
Market Overview:
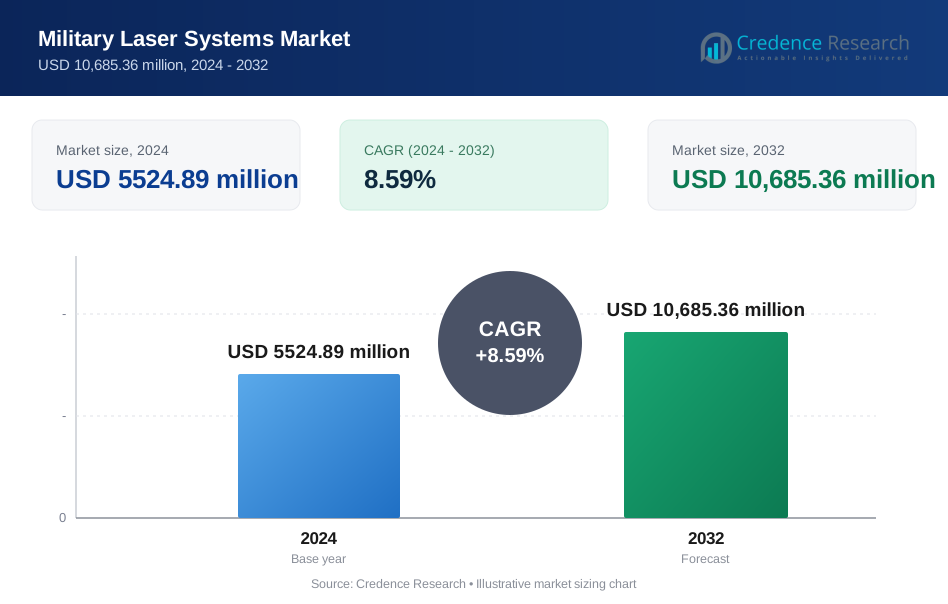
Military Laser Systems Market size was valued at USD 5524.89 million in 2024 and is anticipated to reach USD 10,685.36 million by 2032, at a CAGR of 8.59% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Military Laser Systems Market Size 2024 | USD 5524.89 million |
| Military Laser Systems Market, CAGR | 6.71% |
| Military Laser Systems Market Size 2032 | USD 10,685.36 million |
Key drivers fueling the market expansion include the rising need for advanced weaponry to counter emerging asymmetric warfare threats and the growing focus on improving the effectiveness of military platforms. The rapid evolution of laser technologies, such as fiber lasers and solid-state lasers, is enabling their integration into unmanned systems, naval vessels, and airborne platforms. Additionally, increasing defense budgets in countries like the United States, China, and India are accelerating procurement and development programs. The demand for non-lethal laser-based weapons for crowd control and anti-drone systems is also gaining momentum, supporting the broader adoption of laser technologies across multiple military segments. Rising geopolitical tensions and the proliferation of low-cost unmanned aerial threats have further emphasized the need for directed energy solutions. Additionally, the low operational cost and high accuracy of laser systems make them a favorable alternative to traditional kinetic weapons.
Regionally, North America dominates the military laser systems market, driven by extensive R&D investments, large-scale defense modernization programs, and early adoption of advanced technologies by the U.S. Department of Defense. Europe follows as the second-largest market, supported by joint defense initiatives, NATO modernization projects, and cross-border collaborations. The Asia-Pacific region is expected to register the fastest growth rate over the forecast period, fueled by increasing territorial conflicts, rising military expenditure, and efforts by countries such as China, India, and South Korea to enhance their indigenous defense capabilities. Latin America and the Middle East are also witnessing gradual adoption of military laser systems due to internal security challenges and defense reforms. These regional dynamics, combined with global strategic alliances, position the Military Laser Systems Market for sustained long-term growth.
Market Insights:
- The Military Laser Systems Market was valued at USD 5524.89 million in 2024 and is projected to reach USD 10,685.36 million by 2032, registering a CAGR of 8.59% during the forecast period.
- Rising demand for precision-guided weapons with minimal collateral damage is accelerating the adoption of laser-based systems in modern military operations.
- The market is expanding due to the increasing threat from low-cost drones and asymmetric warfare tactics, which laser systems can counter effectively.
- Countries like the United States, China, and India are investing heavily in laser technology as part of defense modernization and strategic deterrence.
- Integration of fiber and solid-state lasers into autonomous systems, naval vessels, and airborne platforms is enhancing mission flexibility and responsiveness.
- Technical challenges related to power supply, beam stability, and weather interference remain barriers to large-scale deployment and field reliability.
- North America leads the market with 42% share in 2024, followed by Europe at 27%, while Asia Pacific emerges as the fastest-growing region driven by rising geopolitical tensions and regional defense initiatives.
Market Drivers:
Rising Demand for Precision and Low-Collateral Damage Weapons
The growing preference for precision-guided systems with minimal collateral damage is a major driver of the Military Laser Systems Market. Laser-based weapons offer high accuracy and rapid target engagement, making them suitable for modern combat scenarios. Militaries worldwide are prioritizing technologies that can neutralize threats quickly while avoiding unintended casualties. The ability of laser systems to focus energy on specific targets without explosive impact makes them an attractive alternative to conventional weapons. This demand aligns with the global shift toward smarter, more controlled warfare. The Military Laser Systems Market benefits from the increasing integration of precision technologies into land, air, and naval platforms.
Growing Threats from Asymmetric Warfare and Low-Cost Drones
Modern conflicts increasingly involve asymmetric threats such as insurgents, unmanned aerial vehicles, and irregular combatants. These evolving challenges require flexible, scalable solutions, which laser systems provide. The Military Laser Systems Market gains momentum from its role in countering drones and other emerging threats that evade traditional defense systems. Directed energy weapons are particularly effective in disabling surveillance drones and small attack UAVs in real time. This capability enhances perimeter defense and improves mission safety in contested environments. Governments are prioritizing investments in systems that can adapt to unconventional warfare, increasing market traction.
- For instance, Israel’s Ministry of Defense announced that its high-energy laser weapons have been successfully used in combat operations since 2024, with Air Defense units deploying several prototypes developed by Rafael Advanced Defense Systems to destroy dozens of loitering weapons and one-way attack drones on multiple fronts during the Swords of Iron War.
Increased Defense Budgets and Focus on Technological Superiority
The rise in global defense spending is fueling innovation and procurement in advanced weapon systems. Countries such as the United States, China, and India are allocating significant funds to directed energy research and deployment. The Military Laser Systems Market reflects this investment trend, with a surge in development contracts and prototype testing. Defense agencies are focusing on achieving battlefield superiority through next-generation systems that reduce logistic footprints and increase mission effectiveness. Laser systems provide high operational efficiency, low per-shot cost, and minimal maintenance. It strengthens the case for widespread adoption across all military branches.
- For instance, the United States Department of Defense has emphasized directed energy weapons in its fiscal year 2024 funding, with substantial allocations supporting research, development, and integration of these systems into platforms such as ships, aircraft, and ground vehicles.
Integration of Lasers into Multi-Domain and Autonomous Platforms
The shift toward multi-domain operations has intensified the need for adaptable, interoperable weapons. Laser systems fit into this framework through their ability to work across land, air, sea, and space platforms. The Military Laser Systems Market is witnessing increased deployment in autonomous systems, including drones and unmanned ground vehicles. These platforms benefit from lasers' compact design, silent operation, and precise targeting. Integration with AI and advanced sensors further enhances system responsiveness and effectiveness in dynamic combat zones. It positions laser weapons as a core element of future military architecture.
Market Trends:
Shift Toward Directed Energy Weapons for Next-Generation Combat Readiness
Defense agencies are prioritizing the development and deployment of directed energy weapons to enhance combat readiness. The Military Laser Systems Market reflects this shift, with growing interest in high-energy laser (HEL) systems capable of intercepting missiles, drones, and artillery shells. These systems offer significant advantages in terms of speed-of-light engagement, reduced logistical demands, and precision targeting. Governments are accelerating field trials and incorporating laser weapons into military exercises to validate performance under real-world conditions. It supports efforts to build agile and scalable defense systems that can address a wide spectrum of threats. The increasing inclusion of laser platforms in defense modernization programs highlights their emerging strategic value.
- For instance, Israel has deployed its Iron Beam high-power laser system, which has successfully intercepted drones and rockets during operational trials, providing an additional layer within its multi-tiered air defense array.
Expansion of Laser Integration into Multi-Platform Defense Systems
Military forces are integrating laser systems into a wider range of platforms, from ground vehicles and naval warships to fighter jets and satellites. The Military Laser Systems Market is benefiting from advancements in miniaturization and thermal management, which allow for deployment in space-constrained environments. It enables armed forces to strengthen their layered defense capabilities with versatile and cost-effective solutions. The adoption of modular laser systems also supports rapid upgrades and mission-specific configurations. This trend aligns with the move toward network-centric warfare, where interoperability and speed are critical. Defense manufacturers are partnering with governments to co-develop systems tailored to evolving operational needs.
- For instance, the European Union’s new Directed Energy Systems project is developing modular, scalable laser systems for integration onto mobile platforms, with a focus on interoperability across European forces.
Market Challenges Analysis:
Technical Barriers to Operational Deployment and Reliability
Despite strong interest, several technical challenges hinder full-scale deployment of laser weapons. The Military Laser Systems Market faces limitations related to power generation, beam control, and thermal management. High-energy lasers require substantial and stable power sources, which are difficult to integrate into mobile or compact platforms. Environmental conditions such as dust, fog, rain, and turbulence reduce beam accuracy and effectiveness. It raises concerns about operational reliability in real-world combat scenarios. Ensuring consistent performance across diverse environments remains a critical barrier to adoption.
- For instance, Lockheed Martin’s Laser Weapon System Demonstrator (LLD) has successfully addressed atmospheric distortion by integrating advanced beam control systems that compensate for temperature gradients and wind, maintaining beam focus and effectiveness during operational tests.
High Development Costs and Complex Regulatory Approvals
Laser systems demand significant research funding, extensive prototyping, and long testing cycles. The Military Laser Systems Market must contend with high upfront costs and uncertain returns on investment for defense contractors. Governments implement strict regulatory and safety protocols, which slow down approval timelines. Export restrictions and international arms control agreements further complicate cross-border technology transfers. It creates hurdles for market expansion, especially in emerging economies with limited defense budgets. These financial and bureaucratic constraints limit the speed of innovation and commercial viability.
Market Opportunities:
Rising Demand for Counter-UAV and Border Security Solutions
The growing threat of low-cost drones and unmanned aerial vehicles presents a major opportunity for laser-based defense systems. The Military Laser Systems Market can capitalize on this need by offering precise, scalable solutions for drone neutralization and perimeter defense. Armed forces seek compact and mobile laser systems capable of neutralizing aerial threats without creating debris or collateral damage. It strengthens homeland security operations and enhances response capabilities in high-risk zones. Governments are funding targeted initiatives focused on anti-drone technologies, opening procurement channels for laser-based systems. This demand supports both portable and vehicle-mounted laser applications.
Expansion into Space-Based and Naval Laser Platforms
Laser technologies have potential for deployment in space-based platforms and advanced naval systems. The Military Laser Systems Market is well-positioned to support these sectors due to the increasing emphasis on missile defense and satellite protection. It benefits from advances in power efficiency, beam focusing, and platform miniaturization. Naval forces aim to equip vessels with lasers for intercepting threats such as anti-ship missiles and small attack boats. Space agencies are exploring directed energy for orbital debris management and satellite shielding. These applications create new revenue streams for defense manufacturers and diversify market growth beyond traditional battlefield uses.
Market Segmentation Analysis:
By Technology
The Military Laser Systems Market is segmented into solid-state lasers, fiber lasers, chemical lasers, and CO₂ lasers. Solid-state lasers account for a major share due to their high power density, durability, and suitability for compact tactical systems. Fiber lasers are increasingly adopted for their superior beam quality and energy efficiency across multiple defense platforms. Chemical lasers offer high power but face integration challenges due to their size and logistical demands. CO₂ lasers are used in niche roles, primarily for range finding and training applications.
By Platform
It covers ground-based, airborne, and naval platforms. Ground-based systems dominate due to ease of deployment, cost-efficiency, and versatility in land-based defense operations. Airborne laser systems are witnessing growth through their integration in aircraft and drones for interception and surveillance. Naval platforms are evolving with rapid adoption of laser-based close-in weapon systems (CIWS) that can defend against missiles, UAVs, and other threats during naval missions.
By Application
The Military Laser Systems Market is categorized into weapons, target designation, rangefinding, and directed energy systems. Weapons represent the largest application area due to growing use in counter-UAV and missile defense operations. Target designation and rangefinding remain critical in battlefield communication and target engagement accuracy. Directed energy systems are gaining momentum as militaries seek non-kinetic, cost-effective alternatives for disabling threats with minimal collateral damage.
Segmentations:
By Platform- Ground-Based
- Airborne
- Naval
- Others
- Weapon Systems
- Target Designation
- Range Finding
- Directed Energy
- Systems
- Others
- Defense Forces
- Homeland Security
- Solid-State Lasers
- Fiber Lasers
- Chemical Lasers
- CO₂ Lasers
- Others
- Less than 50 kW
- 50–100 kW
- More than 100 kW
-
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Regional Analysis:
North America Leads with Strong R&D and Early Adoption
North America held 42% of the global Military Laser Systems Market in 2024, making it the largest regional contributor. The region maintains its lead through strong defense funding, cutting-edge research, and early adoption of directed energy weapons. The U.S. Department of Defense is advancing multiple high-energy laser programs across all military branches. It supports development through consistent procurement, long-term contracts, and collaboration with major defense contractors. Canada also plays a role in regional growth through bilateral defense initiatives and research partnerships. The presence of a robust supply chain and advanced testing infrastructure further solidifies North America's dominance in this sector.
Europe Advances Through Defense Cooperation and NATO Programs
Europe captured 27% of the global Military Laser Systems Market in 2024, ranking as the second-largest regional market. Strong intergovernmental collaboration and NATO-aligned defense projects are central to the region’s momentum. Key countries such as France, Germany, and the United Kingdom are deploying laser-based systems to modernize their armed forces. It aligns with efforts to reduce reliance on conventional arms and adopt energy-efficient, precision-based systems. European defense agencies are promoting the integration of lasers in mobile ground platforms and naval fleets. Cross-border R&D initiatives and co-funded innovation programs support sustained regional growth.
Asia Pacific Emerges as a High-Growth Strategic Market
Asia Pacific accounted for 22% of the global Military Laser Systems Market in 2024 and is projected to grow at the fastest rate during the forecast period. The region is investing heavily in indigenous laser technologies to strengthen military readiness and strategic deterrence. China, India, South Korea, and Japan are accelerating procurement and local development of directed energy systems. It reflects a regional pivot toward advanced defense capabilities in response to escalating territorial and geopolitical tensions. Government-backed R&D, increased defense spending, and local production incentives are driving adoption. Asia Pacific continues to emerge as a major force in shaping the future landscape of laser-based military technologies.
Key Player Analysis:
- Lockheed Martin Corporation
- Rheinmetall AG
- Thales Group
- The Boeing Company
- Northrop Grumman Corporation
- L3Harris Technologies Inc.
- BAE System
- RTX Corporation
- Others
Competitive Analysis:
The Military Laser Systems Market features intense competition among established defense contractors and advanced technology firms. Key players include Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies Corporation, BAE Systems plc, and Thales Group. These companies invest heavily in research and development to enhance laser power, targeting precision, and operational flexibility. It fosters competitive differentiation through integrated weapon solutions, rapid deployment capabilities, and modular designs suited for various platforms. Strategic collaborations with defense agencies and military modernization programs further strengthen their market position. Emerging players focus on compact and energy-efficient systems to meet evolving tactical needs. The market also sees rising interest from startups specializing in directed energy and photonics technologies. Geopolitical tensions, increasing asymmetric threats, and national defense initiatives drive sustained investment in laser-based solutions, prompting continuous innovation and competitive alignment across global suppliers.
Recent Developments:
- In March 2025, Raytheon (an RTX business) launched a new variant of its Coyote® unmanned aerial system, the Coyote LE SR, from a helicopter.
- In April 2025, Lockheed Martin announced the acquisition of the Rapid Solutions business of Amentum, expanding its capabilities in airborne and space-based ISR (intelligence, surveillance, reconnaissance) and tactical systems.
- In February 2025, Thales partnered with Cubic to launch next-generation eSIM solutions for connected vehicles, leveraging Thales’s eSIM management platform.
Market Concentration & Characteristics:
The Military Laser Systems Market exhibits a moderately concentrated structure, with a few dominant players controlling a significant share. It is characterized by high entry barriers due to stringent defense regulations, complex technology requirements, and capital-intensive development. Leading companies maintain strong government ties and long-term contracts, which reinforces their market hold. The market emphasizes performance reliability, power efficiency, and integration versatility across platforms. It prioritizes innovation in directed energy applications and compact system designs to meet modern combat demands. The competitive landscape remains shaped by defense budgets, evolving threat scenarios, and the pace of technological advancement. Procurement cycles are often long and influenced by geopolitical alliances and strategic defense policies. Standardization and interoperability are emerging as critical criteria in system adoption across multi-domain operations.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Platform, Application, End-Use, Output Power and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Defense agencies are integrating high-energy lasers into ground vehicles, ships, and aircraft to improve precision targeting and threat mitigation.
- Directed energy weapons are gaining favor for offering scalable and cost-efficient alternatives to conventional interceptors.
- Fiber laser systems are advancing in power density and beam quality, supporting broader adoption across tactical platforms.
- Naval forces are deploying ship-mounted lasers to counter missiles, UAVs, and swarm threats with rapid engagement.
- Airborne laser platforms are expected to expand in use for intercepting drones and supporting aerial superiority missions.
- Ground-based systems will play a central role in perimeter security and mobile battlefield applications.
- Continued R&D focuses on improving power efficiency, thermal control, and beam stability to enhance system reliability.
- International defense partnerships and joint ventures are accelerating the operational deployment of next-generation laser solutions.
- AI integration and advanced sensors will increase accuracy, reduce reaction times, and improve autonomous threat response.
- Military laser systems are set to become vital components of modern warfare strategies, offering adaptable and low-collateral defense options.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Precision and Low-Collateral Damage Weapons
Military laser systems offer high accuracy and the ability to neutralize threats with minimal collateral damage, making them increasingly attractive for modern combat scenarios where precision is critical and unintended casualties must be avoided.
Countering Asymmetric Warfare and Drone Threats
The proliferation of low-cost drones and asymmetric warfare tactics has driven militaries to adopt laser systems, which provide rapid, scalable, and cost-effective solutions for neutralizing UAVs and unconventional threats that evade traditional defenses.
Rising Defense Budgets and Focus on Technological Superiority
Increased global defense spending, particularly in the United States, China, and India, is fueling investment in advanced laser technologies as militaries seek to maintain strategic and technological superiority through next-generation directed energy weapons.
Integration into Multi-Domain and Autonomous Platforms
The adaptability of laser systems for use across ground, air, and naval platforms - including integration with autonomous vehicles - enhances mission flexibility and supports the shift toward multi-domain operations in modern military strategies.
Advancements in Laser Technology and Operational Efficiency
Ongoing improvements in fiber and solid-state laser technologies are enabling higher power densities, better beam quality, and lower operational costs, making laser systems more reliable and attractive for widespread military adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size and growth rate of the Military Laser Systems Market?
What factors are driving the Military Laser Systems Market?
Which laser technologies are commonly used in military systems?
Which regions are leading in the adoption of military laser systems?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Platform
- 1.2.1 Ground-Based
- 1.2.2 Airborne
- 1.2.3 Naval
- 1.2.4 Others
- 1.3 By Technology
- 1.3.1 Solid-State Lasers
- 1.3.2 Fiber Lasers
- 1.3.3 Chemical Lasers
- 1.3.4 CO₂ Lasers
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Weapon Systems
- 1.4.2 Target Designation
- 1.4.3 Range Finding
- 1.4.4 Directed Energy Systems
- 1.4.5 Others
- 1.5 By Output Power
- 1.5.1 Less than 50 kW
- 1.5.2 50–100 kW
- 1.5.3 More than 100 kW
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5524.89 million → 2032: USD 10,685.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Military Laser Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Military Laser Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Military Laser Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Military Laser Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Military Laser Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Military Laser Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Military Laser Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Military Laser Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5524.89 million → 2032: USD 10,685.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Military Laser Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Platform - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Ground-Based
- 12.3.7.2 Airborne
- 12.3.7.3 Naval
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solid-State Lasers
- 12.4.7.2 Fiber Lasers
- 12.4.7.3 Chemical Lasers
- 12.4.7.4 CO₂ Lasers
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Weapon Systems
- 12.5.7.2 Target Designation
- 12.5.7.3 Range Finding
- 12.5.7.4 Directed Energy Systems
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Output Power - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Less than 50 kW
- 12.6.7.2 50–100 kW
- 12.6.7.3 More than 100 kW
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Military Laser Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Military Laser Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Military Laser Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Military Laser Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lockheed Martin Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Northrop Grumman Corporation
- 18.4 Raytheon Technologies Corporation (RTX)
- 18.5 BAE Systems plc
- 18.6 Thales Group
- 18.7 Rheinmetall AG
- 18.8 L3Harris Technologies Inc.
- 18.9 The Boeing Company
- 18.10 Leonardo S.p.A.
- 18.11 Elbit Systems Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

