
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Military Lighting Market Size 2024 | USD 654 million |
| Military Lighting Market, CAGR | 7.2% |
| Military Lighting Market Size 2032 | SD 1140 million |
Market Overview:
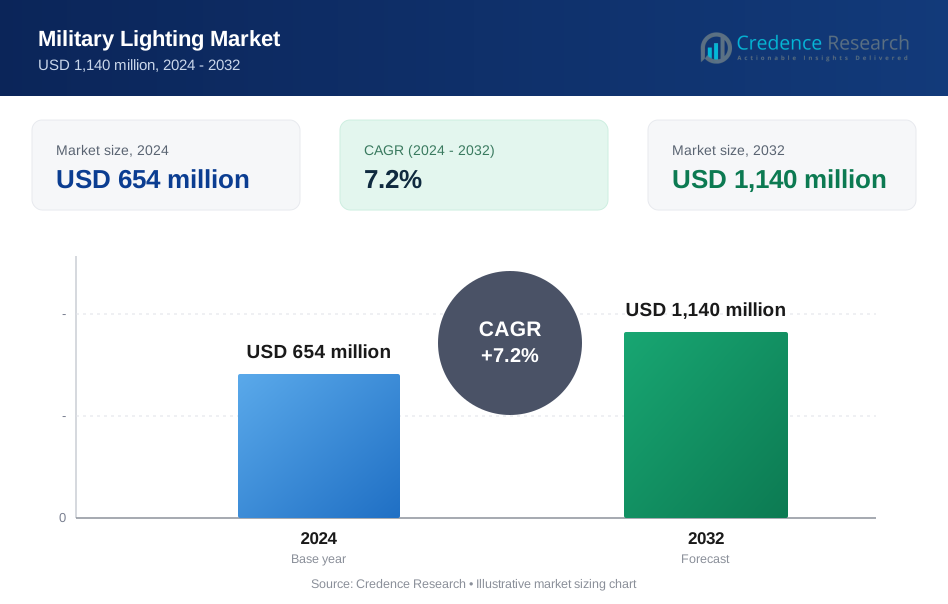
Military Lighting Market size was valued at USD 654 million in 2024 and is anticipated to reach USD 1140 million by 2032, at a CAGR of 7.2% during the forecast period (2024-2032).
Key factors fueling market expansion include the rising emphasis on enhancing battlefield visibility, situational awareness, and operational safety. Modern militaries are investing heavily in upgrading legacy lighting systems with smart, low-maintenance, and energy-efficient alternatives. The integration of advanced lighting with night vision compatibility and infrared (IR) capabilities is becoming essential in tactical missions. Growing procurement of unmanned aerial vehicles (UAVs), armored vehicles, and naval fleets has intensified the demand for lightweight, durable, and versatile lighting technologies. Furthermore, increasing defense budgets and modernization programs in the United States, China, India, and several NATO countries are accelerating innovation and deployment of advanced lighting solutions for both combat and non-combat applications. The need for interoperability in multinational operations is also influencing the standardization of lighting systems. Evolving battlefield scenarios require rapid deployment of adaptive lighting technologies suitable for dynamic mission requirements.
Regionally, North America dominates the Military Lighting Market, holding the largest market share in 2024 due to high defense spending, extensive military modernization efforts, and a robust presence of leading manufacturers. The U.S. Department of Defense continues to prioritize next-generation military hardware, including advanced lighting systems for land, air, and maritime platforms. Europe holds a substantial share, supported by strong investments in NATO-led programs and growing focus on energy-efficient defense infrastructure. Regional defense suppliers are actively collaborating with global OEMs to co-develop technologically advanced lighting systems. The Asia-Pacific region is emerging as a high-growth area, driven by expanding defense budgets and escalating geopolitical tensions that are prompting countries like China, India, and South Korea to invest in modern military capabilities, including advanced lighting systems. Rapid indigenous defense production and technological partnerships in the region are also accelerating market entry for global lighting technology providers.
Market Insights:
- The Military Lighting Market was valued at USD 654 million in 2024 and is projected to reach USD 1,140 million by 2032, registering a CAGR of 7.2% during the forecast period.
- Rising emphasis on battlefield visibility, operational safety, and situational awareness is driving the demand for advanced lighting systems with infrared and night vision compatibility.
- Defense agencies are actively modernizing legacy platforms with smart, energy-efficient lighting solutions that reduce maintenance and enhance durability in harsh conditions.
- Growing adoption of unmanned aerial vehicles (UAVs) and autonomous systems is boosting the need for compact, lightweight, and covert lighting technologies.
- Integration of lighting with broader defense systems, including navigation and communication units, is enhancing mission efficiency and supporting real-time operational control.
- High procurement costs, integration complexity, and stringent regulatory compliance remain key challenges for manufacturers and slow adoption in smaller defense markets.
- North America led the market with 42% share in 2024, followed by Europe with 28% and Asia-Pacific with 21%, driven by modernization programs and increased defense investments.
Market Drivers:
Rising Demand for Enhanced Battlefield Visibility and Tactical Superiority
The growing need for superior battlefield visibility is a key driver shaping the Military Lighting Market. Armed forces are prioritizing lighting systems that support night operations, low-visibility conditions, and mission-specific requirements. These solutions must offer high reliability, precision illumination, and compatibility with night vision devices. Tactical superiority often depends on the ability to maneuver effectively in darkness, making lighting a critical asset. Modern LED technologies provide focused beams, reduced power consumption, and minimal heat signatures. It helps reduce detection risks while maintaining operational effectiveness. The Military Lighting Market is responding with advanced systems tailored for land, air, and naval platforms.
Modernization of Legacy Platforms with Energy-Efficient Solutions
Global defense agencies are accelerating efforts to replace outdated lighting infrastructure with smart, energy-efficient systems. Traditional incandescent and halogen systems are being phased out in favor of LEDs and other advanced technologies. These new solutions offer longer life cycles, reduced maintenance needs, and superior environmental resilience. Energy-efficient lighting also aligns with military goals to reduce logistic loads and fuel consumption. It supports extended operational endurance, particularly in remote or hostile environments. The Military Lighting Market is benefiting from government-funded modernization programs focused on upgrading vehicle fleets, aircraft, and base infrastructure.
- For instance, the U.S. General Services Administration (GSA), in collaboration with the Pacific Northwest National Laboratory, recently released LED Lighting and Controls Guidance for Federal Buildings as part of its sustainability initiatives.
Growth in Procurement of UAVs and Autonomous Platforms
The increasing deployment of unmanned aerial vehicles (UAVs), ground robots, and autonomous systems is driving demand for compact, lightweight, and adaptable lighting solutions. These platforms require low-profile lights that deliver optimal performance without compromising agility or endurance. Infrared and covert lighting technologies are especially critical for stealth operations. It enhances surveillance, target acquisition, and nighttime reconnaissance. The Military Lighting Market is aligning with defense trends favoring unmanned systems for both tactical and support roles. This shift creates ongoing opportunities for lighting innovations tailored to autonomous missions.
- For instance, the Indian Army signed a contract to procure high-altitude SWITCH UAVs from ideaForge, an indigenous start-up, for surveillance operations.
Integration of Lighting with Advanced Defense Systems
Lighting systems are now part of integrated defense ecosystems that include communication, navigation, and targeting systems. Militaries are demanding modular and interoperable lighting that can seamlessly interact with broader digital platforms. Embedded lighting systems must support real-time control, adaptive brightness, and remote diagnostics. It contributes to the effectiveness and safety of mission-critical operations. The Military Lighting Market is witnessing an increased focus on smart lighting capable of responding dynamically to environmental and mission conditions. Manufacturers are investing in R&D to create versatile systems that enhance operational readiness and efficiency.
Market Trends:
Adoption of Smart and Adaptive Lighting Technologies Across Military Platforms
The integration of smart and adaptive lighting technologies is a growing trend in the Military Lighting Market. Armed forces are shifting toward lighting systems that offer real-time adjustments based on ambient conditions and mission requirements. These systems can automatically adapt brightness, beam direction, and color temperature to improve visibility and reduce energy consumption. Smart lighting supports integration with onboard systems such as sensors, navigation units, and communication networks. It enhances situational awareness and improves safety across air, land, and naval platforms. The Military Lighting Market is evolving with sensor-enabled solutions that support remote diagnostics and predictive maintenance, improving operational reliability and lifecycle performance.
- For instance, the U.S. Army’s comprehensive plan to upgrade all field lighting systems to LED technology demonstrates the commitment to leveraging smart and adaptive lighting for enhanced operational effectiveness and energy efficiency.
Focus on Infrared and Covert Lighting for Stealth Operations
Infrared (IR) and covert lighting technologies are gaining traction to meet the increasing demand for stealth and low-signature operations. These systems allow troops and equipment to remain undetected while maintaining visibility for mission-critical tasks. IR-compatible lighting works seamlessly with night vision systems, providing operational advantage during nighttime or low-light missions. It is becoming essential in special operations, UAV surveillance, and reconnaissance missions. The Military Lighting Market is witnessing increased investments in non-visible spectrum lighting to align with modern combat strategies. Global defense agencies are adopting these technologies to enhance their ability to operate effectively in contested and hostile environments.
- For instance, the U.S. Army has awarded contracts for advanced infrared illuminators to be used on armored combat vehicles, significantly improving battlefield night vision capabilities and supporting covert navigation and targeting in challenging environments.
Market Challenges Analysis:
High Cost and Complex Integration of Advanced Lighting Systems
The high cost of advanced military lighting systems presents a major challenge for widespread adoption, especially in developing defense markets. Smart and adaptive lighting technologies involve complex design, specialized materials, and integration with command systems, which increases procurement and maintenance costs. Budget constraints can delay upgrades and restrict deployments to only priority units. Integration with legacy systems often requires extensive customization and retrofitting. It complicates logistics and increases downtime during transitions. The Military Lighting Market faces barriers in scalability, especially for small and mid-sized defense forces seeking cost-effective solutions.
- For instance, in April 2024, the U.S. Army announced a comprehensive plan to upgrade all field lighting systems to LED technology, aiming to enhance energy efficiency, reduce maintenance costs, and improve operational effectiveness over the next five years.
Stringent Regulatory Standards and Reliability Requirements
Military lighting solutions must meet rigorous regulatory and operational standards, which slows down product development and approval timelines. These systems need to function flawlessly in extreme temperatures, high-pressure environments, and combat scenarios. Ensuring consistent performance under variable conditions demands rigorous testing and certification. It challenges manufacturers to balance innovation with compliance and durability. The Military Lighting Market must navigate long defense procurement cycles and complex quality assurance protocols. These regulatory demands can hinder time-to-market and limit supplier flexibility.
Market Opportunities:
ising Demand for Modernization in Emerging Defense Economies
Emerging defense markets are creating significant growth opportunities for the Military Lighting Market. Countries across Asia, the Middle East, and Latin America are expanding their defense budgets to modernize fleets and infrastructure. These programs include upgrading lighting systems in vehicles, aircraft, and naval platforms to meet modern combat requirements. The demand for cost-effective, durable, and energy-efficient solutions is rising in parallel with these investments. It enables suppliers to offer modular and scalable lighting systems tailored for regional operational needs. Local partnerships and technology transfers can accelerate market penetration and long-term procurement contracts.
Expansion of Unmanned and Space-Based Military Applications
The growing use of unmanned aerial systems, ground robots, and space-based platforms offers a new frontier for lighting innovations. These applications require ultra-lightweight, high-performance lighting that functions under extreme operational constraints. The Military Lighting Market can capitalize on these requirements by developing compact systems with infrared and adaptive features. It supports long-duration missions, stealth operations, and advanced navigation. As militaries invest in satellite defense systems and autonomous technologies, lighting becomes an integral part of multi-domain capabilities. This trend opens new segments and use cases for advanced military lighting manufacturers.
Market Segmentation Analysis:
LED Technology Leads Due to Efficiency and Reliability
By technology, the LED segment dominates the Military Lighting Market due to its energy efficiency, durability, and low thermal output. LEDs provide consistent performance in extreme conditions, making them ideal for combat environments. Their long service life reduces maintenance cycles and supports mission continuity. Smart LED systems integrated with sensors and control features are gaining traction across modern military platforms. It enables real-time adjustments to illumination levels based on situational needs. The adoption of LED lighting aligns with military goals of reducing power consumption and operational costs.
Internal Lighting Systems Hold the Largest Share by Type
By type, internal lighting leads the market due to its vital role in cockpit, cabin, and compartment illumination. These systems enhance visibility for navigation, equipment handling, and personnel safety under night-time or low-light conditions. It improves operational efficiency and reduces error rates during mission-critical activities. External lighting is also witnessing growth, driven by its use in vehicle headlights, landing lights, and signal systems. Tactical lighting requirements in combat and reconnaissance vehicles continue to expand the segment scope.
Ground Forces Drive Demand Across Application Segments
By application, ground forces represent the largest segment due to the broad deployment of lighting systems across tanks, armored vehicles, and troop carriers. It supports operational visibility, signaling, and tactical concealment. Continued investments in land-based platforms across major defense economies are sustaining growth. Airborne and naval forces also contribute to market expansion with increasing procurement of aircraft and ships requiring advanced, low-maintenance lighting systems. These segments demand precision-engineered lighting that integrates with navigation and combat systems.
Segmentations:
By Technology:
- LED
- Incandescent
- Fluorescent
- Halogen
- Others
By Type:
- Internal Lighting
- External Lighting
By Application:
- Ground Forces
- Airborne Forces
- Naval Forces
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leads the Market Driven by Robust Defense Spending
North America held 42% of the Military Lighting Market share in 2024, driven by the United States’ unmatched defense budget and sustained technological advancement. The region benefits from robust modernization programs and frequent procurement of high-performance lighting systems across land, air, and naval platforms. The U.S. Department of Defense emphasizes durable, energy-efficient, and stealth-compatible lighting to improve battlefield effectiveness. Leading manufacturers based in the U.S. drive innovation in infrared, night vision-compatible, and sensor-integrated lighting systems. It accelerates deployment across diverse mission environments and supports joint operations. Canada contributes to regional demand through its military vehicle and aircraft upgrades under NATO-aligned initiatives.
Europe Advances Through Strategic Defense Collaborations
Europe captured 28% of the global Military Lighting Market revenue in 2024, supported by joint defense initiatives and NATO-aligned equipment upgrades. Countries including France, Germany, and the United Kingdom are deploying advanced lighting in next-generation armored vehicles, aircraft, and naval fleets. The region focuses on modular, low-maintenance lighting solutions tailored for night operations and extreme weather conditions. It supports military readiness and export competitiveness. European defense programs prioritize sustainability, prompting adoption of energy-efficient lighting infrastructure. Strategic investments in R&D and regional manufacturing capabilities further strengthen Europe’s market position.
Asia-Pacific Emerges as the Fastest-Growing Regional Market
Asia-Pacific held 21% of the Military Lighting Market share in 2024, fueled by rising defense budgets and regional security concerns. Countries such as China, India, South Korea, and Japan are expanding their military capabilities across all domains. The demand for reliable, rugged lighting systems is increasing with the deployment of modern armored vehicles, UAVs, and naval platforms. It promotes domestic manufacturing and cross-border technology partnerships. Strategic priorities include enhancing night-time operational effectiveness and reducing maintenance burden. Local suppliers are gaining traction by offering competitive, mission-specific lighting technologies aligned with national defense agendas.
Key Player Analysis:
- United Technologies
- Honeywell International Inc.
- Larson Electronics
- Rockwell Collins
- Raytheon Technologies Inc.
- Lunar Lighting
- Orion Energy Systems
- Revolution Lighting Technologies
Competitive Analysis:
The Military Lighting Market is highly competitive, with key players focusing on innovation, system integration, and durability to meet evolving defense requirements. Leading companies such as Collins Aerospace, Honeywell International Inc., Astronics Corporation, Oxley Group, and Elbit Systems dominate the landscape through strong R&D capabilities and long-standing defense contracts. It encourages continuous product development, particularly in LED-based, night vision-compatible, and infrared lighting systems. Strategic collaborations with military agencies and global OEMs support market expansion and secure long-term procurement deals. Companies are also investing in compact, energy-efficient solutions to align with next-generation military platforms. Emerging players are entering the market by offering cost-effective and customized solutions tailored to regional defense needs. Technological differentiation, compliance with military standards, and reliability under harsh conditions remain key factors influencing market position. The Military Lighting Market rewards manufacturers that deliver scalable, interoperable, and mission-specific lighting systems suited for multi-domain operations.
Recent Developments:
- In May 2025, Honeywell announced the acquisition of Johnson Matthey's Catalyst Technologies business segment for £1.8 billion in an all-cash transaction.
- In March 2025, Raytheon (an RTX business) launched a new variant of its Coyote® unmanned aerial system (UAS), the Coyote LE SR, from a helicopter.
- In April 2025, Raytheon partnered with BrainChip for an Air Force Research Laboratory (AFRL) radar contract.
Market Concentration & Characteristics:
The Military Lighting Market exhibits moderate to high market concentration, with a few established players controlling a significant share due to their advanced technological capabilities and defense partnerships. It is characterized by high entry barriers, driven by stringent regulatory standards, long procurement cycles, and the need for proven reliability in extreme conditions. The market demands specialized, rugged, and mission-adapted lighting systems that integrate with broader defense platforms. Product customization, durability, and night vision compatibility are critical differentiators. It shows a strong emphasis on R&D, with manufacturers prioritizing innovation in LED, infrared, and modular lighting technologies. Long-term government contracts and strategic defense collaborations shape competition and influence supplier relationships.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Defense modernization programs across developed and emerging economies will continue to drive demand for advanced military lighting systems.
- Integration of lighting with digital battlefield systems, including sensors and autonomous platforms, will become more prevalent.
- The adoption of infrared and night vision-compatible lighting will expand, supporting enhanced stealth and low-visibility operations.
- Manufacturers will prioritize lightweight, compact, and energy-efficient designs to meet mobility and endurance requirements of modern platforms.
- Increasing investments in unmanned systems will create new opportunities for lighting solutions tailored to UAVs and ground robots.
- Standardization of military lighting across NATO and allied forces will support interoperability in joint operations.
- Smart lighting technologies with adaptive brightness, diagnostics, and real-time control features will gain wider adoption.
- Regional suppliers in Asia-Pacific and the Middle East will grow through local defense production and strategic partnerships.
- The need for rugged, maintenance-free systems capable of withstanding extreme environments will influence product development.
- Long-term contracts and government-funded R&D initiatives will shape competitive positioning and innovation in the global market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Emphasis on Enhanced Battlefield Visibility and Situational Awareness
Modern militaries require advanced lighting systems to improve visibility and situational awareness during night operations and low-visibility conditions. This demand is driving the adoption of lighting solutions compatible with night vision and infrared technologies, which are critical for tactical superiority.
Modernization of Legacy Military Platforms
Defense agencies are replacing outdated incandescent and halogen lighting with energy-efficient, durable LED systems. These upgrades reduce maintenance needs, extend operational endurance, and align with military goals for sustainability and reduced logistical burdens.
Growth in Unmanned and Autonomous Military Platforms
The increasing deployment of UAVs, ground robots, and autonomous vehicles is fueling demand for compact, lightweight, and covert lighting technologies. These platforms require specialized lighting for stealth, surveillance, and nighttime reconnaissance missions.
Integration with Advanced Defense Systems
Lighting is increasingly being integrated with broader defense ecosystems, including navigation, communication, and targeting systems. This integration enhances mission efficiency, supports real-time operational control, and enables adaptive lighting based on mission requirements.
Rising Defense Budgets and Modernization Programs in Key Regions
Countries such as the United States, China, India, and NATO members are increasing defense spending and investing in modernization programs. These initiatives accelerate the procurement and deployment of advanced lighting systems across land, air, and naval platforms.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and growth forecast of the Military Lighting Market?
What factors are driving the growth of the Military Lighting Market?
Which regions are leading the Military Lighting Market?
What types of platforms are boosting demand for military lighting?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Internal Lighting
- 1.2.2 External Lighting
- 1.3 By Technology
- 1.3.1 LED
- 1.3.2 Incandescent
- 1.3.3 Fluorescent
- 1.3.4 Halogen
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Ground Forces
- 1.4.2 Airborne Forces
- 1.4.3 Naval Forces
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 654 million → 2032: USD 1,140 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Military Lighting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Military Lighting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Military Lighting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Military Lighting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Military Lighting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Military Lighting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Military Lighting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Military Lighting Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 654 million → 2032: USD 1,140 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Military Lighting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Internal Lighting
- 12.3.7.2 External Lighting
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 LED
- 12.4.7.2 Incandescent
- 12.4.7.3 Fluorescent
- 12.4.7.4 Halogen
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ground Forces
- 12.5.7.2 Airborne Forces
- 12.5.7.3 Naval Forces
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Military Lighting End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Military Lighting Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Military Lighting Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Military Lighting Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Raytheon Technologies Inc.
- 18.4 Collins Aerospace (Raytheon Technologies)
- 18.5 Larson Electronics
- 18.6 Astronics Corporation
- 18.7 Elbit Systems
- 18.8 Oxley Group
- 18.9 Lunar Lighting
- 18.10 Orion Energy Systems
- 18.11 Revolution Lighting Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

