
Mobility Aid Devices Market Overview:
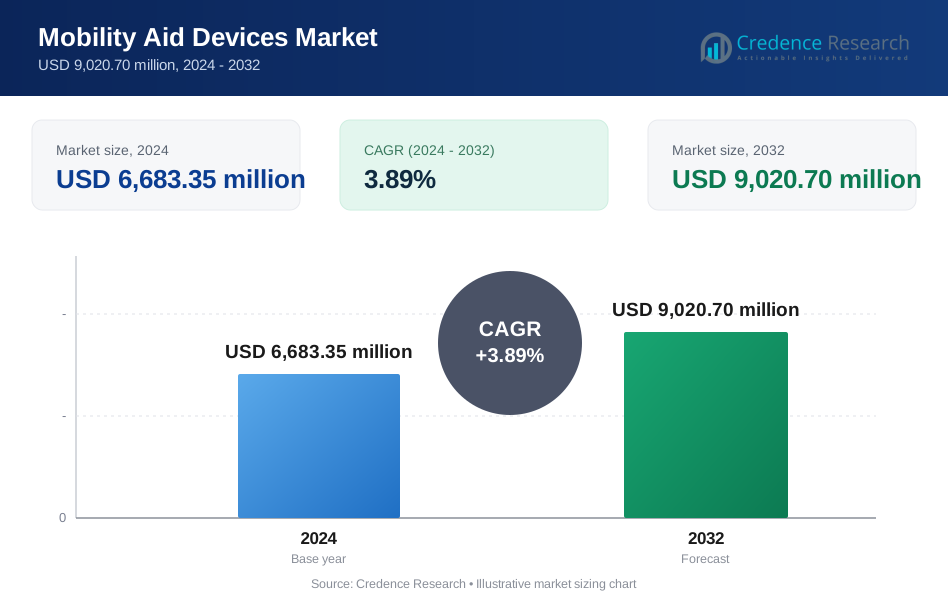
The Mobility Aid Devices market size was valued at USD 6,120.00 million in 2018 and increased to USD 6,683.35 million in 2024. It is anticipated to reach USD 9,020.70 million by 2032, growing at a CAGR of 3.89% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobility Aid Devices Market Size 2024 | USD 6,683.35 million |
| Mobility Aid Devices Market, CAGR | 3.89% |
| Mobility Aid Devices Market Size 2032 | USD 9,020.70 million |
The mobility aid devices market is led by prominent players including Invacare Corporation, Sunrise Medical, Ottobock Healthcare GmbH, Permobil AB, and Pride Mobility Products Corporation. These companies dominate due to their broad product portfolios, global distribution networks, and continuous innovation in powered and manual mobility solutions. Invacare and Pride Mobility hold strong positions in North America, while Ottobock and Sunrise Medical maintain leadership in Europe. Permobil shows notable growth in both regions through its focus on high-end powered devices. In 2024, North America accounted for 36.1% of the global market share, making it the leading region, followed by Asia Pacific with 31.5%. These regions benefit from aging populations, advanced healthcare systems, and increasing demand for personalized and smart mobility solutions. Market leaders compete on technology integration, comfort, and service support, while expanding into emerging markets through strategic partnerships and localized product offerings.

Mobility Aid Devices Market Insights
- The global Mobility Aid Devices market grew from USD 6,120.00 million in 2018 to USD 6,683.35 million in 2024, and is projected to reach USD 9,020.70 million by 2032, registering a CAGR of 3.89% during the forecast period.
- Rising aging populations and increasing prevalence of mobility-related conditions are driving sustained demand across both homecare and institutional settings.
- The market is witnessing a shift toward powered and smart mobility devices, with features like GPS, fall detection, and real-time health tracking gaining popularity.
- Key players such as Invacare, Ottobock, Sunrise Medical, Permobil, and Pride Mobility compete through innovation, expanding their presence across developed and emerging markets.
- North America leads the market with 36.1% share, followed by Asia Pacific at 31.5%, while wheelchairs dominate the product segment, supported by strong institutional demand and long-term care needs.
Mobility Aid Devices Market Segmentation Analysis:
By Product
Wheelchairs lead the product segment in the Mobility Aid Devices market, accounting for the largest revenue share in 2024. The demand is driven by a growing elderly population, increased incidence of mobility impairments, and technological advancements in wheelchair design, such as lightweight materials and enhanced maneuverability. Mobility scooters are gaining traction due to rising adoption among seniors for outdoor mobility. Walking aids maintain steady demand among individuals with temporary mobility issues. Mobility lifts are increasingly used in homecare and hospital settings, particularly for safe patient transfers and fall prevention.
- For instance, Invacare supplies wheelchairs and scooters sold in over 80 countries, with its power wheelchairs supporting users up to 136 kilograms and offering ranges beyond 20 kilometers per charge.
By End-User
Hospital and nursing homes represent the dominant end-user segment, contributing the highest market share in 2024. Their steady procurement cycles, emphasis on patient mobility, and requirement for durable, multi-user devices support strong product demand. Institutional users, including rehabilitation centers and elderly care facilities, also show increasing adoption of powered and assistive devices. Personal users and individuals contribute significantly to market growth due to rising home-based care, longer lifespans, and improved product availability through online and retail channels, enabling easier access to tailored mobility solutions across age groups.
- For instance, Hillrom equips hospitals globally, with its patient mobility solutions installed in over 100 countries to support inpatient movement and rehabilitation.
By Technology
Manual devices dominate the technology segment with the highest market share in 2024, owing to their affordability, ease of use, and minimal maintenance requirements. These devices remain preferred in low- and middle-income countries where powered alternatives are less accessible. However, powered mobility devices are expanding rapidly due to rising demand for user convenience, especially among the elderly and disabled populations. Smart mobility devices are emerging with integrated sensors, GPS tracking, and remote diagnostics, appealing to tech-savvy users and institutional buyers focused on real-time monitoring and enhanced safety.
Mobility Aid Devices Market Key Growth Drivers
Aging Global Population and Rise in Mobility Disorders
The expanding elderly population is a primary driver for the mobility aid devices market. Individuals aged 65 and above are more prone to arthritis, osteoporosis, and neurological disorders, which limit physical movement and create long-term mobility needs. According to global health data, the proportion of people aged 65+ is projected to double by 2050, significantly increasing demand for wheelchairs, scooters, and walking aids. This demographic shift is especially pronounced in developed nations, where life expectancy is higher and aging-related disabilities are more prevalent. The need for improved quality of life and independent living among seniors supports growing adoption of assistive mobility technologies. Healthcare systems in countries such as Japan, Germany, and the U.S. are investing in elder care infrastructure, further boosting device deployment. Public awareness campaigns and government programs offering subsidies for assistive equipment are also accelerating market penetration in both homecare and institutional settings.
- For instance, Permobil is a global leader in complex rehabilitation technology, delivering advanced mobility solutions including powered and manual wheelchairs to users across more than 70 countries.
Advancements in Assistive Technology and Product Innovation
Technological innovation plays a vital role in driving mobility aid device adoption. Manufacturers are integrating advanced materials, smart sensors, and connectivity features to improve usability and comfort. Lightweight frames, ergonomic designs, and foldable mechanisms now enable better portability and convenience, particularly in urban environments. Powered wheelchairs and mobility scooters with lithium-ion batteries offer extended range and reduced charging times. Smart mobility aids now include GPS tracking, fall detection, and real-time health monitoring, helping caregivers and healthcare providers enhance patient safety. Innovations in electric stair climbers and mobility lifts are expanding product use in multilevel residential spaces. The availability of custom-fit and user-personalized devices ensures better clinical outcomes and user satisfaction. R&D investment from both public and private sectors is creating new product lines with greater automation and intuitive controls, making devices more accessible to users with complex mobility challenges and boosting market growth.
- For instance, Sunrise Medical produces powered wheelchairs with lithium-ion systems delivering driving ranges of up to 30 kilometers per charge, improving outdoor mobility for users.
Expanding Homecare Services and Decentralized Healthcare Models
The global shift toward home-based care is fueling demand for mobility aid devices suited for non-clinical environments. As healthcare systems face cost pressures and hospital overcrowding, care is increasingly shifting to outpatient and home settings. Patients recovering from surgeries or managing chronic illnesses prefer home rehabilitation, which drives the need for accessible, easy-to-use assistive devices. In parallel, the rise of decentralized healthcare delivery models supports investments in portable and compact mobility equipment. Many families opt for home caregiving to ensure personalized attention for elderly or disabled members, especially in the wake of the COVID-19 pandemic. This trend is further supported by the growing availability of e-commerce platforms that allow users to select, compare, and purchase mobility aids online. Governments and insurance providers in developed economies now offer financial support for homecare mobility devices, while aging-in-place policies across regions like North America and Western Europe reinforce long-term market growth in the segment.
Mobility Aid Devices Market Key Trends & Opportunities
Surge in Demand for Powered and Smart Mobility Devices
There is growing demand for powered and smart mobility devices equipped with advanced features. Users increasingly seek devices that require minimal physical effort and offer autonomous mobility. Powered wheelchairs and scooters with joystick controls, smart navigation, and braking assistance appeal to both elderly and disabled users. Integration of IoT features such as fall alerts, route tracking, and remote diagnostics enables better care coordination between users, caregivers, and medical professionals. Companies are also exploring AI-driven systems to adapt to user movement patterns and environmental conditions, improving device intelligence. These innovations are helping shift the market from basic assistive tools to connected health ecosystems. In urban environments, smart scooters and compact powered wheelchairs are gaining popularity for daily commuting. This trend creates new opportunities for manufacturers to offer feature-rich, tech-enabled devices in both personal and institutional settings, especially as user expectations grow around convenience, customization, and safety.
- For instance, Permobil equips its power wheelchairs with integrated electronics supporting programmable drive controls, seat elevation exceeding 30 centimeters, and real-time diagnostics used across clinical and homecare settings.
Rising Investments in Elderly Care Infrastructure and Accessibility Initiatives Governments and private institutions are boosting investments in elderly care infrastructure, driving demand for mobility aid devices across public and private domains. Nations with aging populations are expanding care home capacities, rehabilitation centers, and accessible housing units. These initiatives often include procurement of advanced mobility aids for long-term resident support. At the same time, regulations and incentives aimed at making public spaces, transport systems, and residential buildings more accessible are encouraging individuals to adopt mobility devices for daily use. Global disability rights frameworks and urban planning norms now increasingly mandate the availability of mobility-supportive infrastructure. This includes ramps, lifts, and transport accommodations compatible with wheelchairs and scooters. The combination of regulatory backing and growing infrastructure investment provides sustained momentum for manufacturers. As mobility becomes a key component of inclusive design and elder independence, the industry benefits from a wide array of downstream opportunities linked to public policy and capital deployment.

Mobility Aid Devices Market Key Challenges
High Cost and Limited Reimbursement in Developing Markets
Despite growing need, affordability remains a major barrier in emerging economies. Many high-performance mobility aid devices especially powered and smart models come with elevated price tags due to the use of advanced materials, electronics, and batteries. In countries where public healthcare support is limited, out-of-pocket expenses hinder wide adoption. Furthermore, insurance coverage for mobility aids is often restricted or inconsistent, leaving many users unable to access critical support equipment. Import duties and limited local manufacturing further raise end-user prices. As a result, penetration remains low in large population segments across Asia, Africa, and Latin America. Without adequate reimbursement schemes or government subsidies, market expansion in cost-sensitive regions faces headwinds. Addressing this challenge will require collaboration between policymakers, healthcare providers, and manufacturers to create scalable, low-cost solutions while expanding insurance frameworks for assistive technologies.
Limited Awareness and Social Stigma Around Mobility Device Usage
Another critical challenge is the lack of awareness and persistent social stigma associated with mobility aid devices. In many cultures, using assistive equipment is seen as a sign of weakness or dependency, discouraging individuals from adopting them even when needed. This mindset limits early intervention and delays rehabilitation, especially in middle-aged populations with emerging mobility issues. Additionally, many consumers are unaware of the variety of products available or lack guidance on choosing the right device. Healthcare professionals may also underprescribe assistive devices due to outdated knowledge or lack of product familiarity. These factors contribute to low usage rates despite clinical need. Educational campaigns, user training, and community outreach are essential to normalize assistive device adoption. Creating positive messaging around independence, safety, and improved quality of life can help shift perceptions and boost market engagement across diverse demographic groups.
Mobility Aid Devices Market Regional Analysis
North America
North America led the global mobility aid devices market in 2024, accounting for approximately 36.1% of total revenue. The market grew from USD 2,236.25 million in 2018 to USD 2,412.65 million in 2024 and is projected to reach USD 3,251.98 million by 2032, growing at a CAGR of 3.9%. The region benefits from advanced healthcare infrastructure, strong reimbursement systems, and a rapidly aging population. The U.S. drives most of the demand with its high per capita healthcare spending and widespread adoption of powered and smart mobility devices for elderly care and disability support.
Europe
Europe held a market share of 22.1% in 2024, with the market increasing from USD 1,414.94 million in 2018 to USD 1,476.84 million in 2024, and expected to reach USD 1,866.86 million by 2032, at a CAGR of 3.1%. The market is driven by a growing senior population, government-led accessibility programs, and robust institutional demand. Countries like Germany, France, and the UK have well-established eldercare systems that adopt advanced mobility aids. Regulatory frameworks supporting product standardization and the presence of key manufacturers further enhance Europe's growth potential.
Asia Pacific
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of 4.9%, with a market share of 31.5% in 2024. The market grew from USD 1,863.54 million in 2018 to USD 2,107.57 million in 2024, and is projected to reach USD 3,083.28 million by 2032. Rapid urbanization, increased healthcare spending, and rising elderly populations in China, Japan, and India are key drivers. Government investments in eldercare infrastructure and a growing middle class adopting home-based assistive devices support long-term growth. Regional manufacturers are also launching affordable products tailored for local needs.
Latin America
Latin America accounted for 5.1% of the global market in 2024, with the market growing from USD 318.24 million in 2018 to USD 343.46 million in 2024, and expected to reach USD 422.80 million by 2032, at a CAGR of 2.7%. Brazil and Mexico lead regional demand due to improving healthcare access and rising awareness about mobility assistance. However, limited insurance coverage and economic disparities remain challenges. The region sees steady adoption of manual devices, particularly among low-income users. Efforts to expand elderly care services and local production may support moderate growth.
Middle East
The Middle East held a 2.1% market share in 2024, with the market slightly declining from USD 144.43 million in 2018 to USD 141.64 million in 2024, but projected to recover to USD 159.72 million by 2032, growing at a CAGR of 1.6%. Regional demand is primarily driven by institutional purchases and medical tourism hubs in the UAE and Saudi Arabia. Despite slow growth, ongoing investments in healthcare infrastructure and national disability strategies are improving access. However, awareness gaps and limited local production hinder broader adoption of advanced mobility devices.
Africa
Africa accounted for 3.0% of the global market in 2024, showing notable growth from USD 142.60 million in 2018 to USD 201.20 million in 2024, and expected to reach USD 236.06 million by 2032, at a CAGR of 1.7%. Growth is supported by rising disability cases, post-injury rehabilitation needs, and expansion of community-based health programs. South Africa and Nigeria lead regional demand. However, affordability and infrastructure challenges restrict access to powered or smart devices. Manual wheelchairs and walking aids dominate usage, with NGOs and health ministries playing key roles in device distribution.
Mobility Aid Devices Market Segmentations:
By Product:
- Wheelchairs
- Mobility Scooter
- Walking Aids
- Mobility Lifts
By End-User:
- Personal Users
- Institutional Users
- Individual
- Hospital and Nursing Homes
By Technology:
- Manual Devices
- Powdered Devices
- Smart Devices
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The competitive landscape of the mobility aid devices market is characterized by a mix of global manufacturers and regional players focused on innovation, product expansion, and strategic partnerships. Key companies such as Invacare Corporation, Sunrise Medical, Ottobock Healthcare, Permobil AB, and Pride Mobility Products lead the market with diverse product portfolios, including powered and manual wheelchairs, scooters, and walking aids. These firms invest heavily in R&D to integrate smart technologies and improve device ergonomics. Mergers and acquisitions are common as companies aim to expand geographic reach and manufacturing capabilities. For instance, Ottobock continues to strengthen its position through targeted acquisitions in assistive technology. Regional players like Besco Medical and MEYRA GmbH focus on affordable offerings and domestic distribution networks. Additionally, firms such as Stryker and Medline Industries cater to institutional demand with advanced mobility systems for hospital and eldercare settings. Competitive differentiation increasingly depends on innovation, pricing flexibility, regulatory compliance, and post-sales service.
Key Player Analysis
- Invacare Corporation
- Sunrise Medical (US) LLC
- Ottobock Healthcare GmbH
- Permobil AB
- MEYRA GmbH
- Medline Industries, LP
- Pride Mobility Products Corporation
- Stryker Corporation
- Besco Medical
Recent Developments
- In November 2024, Invacare Holdings Corporation announced the acquisition of its North American business by MIGA Holdings LLC. This strategic move aims to optimize operations and accelerate growth in North America, enhancing Invacare’s ability to meet customer needs and expand its market leadership in healthcare mobility.
- In April 2024, Invacare partnered with Free Wheelchair Mission to launch the "Move for Mobility" initiative. This global fundraising effort, involving employees across 20 countries, aims to provide wheelchairs to individuals in under-resourced communities worldwide. For every $96 raised, a new wheelchair is donated, promoting independence and improved quality of life.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for advanced powered mobility devices will continue rising among aging populations.
- Smart mobility aids with health monitoring features will gain wider adoption.
- Manufacturers will focus on lightweight, foldable, and travel-friendly designs.
- Homecare-based mobility device usage will grow with decentralized healthcare expansion.
- Government support programs will improve access in developing countries.
- Online sales channels will play a key role in reaching individual consumers.
- Customized mobility solutions will increase as users seek personalized comfort.
- Hospitals and nursing homes will remain key institutional buyers for premium devices.
- Innovation in battery technology will enhance the performance of powered mobility products.
- Asia Pacific will emerge as the fastest-growing regional market with rising elderly populations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Global Population and Rise in Mobility Disorders
The increasing proportion of elderly individuals worldwide, particularly those aged 65 and above, is leading to higher prevalence of mobility-impairing conditions such as arthritis and neurological disorders. This demographic shift is fueling sustained demand for mobility aid devices in both homecare and institutional settings.
Advancements in Assistive Technology and Product Innovation
Continuous innovation in device design, including lightweight materials, ergonomic features, and integration of smart technologies like GPS and health monitoring, is making mobility aids more user-friendly and appealing. These advancements are expanding the market by attracting both new users and institutional buyers seeking improved outcomes.
Expanding Homecare Services and Decentralized Healthcare Models
The global trend toward home-based care and outpatient rehabilitation is increasing the need for accessible, easy-to-use mobility devices. As more patients recover or manage chronic conditions at home, demand for portable and user-friendly mobility aids is rising, supported by e-commerce and government reimbursement programs.
Rising Investments in Elderly Care Infrastructure and Accessibility Initiatives
Governments and private sectors are investing in eldercare facilities, accessible housing, and public infrastructure, which drives procurement of advanced mobility aids. Regulatory mandates and incentives for accessibility are further encouraging adoption of mobility devices in both public and private domains.
Shift Toward Powered and Smart Mobility Devices
There is a growing preference for powered and smart mobility aids equipped with features such as joystick controls, fall detection, and real-time diagnostics. These devices offer greater independence and safety, appealing to both elderly users and caregivers, and are driving market growth through enhanced functionality and convenience.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Mobility Aid Devices market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mobility Aid Devices market projected to grow between 2024 and 2032?
Which Mobility Aid Devices market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mobility Aid Devices market?
Who are the leading companies in the Mobility Aid Devices market?
Which region commanded the largest share of the Mobility Aid Devices market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Wheelchairs
- 1.2.2 Mobility Scooter
- 1.2.3 Walking Aids
- 1.2.4 Mobility Lifts
- 1.3 By End-User
- 1.3.1 Personal Users
- 1.3.2 Institutional Users
- 1.3.3 Individual
- 1.3.4 Hospital and Nursing Homes
- 1.4 By Technology
- 1.4.1 Manual Devices
- 1.4.2 Powered Devices
- 1.4.3 Smart Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,683.35 million → 2032: USD 9,020.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobility Aid Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobility Aid Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobility Aid Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobility Aid Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobility Aid Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobility Aid Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobility Aid Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobility Aid Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,683.35 million → 2032: USD 9,020.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobility Aid Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Wheelchairs
- 12.3.7.2 Mobility Scooter
- 12.3.7.3 Walking Aids
- 12.3.7.4 Mobility Lifts
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal Users
- 12.4.7.2 Institutional Users
- 12.4.7.3 Individual
- 12.4.7.4 Hospital and Nursing Homes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Manual Devices
- 12.5.7.2 Powered Devices
- 12.5.7.3 Smart Devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobility Aid Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mobility Aid Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mobility Aid Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mobility Aid Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Invacare Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sunrise Medical (US) LLC
- 18.4 Ottobock Healthcare GmbH
- 18.5 Permobil AB
- 18.6 Pride Mobility Products Corporation
- 18.7 MEYRA GmbH
- 18.8 Medline Industries, LP
- 18.9 Stryker Corporation
- 18.10 Besco Medical
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

