
Market Overview
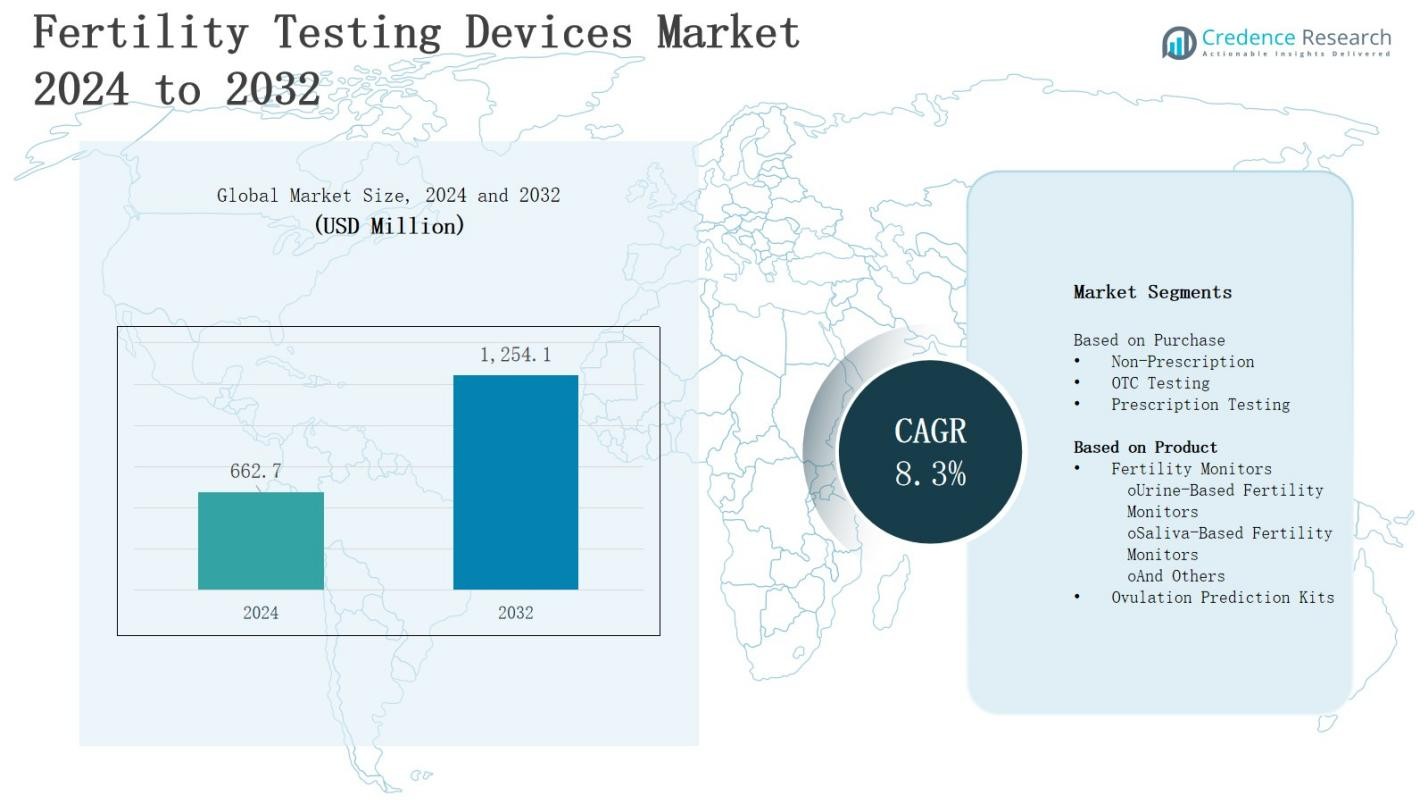
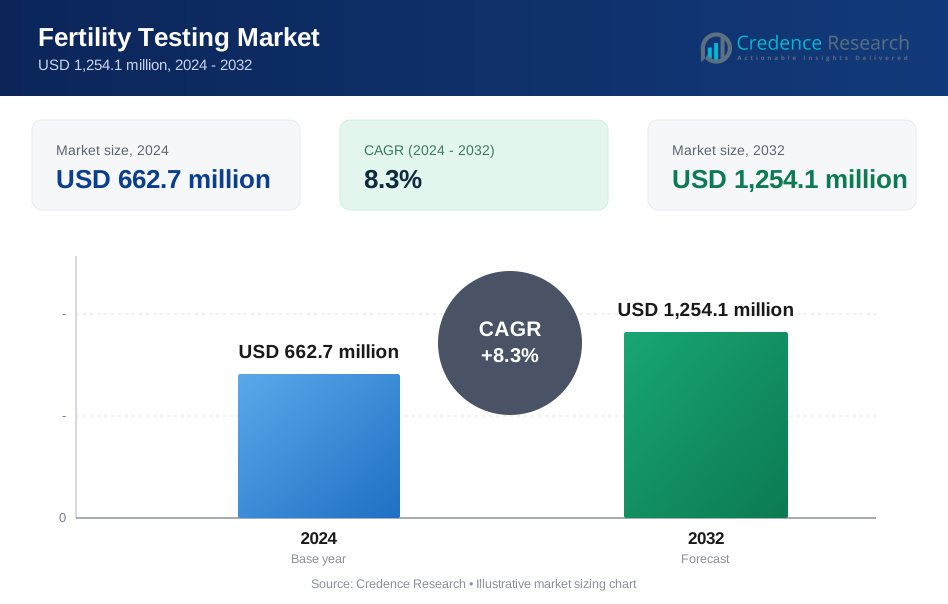
The global fertility testing market is projected to grow from USD 662.7 million in 2024 to USD 1,254.1 million by 2032, registering a CAGR of 8.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fertility Testing Market Size 2024 | USD 662.7 Million |
| Fertility Testing Market, CAGR | 8.3% |
| Fertility Testing Market Size 2032 | USD 1,254.1 Million |
The fertility testing devices market is driven by rising infertility rates, increasing awareness of reproductive health, and the growing adoption of advanced home-based testing solutions. Expanding access to assisted reproductive technologies and the shift toward proactive family planning support market growth. Technological advancements, such as smartphone-connected ovulation monitors and AI-driven fertility tracking, enhance accuracy and user convenience. Trends include the integration of digital health platforms, demand for non-invasive and hormone-based testing, and the expansion of personalized fertility solutions. Increasing healthcare expenditure and supportive government initiatives further strengthen the market’s growth prospects across developed and emerging regions.
The fertility testing devices market spans North America, Europe, Asia-Pacific, and the Rest of the World, each contributing distinct growth drivers. North America leads with advanced healthcare infrastructure and high awareness, while Europe benefits from supportive policies and rising infertility rates. Asia-Pacific shows rapid growth driven by urbanization and increasing healthcare access. The Rest of the World sees demand from improving infrastructure and affordable OTC kits. Key players include Church & Dwight Co. Inc., SPD Swiss Precision Diagnostics GmbH, Quidel Corporation, and Fertility Focus Limited.
Market Insights
- The global fertility testing market is projected to grow from USD 662.7 million in 2024 to USD 1,254.1 million by 2032, registering a CAGR of 8.3% during the forecast period.
- Rising infertility rates, delayed parenthood, and lifestyle-related health issues are driving demand for accurate fertility assessment tools.
- Technological advancements, including smartphone-connected monitors and AI-powered fertility tracking, enhance accuracy, ease of use, and adoption rates.
- Expanding awareness campaigns, healthcare integration, and government programs are improving access to fertility education and testing solutions.
- High costs, limited accessibility in low-income regions, and accuracy concerns remain significant challenges to market growth.
- North America leads with 34% share, followed by Europe at 28%, Asia-Pacific at 25%, and Rest of the World at 13%, each with unique growth drivers.
- Key players include Church & Dwight Co. Inc., SPD Swiss Precision Diagnostics GmbH, Quidel Corporation, and Fertility Focus Limited.
Market Drivers
Rising Prevalence of Infertility and Delayed Parenthood
The fertility testing devices market benefits from the growing prevalence of infertility caused by lifestyle changes, stress, obesity, and underlying medical conditions. Couples are increasingly delaying parenthood due to career priorities and economic considerations, raising the demand for reliable fertility assessment tools. It addresses the need for accurate ovulation prediction and reproductive health monitoring. Rising global infertility rates continue to push healthcare providers and consumers toward early detection and intervention strategies.
- For instance, Ava Women developed wearable fertility trackers that continuously monitor reproductive health, supporting the trend of delayed pregnancies by providing digital, real-time fertility insights.
Technological Advancements in Fertility Testing Solutions
The fertility testing devices market gains momentum from rapid advancements in diagnostic technologies, including digital ovulation monitors, smartphone-integrated testing kits, and AI-powered fertility tracking. These innovations improve accuracy, ease of use, and accessibility, appealing to tech-savvy consumers seeking convenience. It offers non-invasive and hormone-based testing that enables real-time insights into reproductive health. Continuous product innovation enhances adoption rates, making fertility testing more efficient and user-friendly for both clinical and home-based applications.
Increasing Awareness and Access to Reproductive Health Services
The fertility testing devices market experiences growth due to rising awareness campaigns promoting reproductive health and family planning. Government programs, NGOs, and private healthcare providers are improving access to fertility education and affordable testing solutions. It benefits from the integration of these devices into primary healthcare systems, expanding reach in urban and rural areas. Growing social acceptance and open discussions on fertility challenges encourage more individuals to seek early diagnosis and monitoring.
- For instance, Clearblue launched a Bluetooth-enabled pregnancy test that connects to a smartphone app, enhancing user engagement and guidance during testing.
Expansion of Assisted Reproductive Technologies (ART) and Medical Support
The fertility testing devices market strengthens through the parallel growth of assisted reproductive technologies such as IVF and IUI. Accurate fertility testing is critical for optimizing treatment success rates in these procedures. It supports personalized treatment plans by identifying ovulation patterns and hormonal fluctuations. The collaboration between fertility clinics and device manufacturers improves patient outcomes. Expanding insurance coverage and financing options further encourage adoption among couples seeking medical intervention for conception.
Market Trends
Integration of Digital Health and Mobile Applications
The fertility testing devices market is witnessing a strong shift toward digital health integration, with mobile apps and cloud-based platforms enhancing data tracking and interpretation. Consumers increasingly prefer connected devices that sync with smartphones for real-time fertility insights and predictive analytics. It allows users to store, share, and analyze reproductive health data with healthcare professionals. This integration improves accuracy, user engagement, and personalization, creating a seamless link between home-based testing and clinical decision-making.
- For instance, Femometer offers a smart ring that collects and analyzes fertility-related data while syncing with mobile apps, enabling users to share reproductive health information with healthcare professionals for personalized care.
Growing Demand for Non-Invasive and Hormone-Based Testing Methods
The fertility testing devices market benefits from rising consumer preference for non-invasive testing solutions that offer comfort and reliability. Hormone-based urine tests, saliva-based monitors, and wearable sensors are gaining popularity for their convenience and accuracy. It reduces the need for complex laboratory procedures while delivering actionable insights. Manufacturers are investing in research to refine biomarker detection, improve sensitivity, and shorten result times, aligning with the growing demand for user-friendly diagnostic tools.
- For instance, saliva testing labs like ZRT Laboratory utilize non-invasive saliva collection to measure hormones like cortisol, estrogens, progesterone, and androgens. Their advanced liquid chromatography/tandem mass spectrometry (LC-MS/MS) techniques provide precise hormone level readings outside of clinical settings.
Expansion of Home-Based Fertility Monitoring Solutions
The fertility testing devices market is experiencing rapid growth in the home-use segment, driven by consumer interest in privacy, convenience, and cost-effectiveness. Portable and discreet devices allow users to monitor ovulation and hormonal changes without frequent clinical visits. It enables individuals to make informed reproductive decisions on their own terms. Companies are developing compact, AI-enhanced kits that provide lab-quality accuracy, catering to the needs of tech-savvy, health-conscious consumers seeking greater autonomy.
Adoption of AI and Predictive Analytics in Fertility Tracking
The fertility testing devices market is embracing AI-powered algorithms to analyze cycle patterns, hormonal fluctuations, and lifestyle factors for enhanced fertility prediction. Predictive analytics improves conception planning by identifying optimal fertile windows with high precision. It supports healthcare providers in offering tailored treatment recommendations. This trend is driving partnerships between medtech firms and AI developers, fostering the creation of advanced platforms that combine hardware, software, and data science for superior reproductive health management.
Market Challenges Analysis
High Cost and Limited Accessibility in Emerging Markets
The fertility testing devices market faces growth constraints due to high product costs and limited accessibility in low-income and rural regions. Advanced digital monitors and AI-enabled solutions often remain unaffordable for a significant portion of the population. It restricts adoption despite rising awareness of reproductive health. Infrastructural gaps, low healthcare penetration, and lack of insurance coverage further hinder market expansion. Manufacturers must address affordability through localized production, tiered pricing strategies, and distribution partnerships to tap underserved markets.
Accuracy Concerns and Lack of Standardization
The fertility testing devices market encounters challenges related to accuracy, reliability, and standardization of testing outcomes. Variability in hormonal cycles, user errors, and differences in device calibration can lead to inconsistent results, impacting consumer trust. It demands rigorous clinical validation and compliance with international quality standards. Limited regulatory oversight in certain markets increases the risk of substandard products. Addressing these issues through robust R&D, improved product design, and stronger regulatory frameworks is essential for sustained market credibility and growth.
Market Opportunities
Rising Demand for Personalized and Preventive Reproductive Health Solutions
The fertility testing devices market holds significant potential through the growing demand for personalized and preventive reproductive health solutions. Consumers are increasingly seeking tailored fertility insights that align with individual health profiles and lifestyle factors. It enables early detection of potential issues, allowing timely medical intervention and improved conception planning. Integration of wearable devices, AI-driven analytics, and home-based kits supports customization. Expanding interest in holistic wellness and family planning creates opportunities for innovative, user-centric product development.
Untapped Growth Potential in Emerging Economies
The fertility testing devices market can expand substantially in emerging economies with large, underserved populations and rising healthcare awareness. Increasing urbanization, higher disposable incomes, and improved digital connectivity are creating favorable conditions for market entry. It benefits from growing e-commerce penetration, enabling broader distribution of home-based testing kits. Strategic partnerships with local healthcare providers and distributors can strengthen market reach. Government initiatives promoting reproductive health and family planning further enhance adoption prospects in these high-growth regions.
Market Segmentation Analysis:
By Purchase
The fertility testing devices market is segmented by purchase into non-prescription, OTC testing, and prescription testing. Non-prescription and OTC testing products dominate due to their convenience, affordability, and wide availability through pharmacies, retail stores, and e-commerce channels. It caters to consumers seeking privacy and quick results without clinical visits. Prescription testing holds a smaller share but is critical for medically supervised fertility assessments, particularly in complex cases requiring professional interpretation and integration with assisted reproductive treatments.
- For instance, devices like the Mira Starter Kit offer at-home hormone tracking paired with an app to aid in fertility monitoring.
By Product
The fertility testing devices market is categorized by product into fertility monitors and ovulation prediction kits. Fertility monitors, including urine-based, saliva-based, and other types, are gaining traction for their accuracy, digital connectivity, and ability to track multiple cycle parameters. It appeals to tech-savvy users seeking advanced insights into reproductive health. Ovulation prediction kits remain widely adopted for their simplicity and affordability, making them a preferred choice for first-time users and consumers seeking quick, reliable ovulation detection.
- For instance, Clearblue, a brand by SPD Swiss Precision Diagnostics, introduced a Bluetooth-enabled pregnancy test that connects to a smartphone app to guide users through testing and interpreting results, exemplifying the integration of digital technology in fertility monitoring.
Segments:
Based on Purchase
- Non-Prescription
- OTC Testing
- Prescription Testing
Based on Product
- Fertility Monitors
- Urine-Based Fertility Monitors
- Saliva-Based Fertility Monitors
- And Others
- Ovulation Prediction Kits
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds 34% share of the fertility testing devices market, driven by high awareness of reproductive health, advanced healthcare infrastructure, and strong adoption of digital fertility solutions. It benefits from the presence of leading manufacturers and continuous product innovations, including AI-powered monitors and smartphone-enabled testing kits. Insurance coverage for certain fertility-related services also supports growth. The region shows strong demand for home-based, non-prescription fertility tests due to convenience and privacy. Expanding e-commerce distribution further enhances product accessibility and consumer engagement.
Europe
Europe accounts for 28% share of the fertility testing devices market, supported by growing infertility rates, lifestyle shifts, and government initiatives promoting reproductive health awareness. It experiences steady adoption of both OTC and prescription-based fertility tests, driven by robust healthcare systems and favorable reimbursement policies in select countries. The market benefits from technological advancements and collaborations between healthcare providers and device manufacturers. Urban populations exhibit higher demand for connected, data-driven fertility monitoring solutions.
Asia-Pacific
Asia-Pacific captures 25% share of the fertility testing devices market, propelled by a large population base, rising healthcare expenditure, and increasing awareness of fertility management. It gains momentum from rapid urbanization, higher disposable incomes, and expanding access to modern healthcare facilities. Digital adoption is accelerating, with mobile health apps integrating fertility tracking features. Manufacturers target this region with affordable, portable testing solutions to address growing demand in both urban and semi-urban areas.
Rest of the World
The Rest of the World represents 13% share of the fertility testing devices market, with demand emerging in Latin America, the Middle East, and Africa. It is driven by gradual improvements in healthcare infrastructure, growing awareness of reproductive health, and rising penetration of affordable OTC fertility tests. Limited access to advanced diagnostic facilities in certain areas sustains demand for home-based testing kits. Partnerships with local distributors and healthcare providers support market expansion in these regions.
Key Player Analysis
- Quidel Corporation
- Fertility Focus Limited
- Biozhena Corporation
- SPD Swiss Precision Diagnostics GmbH
- Prestige Brands Holdings Inc.
- Geratherm Medical AG
- UEBE Medical GmbH
- HiLin Life Products Inc.
- Babystart Ltd
- AccuQuik
- Church & Dwight Co. Inc.
- Alere Inc.
Competitive Analysis
The fertility testing devices market is characterized by strong competition among established brands and emerging innovators, each focusing on product accuracy, digital integration, and user convenience. It includes major players such as Church & Dwight Co. Inc., SPD Swiss Precision Diagnostics GmbH, Quidel Corporation, Prestige Brands Holdings Inc., HiLin Life Products Inc., Fertility Focus Limited, Geratherm Medical AG, Babystart Ltd, UEBE Medical GmbH, Biozhena Corporation, AccuQuik, and Alere Inc. Companies compete through technological advancements, AI-driven analytics, and smartphone compatibility to enhance user engagement. Strategic partnerships with healthcare providers, e-commerce platforms, and retail chains strengthen distribution networks. Continuous investment in research supports the development of non-invasive, hormone-based, and home-use solutions that meet growing consumer demand. Competitive pricing, targeted marketing campaigns, and global expansion strategies are critical for gaining market share in both developed and emerging economies.
Recent Developments
- In August 2025, Maven Clinic launched its “Cycle Tracker” and male fertility tools, offering personalized predictions, at-home semen tests, and specialist support.
- In April 2024, Clearblue-a flagship brand of SPD Swiss Precision Diagnostics GmbH-rolled out an upgraded version of its Connected Ovulation Test System. The new model features enhanced Bluetooth connectivity and AI-driven cycle prediction, offering users more personalized fertility insights and tighter integration with mobile apps.
- In August 2025, Health-E Commerce announced a collaboration with Fertility Cloud to expand access to at-home fertility testing services through integrated telehealth solutions.
Market Concentration & Characteristics
The fertility testing devices market exhibits moderate concentration, with a mix of global leaders and niche players competing through innovation, brand presence, and distribution reach. It is characterized by steady technological advancements, particularly in AI-powered fertility monitors, smartphone integration, and non-invasive testing methods. Competition focuses on accuracy, user convenience, and affordability to capture both developed and emerging markets. Key companies leverage partnerships with healthcare providers, retail chains, and e-commerce platforms to strengthen market penetration. Regulatory compliance and product standardization play a critical role in maintaining credibility and consumer trust. Demand is fueled by rising infertility rates, growing reproductive health awareness, and expanding home-use adoption. The market structure allows room for new entrants offering specialized or cost-effective solutions while established brands maintain dominance through continuous R&D investment and product diversification.
Report Coverage
The research report offers an in-depth analysis based on Purchase, Product and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising global infertility rates will continue to drive demand for advanced fertility testing solutions.
- Technological integration with AI and mobile health apps will enhance accuracy and user experience.
- Home-based fertility monitoring will gain greater adoption due to convenience and privacy preferences.
- Affordable and portable testing kits will see higher demand in emerging economies.
- Expansion of assisted reproductive technologies will increase the need for precise fertility assessment tools.
- Partnerships between device manufacturers and healthcare providers will strengthen product accessibility.
- Non-invasive and hormone-based testing methods will dominate consumer preference.
- Digital health platforms will support personalized fertility tracking and treatment recommendations.
- E-commerce and online distribution will expand market reach globally.
- Regulatory focus on product quality and standardization will shape competitive dynamics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Infertility and Delayed Parenthood
Increasing infertility rates due to lifestyle changes, stress, and delayed parenthood are driving demand for fertility testing devices, as more individuals and couples seek early and accurate assessment of reproductive health.
Technological Advancements in Fertility Testing Solutions
Innovations such as smartphone-connected monitors, AI-powered fertility tracking, and non-invasive hormone-based tests are enhancing accuracy, convenience, and user engagement, making fertility testing more accessible and appealing.
Increasing Awareness and Access to Reproductive Health Services
Government initiatives, awareness campaigns, and integration of fertility testing into primary healthcare are expanding access to fertility education and affordable testing solutions, especially in urban and semi-urban areas.
Expansion of Assisted Reproductive Technologies (ART)
The growth of ART procedures like IVF and IUI increases the need for precise fertility assessment tools, as accurate testing is critical for optimizing treatment outcomes and supporting personalized reproductive care.
Growth of Home-Based and OTC Fertility Testing
Consumer preference for privacy, convenience, and cost-effectiveness is fueling the adoption of home-based and OTC fertility testing kits, supported by expanding e-commerce and retail distribution channels.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for fertility testing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the fertility testing market projected to grow between 2025 and 2032?
Which fertility testing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the fertility testing market?
Who are the leading companies in the fertility testing market?
Which region commanded the largest share of the fertility testing market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Fertility Monitors
- 1.2.2 Ovulation Prediction Kits
- 1.3 By Purchase
- 1.3.1 Non-Prescription
- 1.3.2 OTC Testing
- 1.3.3 Prescription Testing
- 1.4 By Fertility Monitor Type
- 1.4.1 Urine-Based Fertility Monitors
- 1.4.2 Saliva-Based Fertility Monitors
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 662.7 million → 2032: USD 1,254.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fertility Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fertility Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fertility Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fertility Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fertility Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fertility Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fertility Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fertility Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 662.7 million → 2032: USD 1,254.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fertility Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fertility Monitors
- 12.3.7.2 Ovulation Prediction Kits
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Purchase - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Non-Prescription
- 12.4.7.2 OTC Testing
- 12.4.7.3 Prescription Testing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Fertility Monitor Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Urine-Based Fertility Monitors
- 12.5.7.2 Saliva-Based Fertility Monitors
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fertility Testing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Fertility Testing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Fertility Testing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Church & Dwight Co. Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 SPD Swiss Precision Diagnostics GmbH
- 17.4 Quidel Corporation
- 17.5 Fertility Focus Limited
- 17.6 Prestige Brands Holdings Inc.
- 17.7 Geratherm Medical AG
- 17.8 UEBE Medical GmbH
- 17.9 HiLin Life Products Inc.
- 17.10 Babystart Ltd
- 17.11 Alere Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

