
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
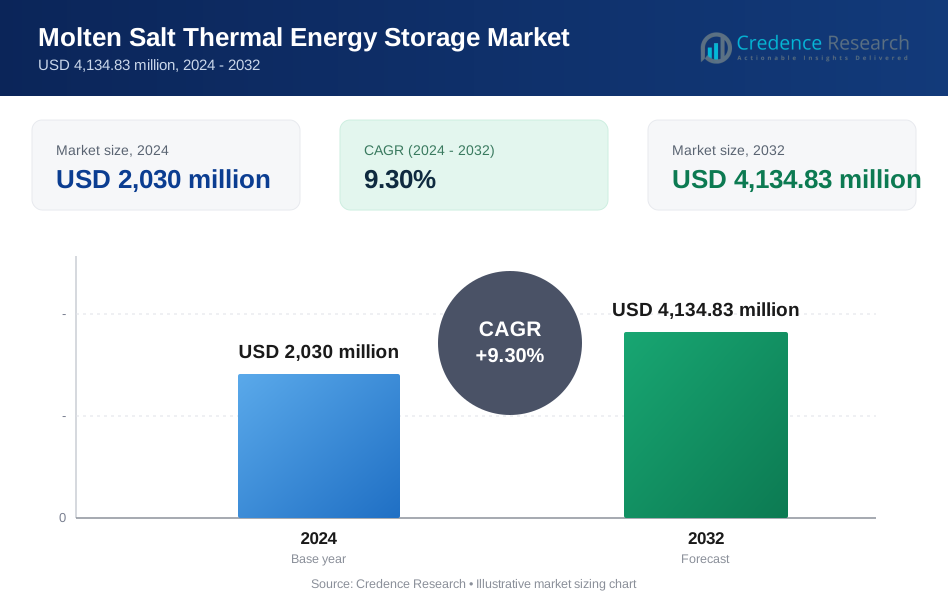
| Molten Salt Thermal Energy Storage Market Size 2024 | USD 2,030 million |
| Molten Salt Thermal Energy Storage Market, CAGR | 9.30% |
| Molten Salt Thermal Energy Storage Market Size 2032 | USD 4,134.83 million |
Market Overview:
The Molten Salt Thermal Energy Storage Market is projected to grow from USD 2,030 million in 2024 to USD 4,134.83 million by 2032, representing a compound annual growth rate (CAGR) of 9.30% during the forecast period. This growth is primarily attributed to the increasing demand for renewable energy storage solutions, particularly in concentrated solar power (CSP) plants, where molten salt technology is widely utilized. The ability of molten salt systems to store large amounts of thermal energy efficiently positions them as a key player in enhancing energy reliability and facilitating the transition to a sustainable energy grid.
Several factors are driving the growth of the molten salt thermal energy storage market. The global shift toward renewable energy sources, combined with government incentives and policies promoting energy storage solutions, is propelling investment in thermal energy storage technologies. Additionally, the declining costs of solar power systems and the rising need for grid stability and peak load management further contribute to the market's expansion. As energy systems evolve to incorporate more intermittent renewable sources, molten salt storage systems offer a practical solution for balancing supply and demand.
Regionally, North America currently holds a significant share of the market, driven by increased investments in renewable energy infrastructure and favorable government policies. The United States is a leader in deploying CSP technologies that utilize molten salt storage. Europe follows closely, with countries like Spain and Germany investing in advanced thermal energy storage systems. The Asia-Pacific region is anticipated to witness the fastest growth, fueled by rising energy demands, rapid industrialization, and increasing adoption of renewable energy technologies in countries like China and India. Overall, the molten salt thermal energy storage market is poised for substantial growth, driven by technological advancements and the global push toward sustainable energy solutions.
Market Drivers:
Growing Demand for Renewable Energy Storage:
The increasing demand for renewable energy storage solutions is a significant driver in the Molten Salt Thermal Energy Storage Market. As the global energy landscape shifts toward more sustainable sources, the need for effective storage systems that can store excess energy produced during peak sunlight hours becomes critical. For instance, the International Renewable Energy Agency (IRENA) reported that solar energy capacity is expected to reach over 2,800 GW by 2030, necessitating efficient storage solutions to balance supply and demand. Molten salt systems are particularly effective for this purpose, enabling the efficient storage of thermal energy for later use in electricity generation.
Technological Advancements in CSP:
Advancements in Concentrated Solar Power (CSP) technology also contribute to the market's growth. CSP plants that incorporate molten salt thermal energy storage systems can operate efficiently even after the sun sets, providing a reliable energy supply. Companies like Abengoa Solar have successfully implemented molten salt storage in their CSP projects, demonstrating the technology’s capability to deliver electricity during off-peak hours. This ability to dispatch power on demand enhances grid stability and supports the broader adoption of renewable energy sources.
Government Incentives and Policies:
Government initiatives aimed at promoting renewable energy are further driving the growth of the molten salt thermal energy storage market. Policies such as tax credits, grants, and subsidies encourage investment in renewable energy technologies, including molten salt systems. For instance, the U.S. Department of Energy (DOE) has allocated significant funding for research and development of advanced energy storage technologies, recognizing the importance of thermal storage in achieving energy independence and sustainability goals.
Need for Grid Stability and Reliability:
The increasing need for grid stability and reliability is also propelling the market forward. As more intermittent renewable sources, such as wind and solar, are integrated into the energy mix, maintaining a stable grid becomes challenging. Molten salt thermal energy storage provides a solution by allowing utilities to store excess energy and release it during peak demand periods. This capability helps prevent blackouts and ensures a steady energy supply, which is crucial for both residential and industrial consumers.
Market Trends:
Increasing Adoption of Renewable Energy:
The Molten Salt Thermal Energy Storage (TES) market is witnessing a significant surge in adoption due to the global shift towards renewable energy sources. Governments worldwide are implementing policies to reduce carbon emissions and promote sustainable energy solutions. For instance, the European Union has set ambitious targets to achieve 32% renewable energy consumption by 2030. This has led to increased investments in solar thermal power plants, which utilize molten salt TES systems to store excess energy generated during peak sunlight hours.
Technological Advancements:
Technological advancements are playing a crucial role in enhancing the efficiency and reliability of molten salt TES systems. Companies are investing heavily in research and development to improve the thermal stability and heat transfer properties of molten salts. For instance, a recent study by the U.S. Department of Energy highlighted the potential of nanoadditives to enhance the thermal conductivity of molten salts by up to 20%. These innovations are expected to reduce the overall cost of energy storage and make molten salt TES systems more competitive with traditional energy storage solutions.
Government Support and Incentives:
Government support and incentives are driving the growth of the molten salt TES market. Various countries are offering subsidies and tax incentives to encourage the adoption of energy storage technologies. For example, the Indian government has launched the National Solar Mission, which aims to achieve 100 GW of solar power capacity by 2022. This initiative includes financial incentives for the development of solar thermal power plants equipped with molten salt TES systems. Such policies are expected to create a favorable environment for market growth.
Increasing Industrial Applications:
The industrial sector is increasingly adopting molten salt TES systems for high-temperature process heating and energy storage. Industries such as steel manufacturing and chemical processing require reliable and efficient thermal energy storage solutions. For instance, a survey conducted by the International Energy Agency revealed that over 60% of steel manufacturing plants in China are considering the integration of molten salt TES systems to enhance energy efficiency. This trend is expected to drive the demand for molten salt TES systems in the coming years.
Market Challenges Analysis:
High Initial Costs:
One of the primary restraints in the Molten Salt Thermal Energy Storage (TES) market is the high initial costs associated with the installation and maintenance of these systems. Molten salt TES systems require substantial capital investment for the construction of storage tanks, heat exchangers, and other infrastructure components. This significant upfront expenditure can deter potential investors and project developers, particularly in regions with limited financial resources. Additionally, the cost of raw materials, such as specialized salts, further escalates the overall project cost.
Technical Challenges:
Technical challenges also pose significant hurdles to the widespread adoption of molten salt TES systems. The operation of these systems requires precise temperature control and efficient heat transfer mechanisms to ensure optimal performance. Any deviation from the required temperature range can lead to the degradation of the molten salt, reducing its thermal efficiency and lifespan. Moreover, the integration of molten salt TES systems with existing power generation infrastructure can be complex and technically demanding, necessitating specialized expertise and advanced engineering solutions.
Competition from Alternative Technologies:
The molten salt TES market faces stiff competition from alternative energy storage technologies, such as lithium-ion batteries and pumped hydro storage. These alternatives often offer lower initial costs and simpler installation processes, making them more attractive to potential investors. Additionally, advancements in battery technology are continuously improving the energy density and efficiency of lithium-ion batteries, further challenging the market position of molten salt TES systems. This competitive landscape necessitates continuous innovation and cost reduction efforts within the molten salt TES sector.
Regulatory and Environmental Concerns:
Regulatory and environmental concerns also impact the growth of the molten salt TES market. The disposal of used molten salts poses environmental challenges, as improper disposal can lead to soil and water contamination. Furthermore, stringent regulatory frameworks governing the construction and operation of energy storage facilities can create additional compliance costs and delays for project developers. Addressing these regulatory and environmental issues is crucial for the sustainable growth of the molten salt TES market.
Market Segmentation Analysis:
By Type
The Molten Salt Thermal Energy Storage (TES) market is segmented by type into power tower systems, parabolic trough systems, and dish/engine systems. Among these, the parabolic trough systems segment is expected to dominate the market due to its high efficiency and widespread adoption in solar thermal power plants. Power tower systems are also gaining traction, driven by their ability to achieve higher temperatures and improved thermal efficiency.
By Technology
By technology, the market is categorized into sensible heat storage, latent heat storage, and thermochemical storage. Sensible heat storage is the most commonly used technology, owing to its simplicity and cost-effectiveness. Latent heat storage, which involves phase change materials, offers higher energy density and is increasingly being adopted for advanced applications. Thermochemical storage, though still in the nascent stage, holds significant potential for future growth due to its high energy storage capacity and efficiency.
By End User
The end-user segment of the molten salt TES market includes commercial and industrial, public services, and residential sectors. The commercial and industrial segment is the largest end-user, driven by the high demand for reliable and efficient energy storage solutions in manufacturing and processing industries. Public services, including utilities and government projects, are also significant contributors to market growth, supported by various government initiatives and subsidies. The residential sector, while currently smaller, is expected to grow as awareness of renewable energy solutions increases among homeowners.
Segmentations:
By Technology Type- Sensitized and Unsensitized
- Sensitized (with additives)
- Unsensitized (pure salt)
- Single Tank vs. Two Tank Systems
- Single Tank Systems
- Two Tank Systems
- Concentrated Solar Power (CSP) Plants
- Industrial Heating
- Residential Heating
- Others (e.g., district heating)
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis:
North America
North America holds a significant share of the Molten Salt Thermal Energy Storage (TES) market, driven by the increasing adoption of renewable energy technologies and supportive government policies. The United States and Canada are the major contributors to the market in this region. The U.S. government has implemented various initiatives to promote the use of renewable energy, including tax incentives and subsidies for solar thermal power plants equipped with molten salt TES systems. As a result, North America accounts for approximately 25% of the global market share.
Europe
Europe is another prominent region in the molten salt TES market, with countries like Spain, Germany, and Italy leading the way. The European Union’s commitment to reducing carbon emissions and increasing the share of renewable energy in its energy mix has significantly boosted the demand for molten salt TES systems. Spain, in particular, has a large number of solar thermal power plants utilizing molten salt TES technology. Europe holds around 30% of the global market share, making it one of the largest regions for molten salt TES.
Asia-Pacific
The Asia-Pacific region is expected to witness the highest growth rate in the molten salt TES market, driven by rapid industrialization and increasing energy demand in countries like China and India. China has made substantial investments in renewable energy projects, including solar thermal power plants with molten salt TES systems, to reduce its reliance on fossil fuels and combat air pollution. India is also focusing on expanding its renewable energy capacity through initiatives like the National Solar Mission. The Asia-Pacific region currently holds about 35% of the global market share, making it the largest market for molten salt TES.
Latin America
Latin America is emerging as a potential market for molten salt TES, with countries like Brazil and Chile investing in renewable energy projects. The region’s abundant solar resources make it an ideal location for solar thermal power plants equipped with molten salt TES systems. Government policies and international investments are driving the growth of the market in this region. Latin America accounts for approximately 5% of the global market share.
Middle East & Africa
The Middle East & Africa region is also showing promising growth in the molten salt TES market. Countries like the United Arab Emirates and South Africa are investing in renewable energy projects to diversify their energy mix and reduce dependence on fossil fuels. The region’s high solar irradiance levels make it suitable for solar thermal power plants with molten salt TES systems. The Middle East & Africa region holds around 5% of the global market share.
Key Player Analysis:
- Yara International ASA
- Acciona S.A.
- Abengoa SA
- BrightSource Energy Inc.
- SENER Grupo de Ingenieria S.A.
- SolarReserve LLC
- Engie SA
- ACWA Power
- KVK Energy Ventures Ltd
- Torresol Energy Group
Competitive Analysis:
The Molten Salt Thermal Energy Storage (TES) market is characterized by intense competition among key players striving to enhance their market position through technological advancements and strategic partnerships. Companies like Yara International ASA, Acciona S.A., Abengoa SA, and BrightSource Energy Inc. are leading the market with innovative solutions and extensive project portfolios. These players are focusing on improving the thermal efficiency and cost-effectiveness of molten salt TES systems to gain a competitive edge. Additionally, collaborations with government bodies and research institutions are helping these companies to secure funding and accelerate the development of advanced TES technologies. The competitive landscape is further intensified by the entry of new players and the continuous evolution of alternative energy storage technologies, necessitating ongoing innovation and strategic initiatives to maintain market leadership.
Recent Developments:
- In July 2024, China announced plans to construct the first nuclear power plant using molten salt thorium in the Gobi Desert. This innovative project aims to leverage molten salt technology for safer and more efficient nuclear energy production.
- In October 2022, Abengoa won the 2022 Solar Project of the Year Award for the Noor 1 project. This project involves the construction of three solar fields, each with a capacity of 200 MW, using parabolic trough collectors in the Mohammed bin Rashid Al Maktoum Solar Park in Dubai.
- In 2023, significant advancements were made in the stabilization of molten salts with the use of metal chloride. These innovations aim to enhance the thermal stability and efficiency of molten salt TES systems, making them more competitive with other energy storage technologies.
Market Concentration & Characteristics:
The Molten Salt Thermal Energy Storage (TES) market is characterized by a moderate to high level of market concentration, with a few key players dominating the industry. Companies such as Yara International ASA, Acciona S.A., and Abengoa SA hold significant market shares due to their extensive project portfolios and technological advancements. The market is marked by continuous innovation, driven by the need to enhance thermal efficiency and reduce costs. Additionally, the market exhibits characteristics of high capital investment and technological complexity, which act as barriers to entry for new players. The competitive landscape is further shaped by strategic partnerships and collaborations with government bodies and research institutions, aimed at securing funding and accelerating the development of advanced TES technologies. This dynamic environment necessitates ongoing innovation and strategic initiatives to maintain market leadership.
Report Coverage:
The research report offers an in-depth analysis based on Technology Type, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of renewable energy sources will drive the demand for molten salt thermal energy storage systems.
- Technological advancements will enhance the efficiency and reliability of molten salt TES systems.
- Government incentives and policies will continue to support the growth of the molten salt TES market.
- Expansion of solar thermal power plants will boost the deployment of molten salt TES systems.
- Integration with smart grid technologies will improve the management and distribution of stored energy.
- Rising energy consumption in emerging economies will create new opportunities for market growth.
- Collaboration between key players and research institutions will accelerate innovation in the market.
- Environmental concerns and the need for sustainable energy solutions will drive the adoption of molten salt TES systems.
- Increasing industrial applications will expand the use of molten salt TES systems in various sectors.
- Continuous cost reduction efforts will make molten salt TES systems more competitive with alternative energy storage technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Molten Salt Thermal Energy Storage Market?
What factors are driving the growth of the Molten Salt Thermal Energy Storage Market?
What are some challenges faced by the Molten Salt Thermal Energy Storage Market?
Who are the major players in the Molten Salt Thermal Energy Storage Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Molten Salt Thermal Energy Storage Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Molten Salt Thermal Energy Storage Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,030 million → 2032: USD 4,134.83 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Molten Salt Thermal Energy Storage Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Molten Salt Thermal Energy Storage Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Molten Salt Thermal Energy Storage Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Molten Salt Thermal Energy Storage Market Drivers
- 3.3 Molten Salt Thermal Energy Storage Market Restraints & Challenges
- 3.4 Molten Salt Thermal Energy Storage Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Molten Salt Thermal Energy Storage Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Molten Salt Thermal Energy Storage Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Molten Salt Thermal Energy Storage category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Molten Salt Thermal Energy Storage Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Molten Salt Thermal Energy Storage Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Molten Salt Thermal Energy Storage market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Molten Salt Thermal Energy Storage Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Molten Salt Thermal Energy Storage Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Molten Salt Thermal Energy Storage Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Molten Salt Thermal Energy Storage (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Molten Salt Thermal Energy Storage Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Molten Salt Thermal Energy Storage Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Molten Salt Thermal Energy Storage Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Molten Salt Thermal Energy Storage Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Molten Salt Thermal Energy Storage Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Molten Salt Thermal Energy Storage Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Molten Salt Thermal Energy Storage Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Molten Salt Thermal Energy Storage Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Molten Salt Thermal Energy Storage Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
