
Mycosis Fungoides Market Overview:
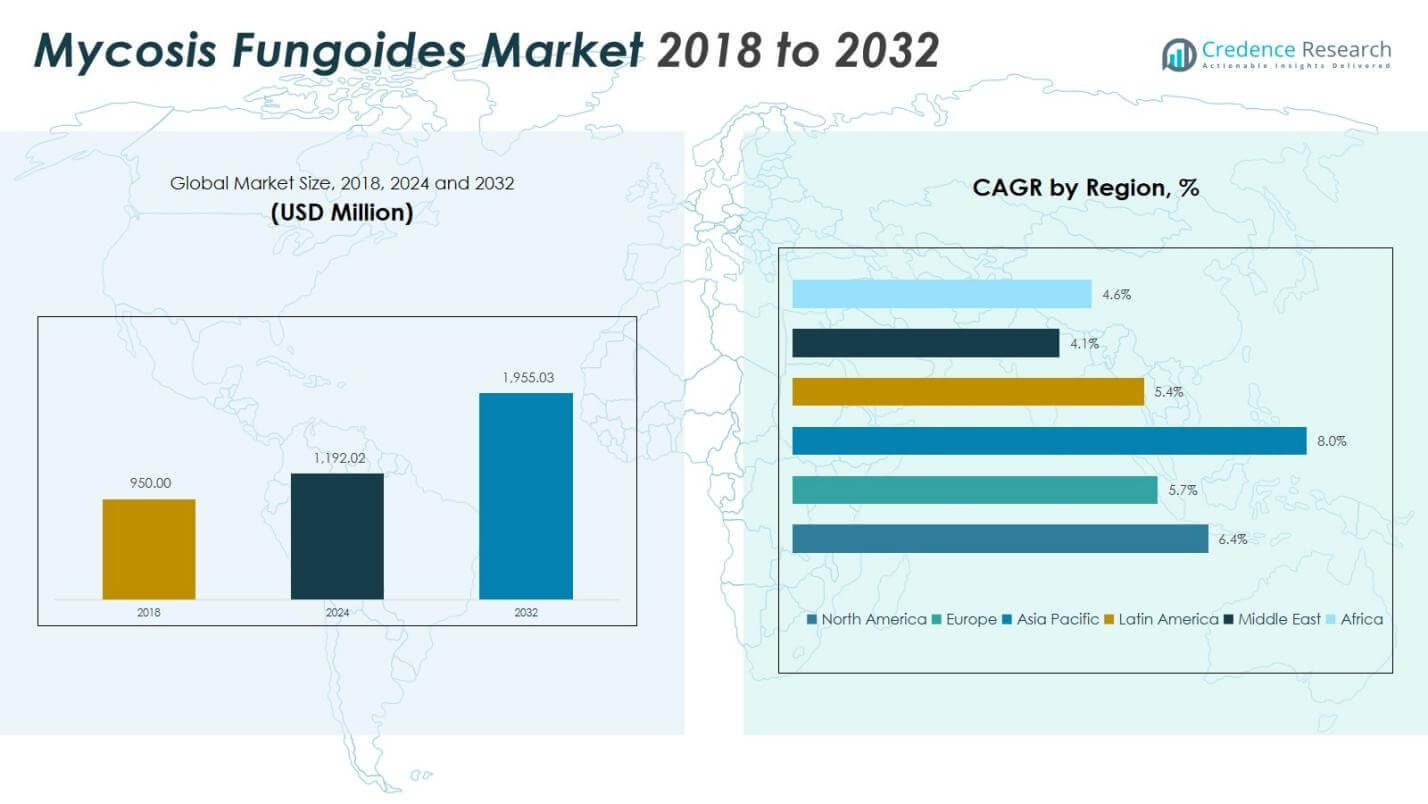
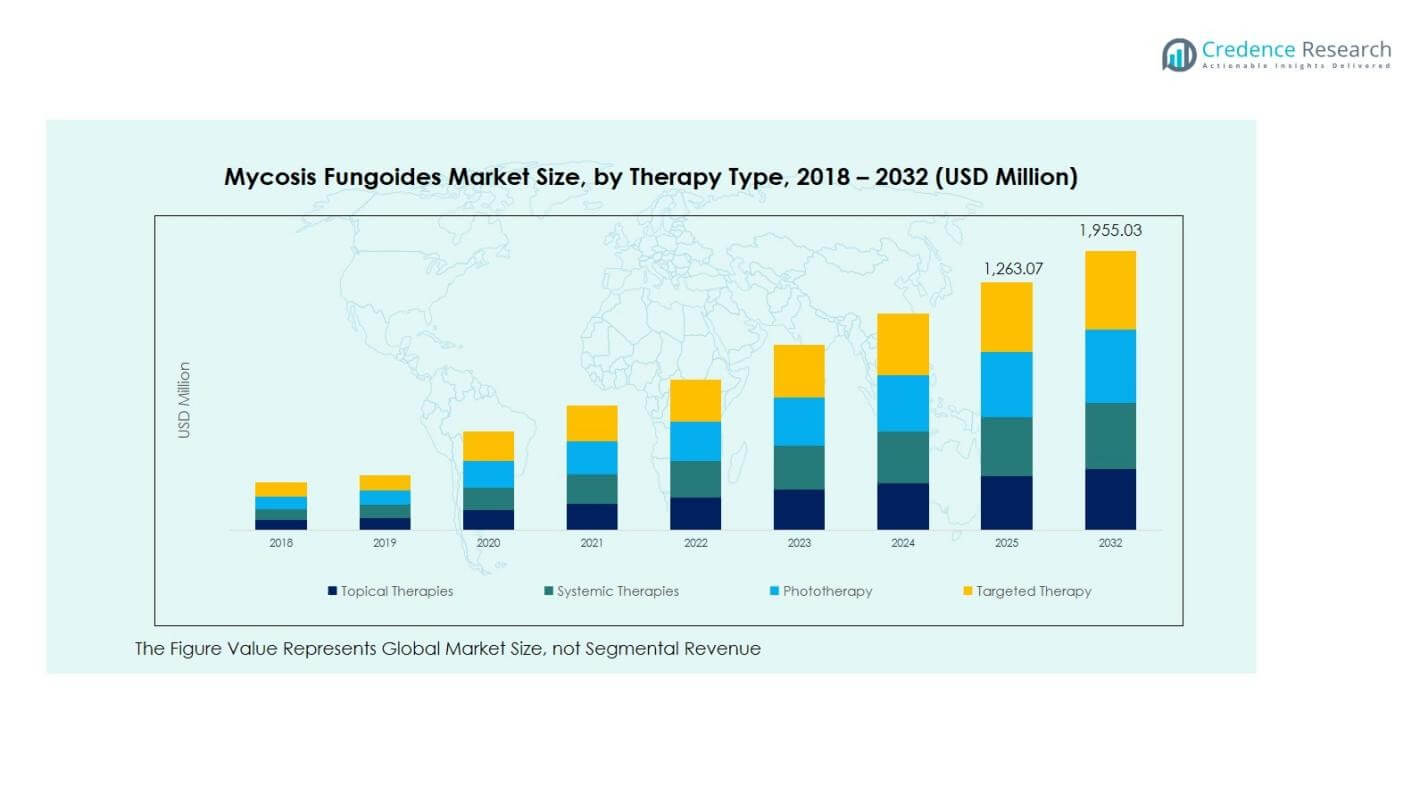
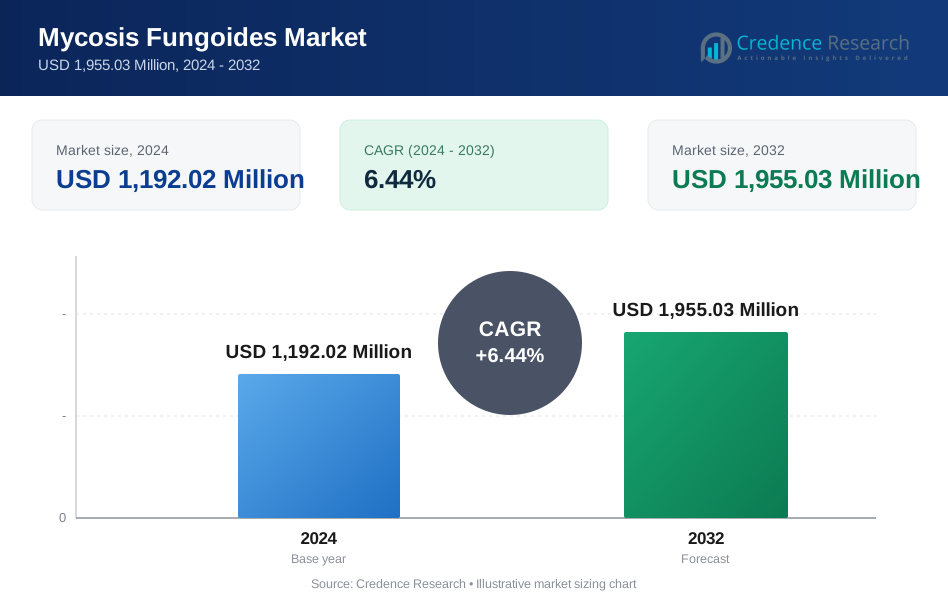
Mycosis Fungoides Market size was valued at USD 950.00 Million in 2018 and increased to USD 1,192.02 Million in 2024, and it is anticipated to reach USD 1,955.03 Million by 2032, at a CAGR of 6.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mycosis Fungoides Market Size 2024 | USD 1,192.02 million |
| Mycosis Fungoides Market, CAGR | 6.44% |
| Mycosis Fungoides Market Size 2032 | USD 1,955.03 million |
Mycosis Fungoides Market Insights
- Market growth is driven by rising prevalence of cutaneous T-cell lymphoma, increasing adoption of immunotherapy and biologics, and expanding access to specialized dermatology and oncology treatment centers.
- Market trends reflect a shift toward precision-based therapies, growing use of topical and targeted treatments, and increasing clinical research initiatives supporting innovation across early- and advanced-stage disease management.
- Leading players focus on portfolio expansion and therapy development, with strong presence from major pharmaceutical manufacturers and strengthening segment leadership of Topical Therapies at 28.60% share in 2024.
- Regional analysis shows North America holding 42.16% share in 2024, followed by Europe at 24.38% and Asia Pacific at 21.43%, while Latin America, Middle East, and Africa accounted for 6.14%, 2.16%, and 3.73% respectively.
Mycosis Fungoides Market Segmentation Analysis:
By Therapy Type
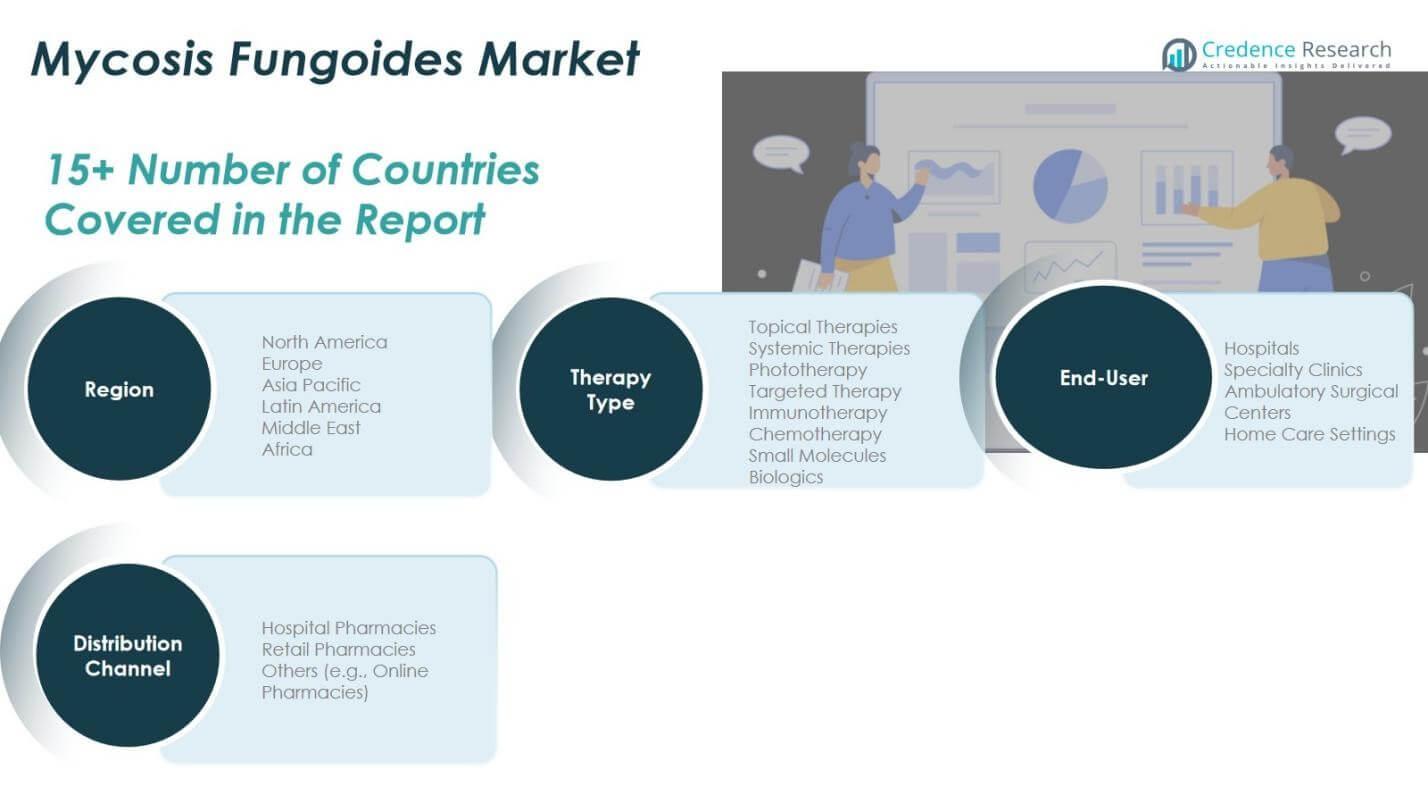
The Mycosis Fungoides Market by therapy type is led by Topical Therapies, which accounted for 28.60% share in 2024, driven by their first-line adoption in early-stage disease, favorable safety profile, and strong clinician preference for localized treatment before escalation to systemic options. Phototherapy and Immunotherapy are gaining traction due to increasing clinical evidence and improving access to specialized treatment centers, while Biologics and Small Molecules are expanding in advanced disease management. The growing shift toward targeted and immune-modulating modalities supports innovation across systemic and personalized therapy pathways.
- For instance, Valchlor (mechlorethamine) gel from Actelion showed a 59% overall response rate (14% complete, 45% partial) in stage IA/IB patients over 12 months in a randomized trial.
By End-User
The end-user landscape is dominated by Hospitals, which held 46.30% share in 2024, supported by the availability of multidisciplinary oncology care, advanced diagnostic infrastructure, and access to specialized dermatology and hematology services. Specialty Clinics continue to expand their presence due to increasing referrals for chronic disease management and long-term follow-up care. Ambulatory Surgical Centers and Home Care Settings are witnessing gradual growth as minimally invasive and home-based therapy delivery models strengthen, driven by improving patient awareness, cost-efficiency requirements, and a growing focus on outpatient-based cancer care pathways.
- For instance, ChartSpan partners with clinics like Regional West Physicians Clinic to manage chronic cancer care via monthly telephonic outreach, care plans, and 24/7 access for Medicare patients with multiple conditions.
By Distribution Channel
Across distribution channels, Hospital Pharmacies remained the leading segment with 49.80% share in 2024, supported by the hospital-based administration of systemic drugs, biologics, and specialty-grade dermatologic therapies used in moderate-to-advanced Mycosis Fungoides cases. Retail Pharmacies continue to serve early-stage and maintenance therapy prescriptions, particularly topical formulations. The Others category, including Online Pharmacies, is growing as digital prescription fulfillment, specialty drug logistics, and patient-support programs expand. Rising adoption of coordinated hospital-pharmacy networks and oncology treatment bundles further reinforces the dominance of institutional dispensing environments in this market.
Key Growth Drivers
Rising Prevalence of Cutaneous T-Cell Lymphoma and Early Diagnosis Expansion
The growing prevalence of cutaneous T-cell lymphoma, including Mycosis Fungoides, continues to drive market demand as improved clinical awareness leads to earlier diagnosis and treatment initiation. Increasing dermatology and oncology screening programs, along with wider access to biopsy and molecular testing, support earlier therapeutic intervention across disease stages. Healthcare providers are also adopting standardized care pathways, which strengthens treatment compliance and continuity. In parallel, patient awareness initiatives and referral networks between primary care and specialty centers enhance case identification, resulting in a steady rise in treatment volumes and sustained revenue growth across care settings.
- For instance, Kyowa Kirin launched POTELIGEO (mogamulizumab), a first-in-class monoclonal antibody approved for second-line treatment of adults with relapsed or refractory Mycosis Fungoides or Sézary syndrome after prior systemic therapy.
Advancements in Immunotherapy, Biologics, and Targeted Treatment Development
Rapid innovation in immunotherapy, biologics, and targeted agents significantly accelerates growth in the Mycosis Fungoides Market as manufacturers expand late-stage pipelines and regulatory approvals. These therapies offer improved safety profiles and enhanced efficacy for relapsed and advanced disease, supporting clinical adoption and premium pricing. Ongoing clinical trials, companion diagnostic integration, and personalized treatment approaches further strengthen value perception among clinicians. Pharmaceutical partnerships and R&D investments also stimulate product differentiation, while real-world evidence continues to validate long-term outcomes, reinforcing uptake across hospital and specialty care environments and expanding treatment opportunities globally.
- For instance, Soligenix's HYBRYTE (synthetic hypericin ointment), a topical photodynamic therapy, completed its Phase 3 FLASH study showing statistically significant lesion improvement after 6 weeks, with 16% of treated patients achieving significant reduction versus 4% on placebo.
Increasing Healthcare Spending and Access to Specialized Oncology Care
Rising healthcare expenditure and expansion of specialized oncology and dermatology infrastructure play a critical role in market growth by improving access to advanced therapeutic modalities. Growth in hospital networks, cancer care centers, and reimbursement support enhances treatment affordability and patient reach. Governments and private providers continue to strengthen rare-disease care programs, accelerating adoption of systemic therapies, phototherapy, and biologics. Parallel developments in pharmacy distribution, patient assistance initiatives, and multidisciplinary care models further support treatment continuity. These system-level improvements collectively enhance therapy penetration, particularly in developing healthcare markets experiencing modernization and capacity expansion.
Key Trends & Opportunities
Shift Toward Personalized and Precision-Based Treatment Pathways
A major trend shaping the Mycosis Fungoides Market is the accelerating shift toward personalized and precision-based treatment approaches driven by advances in molecular profiling and biomarker-guided therapy selection. Clinicians increasingly tailor regimens based on disease stage, genetic expression, and patient-specific response patterns, supporting improved clinical outcomes and reduced toxicity. Pharmaceutical companies are leveraging this shift by developing targeted molecules and next-generation immunotherapies designed for selective disease pathways. This evolution also creates opportunities for companion diagnostics, integrated care algorithms, and real-world outcome monitoring, strengthening long-term treatment optimization and supporting innovation-led market expansion.
- For instance, Kyowa Kirin developed POTELIGEO (mogamulizumab-kpkc), a first-in-class anti-CCR4 monoclonal antibody that targets CCR4-expressing malignant T-cells prevalent in mycosis fungoides and Sézary syndrome.
Growing Adoption of Outpatient, Home-Based, and Digital Care Models
Expanding adoption of outpatient-based therapy delivery, home-care models, and digital patient-management platforms is emerging as a key opportunity within the market. Increasing use of topical therapies, maintenance regimens, and tele-dermatology follow-ups supports decentralized care while improving convenience and adherence. Pharmacy-led patient support programs, remote symptom tracking, and virtual consultations enhance continuity of care for chronic disease management. These models also reduce treatment burden and cost, encouraging broader therapy access. As healthcare systems prioritize patient-centric delivery frameworks, stakeholders benefit from stronger engagement, better monitoring outcomes, and sustainable long-term treatment adoption pathways.
- For instance, Current Health enables delivery of advanced therapies like CAR-T and bispecifics in outpatient and home settings through remote monitoring kits, including wearables and vital sign devices.
Key Challenges
High Treatment Costs and Reimbursement Constraints in Advanced Therapies
One of the major challenges in the Mycosis Fungoides Market is the high cost associated with advanced therapies, including biologics, targeted agents, and immunotherapy, which limits accessibility in cost-sensitive regions. Reimbursement variations across markets create financial barriers for both providers and patients, affecting therapy continuity and adoption rates. Payer scrutiny over long-term cost-effectiveness further restricts coverage decisions, particularly for rare-disease oncology indications. Additionally, limited availability of subsidized treatment programs and disparities in insurance coverage contribute to unequal treatment access, posing a structural challenge to market scalability and uniform therapeutic penetration.
Limited Clinical Awareness and Complexity in Disease Diagnosis and Management
Another critical challenge arises from limited clinical awareness and the complex diagnostic nature of Mycosis Fungoides, particularly in early stages where symptoms resemble common dermatologic conditions. Delayed or inaccurate diagnosis often results in treatment postponement and disease progression, reducing therapeutic effectiveness. The requirement for specialist expertise, multiple biopsies, and long-term monitoring increases clinical complexity and resource burden. In regions with limited dermatopathology capacity, access to skilled professionals remains constrained. These factors collectively hinder timely intervention, reduce patient outcomes, and restrain broader market growth despite ongoing advances in treatment innovation.
Regional Analysis
North America
North America remains the leading region in the Mycosis Fungoides Market, with revenues rising from USD 404.70 Million in 2018 to USD 502.55 Million in 2024, and projected to reach USD 823.27 Million by 2032 at a CAGR of 6.4%. The region accounted for the largest 2024 market share of 42.16%, supported by strong oncology infrastructure, early diagnosis rates, reimbursement coverage, and the presence of leading biopharmaceutical companies. High treatment adoption for biologics, immunotherapy, and phototherapy, along with increasing clinical research participation, continues to reinforce North America’s dominant market position.
Europe
Europe represents the second-largest regional market, growing from USD 241.30 Million in 2018 to USD 290.58 Million in 2024, and expected to reach USD 449.17 Million by 2032 at a CAGR of 5.7%. The region accounted for 24.38% market share in 2024, driven by well-established healthcare systems, strong dermatology and oncology networks, and rising adoption of targeted and systemic therapies. Ongoing clinical guideline updates, government-supported rare-disease programs, and consistent investments in cancer care infrastructure enhance treatment accessibility, supporting steady demand growth across major European countries and strengthening the region’s long-term market contribution.
Asia Pacific
The Asia Pacific market is expanding rapidly, increasing from USD 193.33 Million in 2018 to USD 255.50 Million in 2024, and projected to reach USD 470.77 Million by 2032 at a CAGR of 8.0%. The region accounted for 21.43% share in 2024, supported by improving cancer awareness, expanding healthcare infrastructure, and growing access to specialty dermatology and hematology services. Rising investments in oncology centers, increasing patient diagnosis rates, and gradual inclusion of biologics and immunotherapies in treatment pathways are strengthening market penetration, particularly in China, Japan, India, and South Korea, making Asia Pacific a high-growth regional opportunity.
Latin America
Latin America recorded steady progress in the Mycosis Fungoides Market, increasing from USD 58.90 Million in 2018 to USD 73.18 Million in 2024, and expected to reach USD 111.18 Million by 2032 at a CAGR of 5.4%. The region accounted for 6.14% market share in 2024, supported by the gradual expansion of oncology care services, improving treatment availability in urban hospitals, and strengthening government health programs. Adoption of systemic and phototherapy treatments is rising, although disparities in access and reimbursement persist across countries, resulting in uneven growth momentum between developed and emerging healthcare markets in the region.
Middle East
The Middle East market increased from USD 22.80 Million in 2018 to USD 25.74 Million in 2024, and is projected to reach USD 35.40 Million by 2032 at a CAGR of 4.1%. The region represented 2.16% market share in 2024, driven by expanding investments in specialty cancer care, improving diagnostic capabilities, and increasing adoption of advanced dermatologic and immunotherapy treatments in GCC countries. Growing partnerships with global pharmaceutical companies and modernization of tertiary care hospitals are supporting market development, although treatment affordability and access variations continue to influence overall adoption patterns across the broader Middle Eastern market.
Africa
Africa remains a developing market, with revenues rising from USD 28.98 Million in 2018 to USD 44.47 Million in 2024, and projected to reach USD 65.24 Million by 2032 at a CAGR of 4.6%. The region accounted for 3.73% market share in 2024, supported by gradual improvements in healthcare accessibility, increasing patient awareness, and strengthening oncology service capacity in select urban centers. However, limited specialist availability, delayed diagnosis, and constrained reimbursement frameworks continue to challenge therapy penetration. Ongoing international health initiatives and capacity-building programs are expected to support progressive, but controlled, long-term market expansion across the region.
Mycosis Fungoides Market Segmentations:
By Therapy Type
- Topical Therapies
- Systemic Therapies
- Phototherapy
- Targeted Therapy
- Immunotherapy
- Chemotherapy
- Small Molecules
- Biologics
By End-User
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
- Home Care Settings
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Others (including Online Pharmacies)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Competitive landscape in the Mycosis Fungoides Market is shaped by innovation-driven product development, expanding oncology pipelines, and increasing focus on advanced therapeutic modalities such as immunotherapy, biologics, and targeted agents. Market activity is influenced by continuous clinical trial progress, regulatory approvals, and portfolio-expansion strategies aimed at strengthening treatment outcomes across early and advanced disease stages. Leading participants, including Kyowa Kirin Co., Ltd., Takeda Pharmaceutical Company Ltd., Seagen Inc., Merck & Co., Inc., Novartis AG, Incyte Corporation, Amgen Inc., AbbVie Inc., Sanofi, and GlaxoSmithKline, actively invest in strategic collaborations with academic centers and specialty hospitals to accelerate clinical adoption. Companies also emphasize market-access programs, specialty-pharmacy distribution, and real-world evidence generation to enhance therapy penetration and patient support. Growing emphasis on precision medicine, combination regimens, and differentiated treatment pathways continues to intensify competition while shaping long-term market positioning and future growth opportunities.
Key Player Analysis
- Kyowa Kirin Co., Ltd.
- Takeda Pharmaceutical Company Ltd.
- Seagen Inc. (formerly Seattle Genetics)
- Soligenix, Inc.
- Merck & Co., Inc.
- Helsinn Healthcare SA
- Eisai Co., Ltd.
- Azurity Pharmaceuticals, Inc.
- GlaxoSmithKline (GSK)
- Sanofi
- Eli Lilly and Company
- Novartis AG
- AbbVie Inc.
- Amgen Inc.
- Incyte Corporation
- Teva Pharmaceutical Industries Ltd.
- Horizon Therapeutics plc
Recent Developments
- In December 2025, Citius Oncology announced the U.S. commercial launch of LYMPHIR, a novel IL-2 receptor-directed fusion protein immunotherapy approved by the FDA for relapsed or refractory cutaneous T-cell lymphoma, including mycosis fungoides.
- In November 2025, Innate Pharma received FDA clearance to proceed with the confirmatory Phase 3 TELLOMAK 3 trial of lacutamab in patients with Mycosis Fungoides and Sézary syndrome, advancing its late-stage development program.
- In April 2025, Kyowa Kirin launched a new CTCL staging tool to support healthcare providers in accurately staging patients with Mycosis Fungoides and Sézary Syndrome, enhancing diagnostic precision.
Report Coverage
The research report offers an in-depth analysis based on Therapy Type, End User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand as early diagnosis rates improve and more patients gain access to specialized dermatology and oncology care.
- Adoption of immunotherapy, biologics, and targeted treatments will increase as clinical evidence and treatment outcomes strengthen.
- Precision medicine and biomarker-guided therapy selection will play a larger role in treatment planning and disease management.
- Pharmaceutical companies will intensify R&D investment in novel molecules, combination regimens, and next-generation targeted agents.
- Hospitals and specialty clinics will remain the primary treatment centers, supported by multidisciplinary care and coordinated referral networks.
- Digital health tools, tele-dermatology, and remote patient monitoring will support long-term disease follow-up and adherence.
- Reimbursement expansion and supportive healthcare policies will improve treatment accessibility in emerging and developing markets.
- Partnerships between industry, research institutions, and clinical networks will accelerate innovation and real-world data generation.
- Increasing patient awareness and education programs will encourage timely consultation and earlier treatment initiation.
- Market competition will intensify as new entrants, pipeline approvals, and differentiated therapeutic approaches expand the treatment landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Mycosis Fungoides Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mycosis Fungoides Market projected to grow between 2024 and 2032?
Which Mycosis Fungoides Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mycosis Fungoides Market?
Who are the leading companies in the Mycosis Fungoides Market?
Which region commanded the largest share of the Mycosis Fungoides Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mycosis Fungoides Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mycosis Fungoides Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,192.02 Million → 2032: USD 1,955.03 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mycosis Fungoides Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mycosis Fungoides Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mycosis Fungoides Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mycosis Fungoides Market Drivers
- 3.3 Mycosis Fungoides Market Restraints & Challenges
- 3.4 Mycosis Fungoides Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mycosis Fungoides Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mycosis Fungoides Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mycosis Fungoides category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mycosis Fungoides Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mycosis Fungoides Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mycosis Fungoides market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mycosis Fungoides Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mycosis Fungoides Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mycosis Fungoides Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mycosis Fungoides (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mycosis Fungoides Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mycosis Fungoides Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mycosis Fungoides Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mycosis Fungoides Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mycosis Fungoides Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mycosis Fungoides Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mycosis Fungoides Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mycosis Fungoides Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mycosis Fungoides Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
