
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Nasal Polyposis Treatment Market Size 2024 | USD 4,612 million |
| Nasal Polyposis Treatment Market, CAGR | 6.7% |
| Nasal Polyposis Treatment Market Size 2032 | USD 7,748.26 million |
Market Overview:
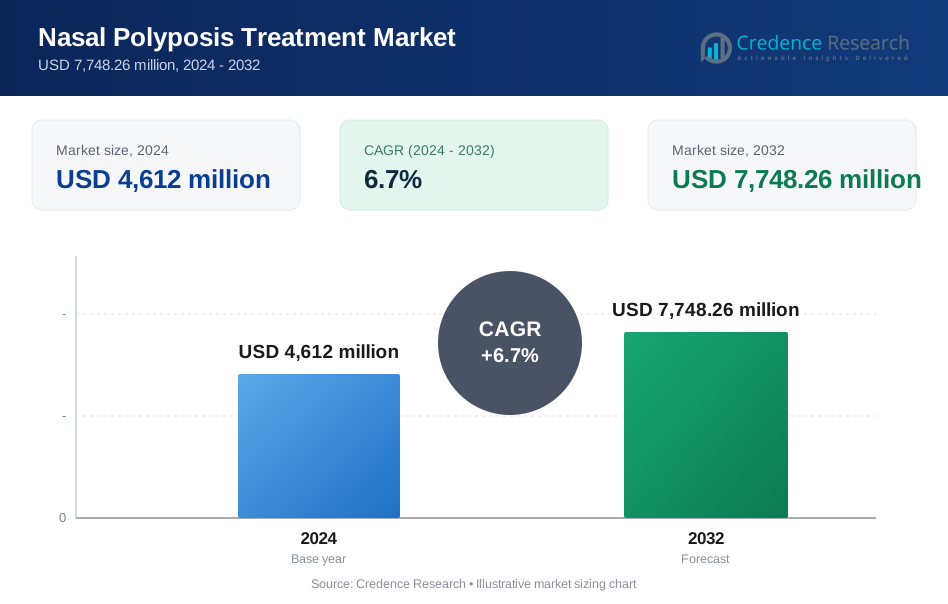
The Nasal Polyposis Treatment Market is projected to grow from USD 4,612 million in 2024 to USD 7,748.26 million by 2032, with a compound annual growth rate (CAGR) of 6.7%.
The Nasal Polyposis Treatment Market is primarily driven by the rising prevalence of chronic rhinosinusitis with nasal polyps (CRSwNP) and increasing awareness about advanced treatment options. Growing demand for biologics, such as interleukin inhibitors, which offer targeted and long-term solutions for managing inflammation, is a key trend. The approval of new biologics like dupilumab and depemokimab, which provide extended dosing intervals and improved patient outcomes, is expected to fuel market expansion. Additionally, increased healthcare spending, advancements in diagnostic tools, and a growing focus on personalized medicine contribute to market growth. The shift toward non-invasive treatment methods and a rising geriatric population, more prone to chronic respiratory conditions, further support demand. However, the high cost of biologics may limit access in certain regions.
The Nasal Polyposis Treatment Market is geographically segmented into North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America holds the largest market share, driven by the adoption of biologic therapies and strong healthcare infrastructure. Europe follows with significant demand, particularly in Germany, the U.K., and France. The Asia-Pacific region is expected to experience the fastest growth, driven by increasing healthcare investments and rising awareness in countries like China, Japan, and India. Latin America and the Middle East & Africa hold smaller shares but are growing due to improving healthcare access and rising prevalence of respiratory conditions. Key players in these regions include Pfizer Inc., Merck KGaA, Sanofi, Biocare Medical, LLC, Lilly, Teva Pharmaceutical Industries, Mitsubishi Chemical Group Corporation, Bristol-Myers Squibb Company, GSK plc., and Bayer AG.
Market Insights:
- The Nasal Polyposis Treatment Market is projected to grow from USD 4,612 million in 2024 to USD 7,748.26 million by 2032, with a CAGR of 6.7%.
- Rising prevalence of chronic rhinosinusitis with nasal polyps (CRSwNP) and increasing awareness about advanced treatments are key market drivers.
- The growing demand for biologics, such as interleukin inhibitors, is transforming treatment options for CRSwNP by offering targeted, long-term solutions.
- Regulatory approvals for biologics like dupilumab and depemokimab are expected to accelerate market growth and expand treatment options for a broader patient population.
- Non-invasive treatment methods, including biologic therapies, are driving a shift away from traditional surgical options, enhancing patient preferences and market demand.
- High costs of biologic therapies remain a challenge, limiting access to treatments in certain regions, especially in low- and middle-income countries.
- Regional growth is driven by North America's dominance (40% market share in 2024), with Europe (30%), Asia-Pacific (18%), and emerging markets like Latin America and the Middle East & Africa contributing to expanding opportunities.
Market Drivers:
Rising Prevalence of Chronic Rhinosinusitis with Nasal Polyps (CRSwNP):
The increasing prevalence of chronic rhinosinusitis with nasal polyps (CRSwNP) is a major driver of the nasal polyposis treatment market. As CRSwNP is a persistent condition that significantly impacts quality of life, the growing number of patients globally, particularly among the aging population, has resulted in heightened demand for effective treatment options. This trend is further amplified by the rising awareness among healthcare professionals and patients regarding the need for proper diagnosis and treatment of nasal polyps to manage symptoms and prevent complications.
Advancements in Biologics and Targeted Therapies:
The market is experiencing significant growth due to advancements in biologic therapies targeting type 2 inflammation, which plays a critical role in CRSwNP. For instance, Dupilumab, an interleukin-4 receptor alpha antagonist, received FDA approval in 2019 for treating CRSwNP, demonstrating its ability to inhibit interleukins 4 and 13, which are key drivers of inflammation. These biologics offer a more personalized and effective treatment compared to traditional therapies, driving their adoption in clinical practice.
Regulatory Approvals and Expanding Indications:
Regulatory approvals of novel biologic therapies for nasal polyposis have further accelerated market growth. Additionally, ongoing clinical trials exploring the use of these biologics for broader indications and patient populations are expected to drive further market expansion, as more patients become eligible for these advanced treatments. Increased awareness among healthcare professionals and patients, alongside improved diagnostic capabilities, is also likely to contribute to the growing adoption of these therapies, ensuring long-term growth in the sector.
Growing Focus on Non-Invasive Treatments:
A shift towards non-invasive and long-term management solutions is driving the demand for biologic treatments in the nasal polyposis market. Patients increasingly prefer therapies that minimize surgical intervention and offer sustained relief from symptoms. For instance, Xolair (omalizumab), developed by Roche, has demonstrated the ability to reduce the size of nasal polyps and relieve nasal congestion in clinical studies within four weeks, making it a promising option for patients seeking more convenient, effective treatments. Ongoing research continues to support its efficacy in improving quality of life for affected individuals.
Market Trends:
Increasing Adoption of Biologics:
One of the most notable trends in the Nasal Polyposis Treatment Market is the increasing adoption of biologic therapies. These advanced treatments, which target specific inflammatory pathways involved in chronic rhinosinusitis with nasal polyps (CRSwNP), are gaining traction due to their efficacy and long-lasting effects. This shift towards biologics is driven by their ability to provide more targeted and personalized treatment options.
Expansion of Indications for Biologics:
The ongoing expansion of indications for biologic treatments is a key trend in the market. Initially approved for use in adults with severe cases of CRSwNP, biologics such as dupilumab are now being extended to broader patient populations, including adolescents. As more studies demonstrate the safety and efficacy of biologics across diverse patient groups, including those with varying severities of nasal polyposis, the market is expected to witness further growth in this segment. Increased access and availability of these treatments in global markets will also contribute to the expanding adoption.
Focus on Patient-Centered Care:
Another trend shaping the market is the growing focus on patient-centered care. Healthcare providers and pharmaceutical companies are placing greater emphasis on improving the overall quality of life for patients with nasal polyps. For instance, Regeneron's DUPIXENT (dupilumab) demonstrated a 35% reduction in nasal polyp scores versus 18% for Roche’s XOLAIR and 15% for GSK’s NUCALA in clinical trials. Biologics, with their long-term efficacy and reduced side effects, align well with this patient-centered approach.
Technological Advancements in Diagnostics:
Technological advancements in diagnostic tools are also influencing the nasal polyposis treatment market. Enhanced imaging techniques and diagnostic algorithms are helping clinicians identify CRSwNP more accurately, leading to earlier diagnosis and personalized treatment plans. For instance, GSK's NUCALA (mepolizumab), a monoclonal antibody, received approval in Japan for treating adults with CRSwNP whose condition is inadequately controlled with standard therapy.
Market Challenges Analysis:
High Cost of Biologic Therapies:
One of the significant challenges facing the Nasal Polyposis Treatment Market is the high cost of biologic therapies. While biologics like dupilumab and depemokimab offer superior efficacy and convenience over traditional treatments, their pricing remains a barrier for widespread adoption, particularly in low- and middle-income countries. The costs associated with research, development, and production of biologics contribute to their high price points, which can limit access for patients who lack sufficient insurance coverage or live in regions with underfunded healthcare systems. Even in developed markets, patients may face high out-of-pocket expenses, which can deter long-term adherence to treatment regimens. As biologics become more prevalent in the treatment landscape, addressing the affordability of these therapies will be crucial to ensuring broader patient access and driving market growth. Companies and governments may need to explore pricing strategies, insurance reforms, or subsidy programs to reduce financial barriers and improve access to biologic treatments.
Regulatory and Reimbursement Barriers:
Navigating complex regulatory frameworks and reimbursement policies presents another challenge for the nasal polyposis treatment market. Securing regulatory approval for biologics involves rigorous clinical trials to demonstrate efficacy, safety, and long-term benefits, which can delay product launches and increase costs for manufacturers. Additionally, each country has its own regulatory requirements, making global commercialization of biologics a lengthy and costly process. On the reimbursement side, healthcare systems and insurers may be hesitant to fully cover the costs of expensive biologics, especially when traditional treatments like corticosteroids or surgery are more affordable in the short term. This reluctance to reimburse high-cost therapies can create obstacles for patients seeking access to the most effective treatments. For instance, To gain FDA approval for Dupixent in 2019 as a treatment for chronic rhinosinusitis with nasal polyps, Regeneron and Sanofi conducted two Phase 3 trials, SINUS-24 and SINUS-52, which demonstrated statistically significant reductions in nasal polyp size and nasal congestion versus a placebo. As a result, companies must work closely with regulatory bodies and payers to demonstrate the value of biologics in improving patient outcomes and reducing long-term healthcare costs, in order to overcome these market challenges. Enhanced communication, data-driven approaches, and clear evidence of the cost-benefit ratio of biologics could help facilitate smoother regulatory approvals and wider payer acceptance.
Market Opportunities:
The Nasal Polyposis Treatment Market presents significant growth opportunities due to the increasing focus on biologic therapies and personalized medicine. As more biologics, such as dupilumab and depemokimab, demonstrate strong efficacy in reducing nasal polyps and improving patient outcomes, there is potential for expanded use in broader patient populations. Currently, biologics are primarily prescribed for severe cases of chronic rhinosinusitis with nasal polyps (CRSwNP), but ongoing clinical trials may lead to approvals for mild-to-moderate cases, further expanding the market. Additionally, the rising incidence of CRSwNP, particularly in aging populations and regions with higher rates of respiratory conditions, will drive demand for advanced treatments.
The market also offers opportunities for growth through geographic expansion, especially in emerging markets. As healthcare infrastructure improves in these regions and awareness about advanced treatment options grows, demand for biologic therapies is expected to rise. Companies that invest in market education, local partnerships, and accessible pricing models can capture untapped potential in regions where nasal polyposis is underdiagnosed or undertreated. Moreover, advancements in diagnostics, such as improved imaging technologies and biomarkers, can lead to earlier and more accurate diagnosis, providing additional opportunities for companies to introduce targeted therapies earlier in the disease progression. The increasing shift toward non-invasive treatment methods will also continue to create new avenues for innovation and growth in the nasal polyposis treatment market.
Market Segmentation Analysis:
By Drugs
The nasal polyposis treatment market is segmented by drugs into corticosteroids, antibiotics, and biologics. Biologics are emerging as the fastest-growing segment due to their targeted mechanism of action and long-term efficacy in treating chronic rhinosinusitis with nasal polyps (CRSwNP). Increasing adoption of biologic therapies, such as dupilumab, is significantly driving market growth.
By Route of Administration
The route of administration for nasal polyposis treatments includes oral, topical, and injectable forms. Injectable biologics, due to their targeted delivery and extended dosing intervals, are gaining popularity. However, topical corticosteroids remain widely used for initial and less severe cases, offering convenient, non-invasive options for patients.
By End User
End-user segments include hospitals, specialty clinics, and home care settings. Specialty clinics hold a significant market share, driven by the increasing preference for expert-led management of CRSwNP cases. Home care settings are also expected to grow, especially for biologic therapies, which allow for long-term treatment with minimal hospital visits.
Segments:
Based on Drugs
- Nasal corticosteroids
- Oral and injectable corticosteroids
- Dupixent
- Others
Based on Route of Administration
- Oral
- Parenteral
- Nasal
- Others
Based on End User
- Hospitals
- Homecare
- Specialty Clinics
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the nasal polyposis treatment market, accounting for 40% of the global market in 2024. This dominance is driven by several factors, including the high prevalence of chronic rhinosinusitis with nasal polyps (CRSwNP) and the widespread adoption of advanced biologic therapies. The U.S. is a major contributor, with significant healthcare infrastructure, strong investment in research and development, and early access to innovative treatments such as dupilumab and depemokimab. Additionally, the presence of major pharmaceutical companies and favorable reimbursement policies further support market growth in the region. Canada is also witnessing growth, with increasing awareness of biologic treatments and improved healthcare access.
Europe:
Europe is the second-largest market, representing 30% of the global nasal polyposis treatment market share in 2024. Countries such as Germany, the U.K., and France are at the forefront of adopting biologics for CRSwNP, driven by advanced healthcare systems and strong regulatory support. The market in Europe is benefiting from rising patient awareness and growing demand for personalized medicine. Additionally, favorable regulatory frameworks for biologics and expanding reimbursement coverage for these therapies are contributing to market growth. However, some countries in Eastern Europe may experience slower adoption due to limited healthcare funding and lower awareness.
Asia-Pacific:
The Asia-Pacific region accounts for 18% of the nasal polyposis treatment market in 2024 and is expected to witness the fastest growth over the coming years. Factors such as increasing healthcare expenditure, rising awareness about CRSwNP, and improving access to advanced therapies are driving market expansion in countries like China, Japan, and India. The growing prevalence of respiratory diseases, coupled with the expansion of healthcare infrastructure in emerging markets, presents significant opportunities for companies. However, high treatment costs and limited access to biologics in some areas may pose challenges to widespread adoption.
Latin America
Latin America holds around 7% of the market share in 2024. The region is gradually adopting advanced therapies for nasal polyposis, particularly in countries like Brazil and Mexico, where healthcare infrastructure is improving. However, market growth may be constrained by limited access to biologics and a lack of awareness about CRSwNP treatment options in less developed regions.
Middle East & Africa
The Middle East & Africa region represents about 5% of the market share in 2024, with market growth driven primarily by increasing healthcare investments in the Gulf Cooperation Council (GCC) countries. While access to biologics remains limited in many parts of Africa, the growing focus on healthcare infrastructure in countries like the UAE and Saudi Arabia is creating opportunities for market expansion. Awareness and affordability remain key challenges in this region.
Key Player Analysis
- Pfizer Inc. (U.S.)
- Merck KGaA (Germany)
- Sanofi (France)
- Biocare Medical, LLC (U.S.)
- Lilly (U.S.)
- Teva Pharmaceutical Industries (Israel)
- Mitsubishi Chemical Group Corporation (U.S.)
- Bristol-Myers Squibb Company (U.S.)
- GSK plc. (U.K.)
- Bayer AG (Germany)
Competitive Analysis:
The Nasal Polyposis Treatment Market is highly competitive, with leading players such as Pfizer Inc., Merck KGaA, Sanofi, Biocare Medical, LLC, Lilly, Teva Pharmaceutical Industries, Mitsubishi Chemical Group Corporation, Bristol-Myers Squibb Company, GSK plc., and Bayer AG vying for market share. These companies are focusing on the development and commercialization of biologic therapies targeting chronic rhinosinusitis with nasal polyps (CRSwNP), with an emphasis on improving patient outcomes through personalized, long-term treatment options. Additionally, market leaders are investing in expanding their product portfolios, enhancing diagnostic tools, and increasing accessibility to biologic treatments. Companies are also working on improving patient adherence to treatment regimens, addressing cost barriers, and navigating complex reimbursement policies to maintain their market positions. Competitive strategies are centered around expanding into emerging markets and offering differentiated treatment options.
Recent Developments
- In October 2024, GSK plc, a biopharmaceutical company, announced positive results from the Phase III ANCHOR trials for depemokimab, a treatment aimed at chronic rhinosinusitis with nasal polyps (CRSwNP). Both the ANCHOR-1 and ANCHOR-2 trials successfully achieved their primary goals, demonstrating significant reductions in nasal polyp size and nasal obstruction compared to placebo over 52 weeks. Depemokimab is an ultra-long-acting biologic, administered every six months, designed to specifically target interleukin-5 (IL-5), a key cytokine in type 2 inflammation.
- In September 2024, Regeneron Pharmaceuticals, Inc., a global pharmaceutical company, announced that the U.S. Food and Drug Administration (FDA) had approved Dupixent (dupilumab) as an add-on maintenance treatment for adolescents aged 12 to 17 with inadequately controlled chronic rhinosinusitis with nasal polyps (CRSwNP).
- In 2023, GSK acquired Aiolos Therapeutics, gaining access to AIO-001, a long-acting anti-TSLP monoclonal antibody. AIO-001 is prepared to enter Phase 2 clinical trials for adult asthma patients, with potential applications for CRSwNP. This acquisition enhances GSK's portfolio in immuno-inflammatory diseases.
- In January 2024, Upstream Bio commenced a Phase II clinical trial for Verekitug (UPB-101), an investigational therapy for CRSwNP. The trial involves dosing the first patients and aims to evaluate the safety and efficacy of Verekitug in treating this condition.
Market Concentration & Characteristics:
The Nasal Polyposis Treatment Market exhibits moderate to high concentration, with key players such as Pfizer Inc., Merck KGaA, Sanofi, and GSK plc. leading the market. These companies are focused on developing and commercializing innovative biologic therapies, particularly interleukin inhibitors, to address chronic rhinosinusitis with nasal polyps (CRSwNP). The market characteristics include a significant emphasis on research and development, as well as regulatory approvals for novel biologic treatments. Additionally, there is a growing trend towards personalized medicine, with biologics offering targeted solutions and extended dosing intervals. The market is also marked by high competition among established pharmaceutical companies, with ongoing clinical trials and expansion into new patient populations. Despite the strong presence of large companies, there is still potential for smaller players to enter the market by focusing on niche treatment areas or emerging regions, contributing to a dynamic competitive landscape.
Report Coverage:
The research report offers an in-depth analysis based on Drugs, Route of Administration, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Nasal Polyposis Treatment Market is expected to continue expanding as the prevalence of chronic rhinosinusitis with nasal polyps (CRSwNP) rises globally.
- Biologic therapies, especially interleukin inhibitors, will dominate the market, offering targeted and long-term treatment options.
- Advances in personalized medicine will drive the demand for biologics, providing more effective and tailored treatment approaches.
- Regulatory approvals of new biologics and expanding indications for existing therapies will further fuel market growth.
- The growing geriatric population will increase the number of CRSwNP patients, thereby boosting treatment demand.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa will present significant growth opportunities.
- The shift towards non-invasive treatments will continue, with patients opting for biologic therapies over surgical options.
- Rising healthcare spending and improved access to advanced therapies will enhance market opportunities, especially in developing regions.
- The high cost of biologic treatments will remain a challenge, requiring companies and governments to explore pricing strategies for wider access.
- Ongoing advancements in diagnostic tools will enable earlier detection of CRSwNP, supporting earlier and more effective treatment intervention.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
what is the current size of the Nasal Polyposis Treatment Market?
What factors are driving the growth of the Nasal Polyposis Treatment Market?
What are some challenges faced by the Nasal Polyposis Treatment Market?
Who are the major players in the Nasal Polyposis Treatment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Nasal Polyposis Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Nasal Polyposis Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,612 million → 2032: USD 7,748.26 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Nasal Polyposis Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Nasal Polyposis Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Nasal Polyposis Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Nasal Polyposis Treatment Market Drivers
- 3.3 Nasal Polyposis Treatment Market Restraints & Challenges
- 3.4 Nasal Polyposis Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Nasal Polyposis Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Nasal Polyposis Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Nasal Polyposis Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Nasal Polyposis Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Nasal Polyposis Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Nasal Polyposis Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Nasal Polyposis Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Nasal Polyposis Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Nasal Polyposis Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Nasal Polyposis Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Nasal Polyposis Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Nasal Polyposis Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Nasal Polyposis Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Nasal Polyposis Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Nasal Polyposis Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Nasal Polyposis Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Nasal Polyposis Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Nasal Polyposis Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Nasal Polyposis Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
