
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Neo And Challenger Bank Market Size 2024 | USD 168822.24 Million |
| Neo And Challenger Bank Market, CAGR | 46.24% |
| Neo And Challenger Bank Market Size 2032 | USD 3531498.98 Million |
Market Overview:
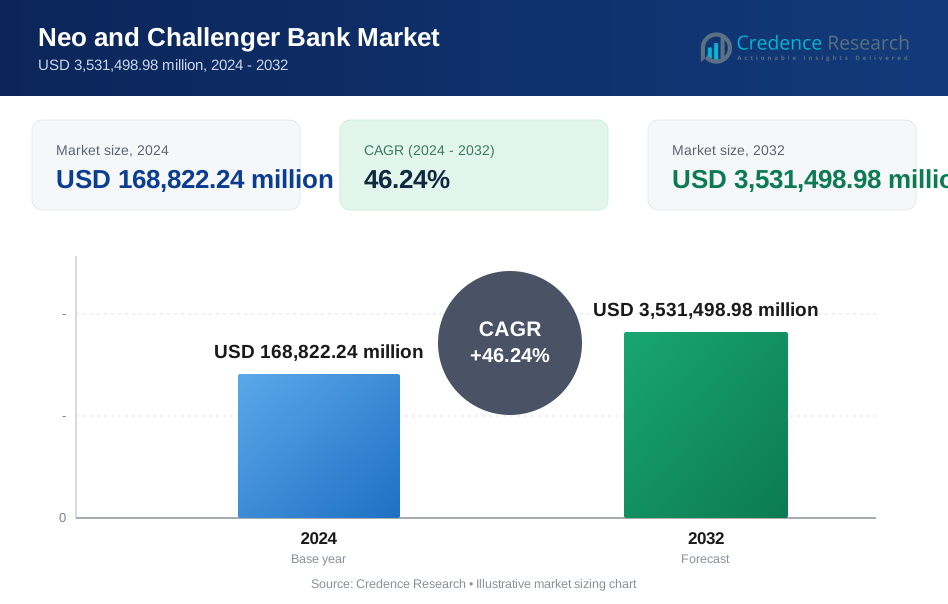
Neo And Challenger Bank Market size was valued at USD 168822.24 million in 2024 and is anticipated to reach USD 3531498.98 million by 2032, at a CAGR of 46.24% during the forecast period (2024-2032).
The market is primarily driven by several key factors. First, the growing trend of digitalization in the financial sector has led to the emergence of new, innovative banking models that focus on providing personalized, customer-centric services. The flexibility and low operating costs of neo and challenger banks, coupled with their ability to offer niche services like cryptocurrency support, have resonated with younger generations. These digital-first solutions are not only more agile but also have the ability to scale rapidly without the constraints of traditional banking infrastructure. Additionally, the increasing number of unbanked and underbanked populations globally is driving demand for accessible and affordable financial services, enabling financial inclusion for previously underserved markets. Enhanced security measures, such as biometric authentication, and advancements in artificial intelligence (AI) and machine learning, further boost the appeal of these digital banks, offering customers a safer and more efficient banking experience.
Regionally, Europe holds the largest share of the Neo and Challenger Bank Market, led by the United Kingdom, where fintech innovation has flourished. The regulatory landscape in Europe has been favorable to the growth of digital banking, with governments encouraging innovation and competition in the sector. North America follows closely, with the U.S. witnessing a surge in challenger bank offerings due to favorable regulatory environments and high digital adoption rates. This region's robust digital infrastructure and large, tech-savvy customer base further contribute to its rapid growth. The Asia Pacific region is expected to experience the fastest growth, driven by the rising middle class and rapid digital transformation across countries like India and China. The proliferation of mobile devices and the increasing shift toward cashless payments are pivotal in driving adoption. As more markets open up to digital banking solutions, the growth potential remains significant across all regions, positioning neo and challenger banks for sustained expansion globally.
Market Insights:
- The Neo and Challenger Bank market is expected to grow from USD 168,822.24 million in 2024 to USD 3,531,498.98 million by 2032, driven by strong digitalization trends.
- Digital-first solutions, offering low operating costs and personalized services, are increasingly appealing to younger, tech-savvy generations.
- Neo and challenger banks play a significant role in improving financial inclusion by offering accessible and affordable services to unbanked and underbanked populations.
- The market benefits from favorable regulatory support in regions like Europe and North America, with initiatives like Open Banking facilitating growth.
- AI, machine learning, and biometric security advancements are enhancing customer experiences and operational efficiency, boosting market growth.
- Europe dominates the market, accounting for 40% of global share, with the UK leading in fintech innovation and digital adoption.
- Asia Pacific is experiencing the fastest growth due to rising smartphone penetration, digital payment adoption, and a large unbanked population.
Market Drivers:
Digitalization and Technological Advancements
The rise of digital technologies has been a primary driver in the growth of neo and challenger banks. Traditional banking models are increasingly being replaced by more agile, tech-driven solutions that offer a wide array of services through digital platforms. With the increasing penetration of smartphones and internet connectivity, these banks are offering customers seamless, 24/7 access to banking services such as account management, fund transfers, and lending. Moreover, the ability of neo and challenger banks to integrate cutting-edge technologies, such as Artificial Intelligence (AI) and Machine Learning (ML), enhances the customer experience by providing personalized financial products and predictive services. This adoption of technology also reduces operational costs significantly, making these institutions highly competitive compared to traditional banks.
Growing Demand for Financial Inclusion
Neo and challenger banks are playing a crucial role in improving financial inclusion globally. A large segment of the global population, particularly in developing countries, remains unbanked or underbanked due to geographical limitations, complex banking procedures, and high costs associated with traditional banking services. For instance, in Nigeria, neobanks have gained widespread acceptance by offering affordable and easy-to-use banking services to mobile users, significantly reducing barriers for the unbanked. Neo and challenger banks, with their cost-effective and easily accessible digital platforms, are providing these underserved populations with a way to access financial services. These institutions focus on providing basic banking products such as savings accounts, loans, and payment services to individuals who have been excluded from the traditional banking system, helping to reduce the global unbanked rate.
Regulatory Support and Evolving Policies
Governments worldwide are increasingly recognizing the importance of fostering innovation in the financial services sector. Many countries, particularly in Europe, have established favorable regulatory frameworks to support the growth of fintech and digital banking. For instance, the UK’s Prudential Regulation Authority (PRA) granted regulatory approval to Atom Bank, enabling it to launch savings accounts and expand its digital offerings for individuals and businesses. Regulatory initiatives, such as the EU’s Payment Services Directive (PSD2) and the UK’s Open Banking framework, are designed to promote transparency, competition, and innovation within the banking industry. These policies have created a conducive environment for neo and challenger banks to flourish, enabling them to compete with traditional banks on a more level playing field while ensuring that they comply with necessary standards to safeguard consumer interests.
Consumer Preference for Convenience and Cost-Effectiveness
One of the key drivers of the neo and challenger bank market is the shift in consumer preferences. As customers increasingly demand greater convenience and more accessible banking options, digital-first solutions that are easy to use and cost-effective are becoming more appealing. Neo and challenger banks typically offer lower fees, more flexible banking options, and faster services compared to traditional banks. Additionally, their ability to tailor services to individual customer needs through data-driven insights is fostering customer loyalty and satisfaction. This growing demand for more efficient, user-centric banking services is expected to continue driving the adoption of neo and challenger banks worldwide, as customers increasingly prioritize convenience over traditional in-branch services.
Market Trends:
Rise of Neo bank and Digital-Only Banking Models
One of the most prominent trends in the neo and challenger bank market is the growing adoption of neobanks and digital-only banking models. Neobanks, which operate solely through digital channels without traditional brick-and-mortar branches, are gaining traction among consumers due to their low operational costs and seamless customer experience. These banks offer highly convenient and efficient banking services such as instant money transfers, automated savings, and personalized financial management tools. The demand for these services is driven by younger generations who prioritize flexibility, speed, and cost-effectiveness over traditional in-branch banking.
Integration of Artificial Intelligence and Machine Learning
Another key trend is the increasing use of Artificial Intelligence (AI) and Machine Learning (ML) to enhance customer experience and improve banking services. Neo and challenger banks are leveraging AI to provide personalized financial advice, automate customer service through chatbots, and offer smarter fraud detection systems. For instance, Bank of America’s virtual assistant Erica uses NLP and ML to deliver personalized financial insights and proactive fraud alerts. The use of AI and ML allows these banks to better understand customer behavior, predict needs, and offer tailored products. This level of personalization is attracting a wider customer base, particularly tech-savvy individuals seeking customized solutions.
Focus on Cryptocurrency and Blockchain Solutions
The incorporation of cryptocurrency and blockchain technology is also a significant trend within the market. Many neo and challenger banks are expanding their services to include cryptocurrency trading, digital wallets, and blockchain-based solutions. For instance, Juno offers USD banking solutions for crypto users, integrating seamless fiat-to-crypto conversions. This trend is driven by increasing consumer interest in decentralized finance and alternative investments. As cryptocurrencies become more mainstream, digital banks are positioning themselves as key players in the rapidly growing digital asset space, attracting a new generation of investors.
Expansion into Emerging Markets
Lastly, the expansion of neo and challenger banks into emerging markets is gaining momentum. These banks are capitalizing on the increasing smartphone penetration and internet access in developing countries to offer affordable and accessible banking services. This trend is helping to improve financial inclusion by providing essential banking services to unbanked and underbanked populations, driving further growth in the sector.
Market Challenges Analysis:
Regulatory and Compliance Challenges
One of the primary challenges faced by neo and challenger banks is navigating the complex regulatory landscape. As digital banking grows in popularity, governments around the world are imposing stricter regulations to ensure consumer protection, financial stability, and data security. For instance, in India, the Reserve Bank of India (RBI) has introduced specific guidelines for digital banking entities to ensure robust cybersecurity measures and compliance with Know Your Customer (KYC) norms, which have helped streamline operations for neobanks like RazorpayX. Compliance with these regulations can be particularly challenging for digital-only banks that operate across multiple jurisdictions, as they must adapt to differing rules and standards in each market. The evolving nature of these regulations requires constant monitoring and adjustment of business practices, adding further complexity. Additionally, regulatory bodies are still developing frameworks for new financial technologies such as cryptocurrencies and blockchain, which adds further uncertainty. The need for ongoing compliance with anti-money laundering (AML), know your customer (KYC), and other regulatory requirements increases operational costs and can limit the speed at which neo and challenger banks can scale their services. The increasing regulatory burden may also deter smaller players from entering the market or expanding their offerings.
Consumer Trust and Security Concerns
Another significant challenge in the neo and challenger bank market is building and maintaining consumer trust. Many potential customers remain hesitant to fully embrace digital-only banking due to concerns over security, fraud, and the reliability of new financial institutions. Despite advances in cybersecurity and data protection, digital banks are prime targets for cyberattacks, and breaches can severely damage a bank's reputation and customer base. The rapid growth in digital transactions and mobile banking also creates more entry points for malicious actors, increasing the potential for financial fraud. As customers increasingly share personal and financial data online, the risk of data breaches or misuse also becomes more pronounced. In addition, while many digital banks offer innovative services, some customers may still prefer the personal touch and familiarity of traditional banking, which can hinder the adoption of neo and challenger banks, especially among older demographics. Overcoming these security concerns and building trust will be crucial for the long-term success and sustainability of the digital banking sector. As trust grows, however, these banks can establish themselves as reliable alternatives to traditional financial institutions.
Market Opportunities:
The Neo and Challenger Bank market presents significant growth opportunities, particularly in emerging economies where digital infrastructure is rapidly expanding. As mobile phone penetration increases and internet access becomes more widespread in developing regions, there is a vast untapped customer base that these digital banks can target. Neo and challenger banks can leverage their low-cost, mobile-first models to offer affordable financial services to the unbanked and underbanked populations in countries across Asia, Africa, and Latin America. By providing easy access to basic banking products such as savings accounts, payments, and microloans, these banks can drive financial inclusion and empower individuals who have been traditionally excluded from the formal banking system. This offers substantial growth potential, as many of these regions lack sufficient access to physical bank branches but have growing demand for digital financial services.
Another key opportunity for neo and challenger banks lies in the growing consumer demand for alternative financial products, such as cryptocurrencies and investment services. With the increasing popularity of digital currencies and the rise of retail investors, these digital banks can incorporate cryptocurrency trading and blockchain-based solutions into their offerings. Additionally, as consumers seek more personalized banking experiences, there is an opportunity to leverage data analytics, AI, and machine learning to offer tailored financial products, investment advice, and savings tools. These innovations can enhance customer engagement, increase customer loyalty, and attract new segments. By expanding into niche markets and adopting innovative technologies, neo and challenger banks can differentiate themselves in a competitive landscape and drive sustained growth.
Market Segmentation Analysis:
By Type
The Neo and Challenger Bank market is segmented by type into two primary categories: neobanks and challenger banks. Neobanks are fully digital banks that operate exclusively online without any physical branches, offering services such as savings accounts, money transfers, and loans. Challenger banks, on the other hand, are established financial institutions that have incorporated digital banking solutions alongside their traditional services, providing a hybrid model. Neobanks dominate the market, especially in regions with high mobile and internet penetration, due to their low operational costs and flexibility.
By Service Offered
The market is also segmented by the services offered, including payment services, lending, wealth management, and others. Payment services represent the largest share of the market, driven by the increasing adoption of mobile payments and digital wallets. Lending services are gaining traction as neo and challenger banks offer personal loans, mortgages, and small business loans with lower fees and more efficient processing compared to traditional banks. Wealth management services, including investment products and financial planning, are emerging as a growing area of interest as these banks leverage technology for personalized financial advice.
By End-User
In terms of end-users, the market serves both individual consumers and businesses. Individual consumers form the largest segment, driven by the growing demand for digital banking solutions, especially among younger, tech-savvy populations. Businesses, particularly small and medium-sized enterprises (SMEs), are also increasingly adopting digital banking services due to their cost-efficiency and ease of use. The market’s rapid growth is largely fueled by the increasing shift toward mobile-first banking solutions among consumers and businesses alike.
Segmentations:
By Type
- Neobanks
- Challenger Banks
By Service Offered
- Payment Services
- Lending Services
- Wealth Management
- Insurance
- Other Services
By End-User
- Individual Consumers
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe
Europe holds the largest market share, accounting for 40% of the global market in 2023. The United Kingdom is the primary driver of this growth, with a well-established fintech ecosystem, favorable regulatory environment, and a high level of digital adoption among consumers. Regulatory initiatives such as Open Banking and the EU’s PSD2 have facilitated innovation in the digital banking space, allowing neo and challenger banks to provide more personalized and efficient services. The widespread shift toward mobile banking and the increasing demand for low-cost, user-friendly financial solutions have propelled the expansion of digital-only banking models across the region. Additionally, many consumers in Europe are becoming more comfortable with the idea of managing their finances through digital platforms, contributing to the region's dominant market share. As digital-first banking continues to gain popularity, other European countries are also adopting similar regulatory frameworks to boost fintech innovation.
North America
North America, particularly the United States, follows closely, capturing 30% of the global market. The region benefits from a highly developed digital infrastructure, widespread internet access, and a tech-savvy population. The regulatory landscape in the U.S. has supported the growth of neo and challenger banks, with initiatives designed to foster innovation in financial services. The demand for digital banking solutions in North America is driven by consumer preferences for convenience, lower fees, and faster services compared to traditional banks. The emergence of financial technologies such as AI, machine learning, and blockchain also contributes to the rapid adoption of digital banking solutions, making the U.S. a key market for neo and challenger banks. The shift towards mobile-first banking in the U.S. has also prompted more traditional banks to adopt digital banking features to stay competitive in the market.
Asia Pacific
Asia Pacific holds the third-largest market share, contributing 25% to the global market. The region is experiencing rapid digital transformation, driven by increasing smartphone penetration, internet connectivity, and a growing middle class in countries such as China, India, and Japan. The rise of mobile-first banking solutions, combined with a large unbanked and underbanked population, offers immense growth opportunities for neo and challenger banks in the region. The market is also driven by the rising adoption of digital payments, mobile wallets, and other fintech solutions. As consumers in Asia Pacific embrace these digital banking services, the market for neo and challenger banks is expected to expand rapidly, particularly in emerging economies where traditional banking infrastructure is limited. The rapid shift toward cashless societies further propels the growth of digital-only financial institutions in this region, positioning Asia Pacific as a critical market for the future of digital banking.
Key Player Analysis:
- Monzo Bank Limited
- MyBank
- Nubank
- Varo Money
- Atom Bank plc
- N26
- Movencorp, Inc.
- UBank limited
- Tandem Bank
- Revolut
- Number26 GmbH
- WeBank
- Fidor Solutions AG
- Simple Finance Technology Corporation
- Chime
Competitive Analysis:
The Neo and Challenger Bank market is highly competitive, with several key players dominating the landscape. Neobanks such as Chime, Revolut, and Monzo have established strong footholds by offering user-friendly, cost-effective banking solutions tailored to digitally native consumers. These players differentiate themselves with minimal fees, mobile-first services, and seamless digital experiences. On the other hand, challenger banks like N26, Starling Bank, and SoFi combine traditional banking expertise with innovative digital services, providing a hybrid model that appeals to a broader customer base. These banks often leverage advanced technologies like artificial intelligence (AI) and machine learning to enhance customer experience, optimize operations, and offer personalized financial services. Regulatory compliance, data security, and expanding service offerings are key challenges faced by these players. The competition is expected to intensify as more players enter the market, focusing on customer-centric services, financial inclusion, and technological innovation.
Recent Developments:
- In June 2024, Monzo Bank announced its first annual profit of £15.4 million, a significant turnaround from a loss of £116.3 million the previous year, indicating a strong recovery in its financial performance.
- In September 2024, Nubank announced plans to expand into additional Latin American markets, aiming to replicate its success in Brazil and enhance its regional presence.
- In June 2024, Atom Bank reported its strongest financial year, achieving full profitability with operating profit rising to £27m (up from £4m in 2023), driven by a 39% increase in lending and a 5* customer service rating.
Market Concentration & Characteristics:
The Neo and Challenger Bank market is characterized by a moderately concentrated competitive landscape, with a few dominant players capturing significant market share, while numerous smaller and emerging institutions continue to enter the space. Leading companies such as Revolut, Monzo, Chime, and N26 hold a substantial portion of the market, driven by their innovative business models and digital-first banking services. These players distinguish themselves through cost-effective solutions, seamless mobile experiences, and advanced technologies like AI, machine learning, and blockchain. Despite this concentration, the market remains dynamic, with new entrants constantly disrupting the sector, particularly in emerging regions where financial inclusion remains a key focus. The market is highly customer-centric, with a strong emphasis on personalization, convenience, and efficiency. As digital banking continues to evolve, the market is expected to see further consolidation, alongside continuous innovation aimed at addressing consumer demands for improved accessibility, security, and service diversity.
Report Coverage:
The research report offers an in-depth analysis based on Type, Service Offered, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market for neo and challenger banks is expected to continue growing as more consumers shift towards digital banking solutions for convenience and lower costs.
- Increasing mobile and internet penetration in emerging markets will open up significant opportunities for neo and challenger banks to target unbanked and underbanked populations.
- The integration of artificial intelligence, machine learning, and blockchain will further enhance the personalization and efficiency of banking services, attracting more customers.
- Regulatory frameworks in regions like Europe and North America will evolve to accommodate the unique needs of digital-only banks, fostering innovation and competition.
- The demand for alternative financial services, such as cryptocurrency and digital wallets, will rise, leading to the expansion of digital asset offerings by neo and challenger banks.
- Partnerships with fintech firms and traditional financial institutions will increase as these banks seek to enhance service offerings and expand their customer base.
- Security and data privacy will continue to be a priority as neo and challenger banks strive to build trust with customers in an increasingly digital world.
- The focus on customer-centric banking, with tailored products and services, will drive customer loyalty and retention.
- The emergence of new technologies and the adoption of open banking models will lead to more innovative solutions in payments, lending, and wealth management.
- Increased competition will push neo and challenger banks to innovate continuously, providing more value to consumers while driving operational efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of Neo and Challenger Banks?
What is driving the growth of the Neo and Challenger Bank market?
Which regions dominate the Neo and Challenger Bank market?
How are neo and challenger banks benefiting unbanked populations?
What technological advancements are contributing to the growth of Neo and Challenger Banks?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Neo and Challenger Bank Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Neo and Challenger Bank Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 168,822.24 million → 2032: USD 3,531,498.98 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Neo and Challenger Bank Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Neo and Challenger Bank Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Neo and Challenger Bank Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Neo and Challenger Bank Market Drivers
- 3.3 Neo and Challenger Bank Market Restraints & Challenges
- 3.4 Neo and Challenger Bank Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Neo and Challenger Bank Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Neo and Challenger Bank Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Neo and Challenger Bank category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Neo and Challenger Bank Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Neo and Challenger Bank Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Neo and Challenger Bank market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Neo and Challenger Bank Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Neo and Challenger Bank Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Neo and Challenger Bank Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Neo and Challenger Bank (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Neo and Challenger Bank Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Neo and Challenger Bank Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Neo and Challenger Bank Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Neo and Challenger Bank Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Neo and Challenger Bank Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Neo and Challenger Bank Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Neo and Challenger Bank Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Neo and Challenger Bank Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Neo and Challenger Bank Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
