
Market Overview:
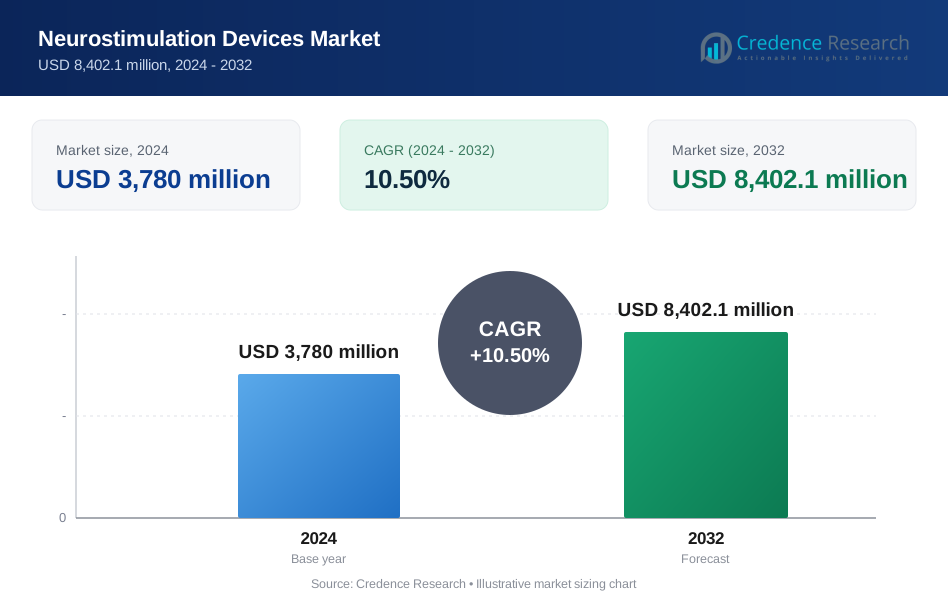
The Neurostimulation Devices Market is projected to grow from USD 3,780 million in 2024 to an estimated USD 8,402.1 million by 2032, with a compound annual growth rate (CAGR) of 10.5% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Neurostimulation Devices Market Size 2024 | USD 3,780 million |
| Neurostimulation Devices Market, CAGR | 10.5% |
| Neurostimulation Devices Market Size 2032 | USD 8,402.1 million |
The market is witnessing strong growth driven by the rising prevalence of neurological disorders, chronic pain, and lifestyle-related diseases. Increasing adoption of minimally invasive procedures and advancements in implantable technologies are boosting demand. Growing awareness about neurostimulation therapies, coupled with supportive regulatory approvals and investments in R&D, is strengthening market expansion. The shift toward personalized and patient-centric treatment solutions is also influencing adoption across healthcare systems.
North America currently leads the market due to advanced healthcare infrastructure, high adoption of innovative therapies, and strong presence of key players. Europe follows closely with strong government support for neurological healthcare. Meanwhile, Asia-Pacific is emerging rapidly, fueled by rising healthcare spending, increasing incidence of neurological disorders, and expanding patient access to advanced treatment options in countries such as China and India.

Market Insights:
- The Neurostimulation Devices Market is projected to grow from USD 3,780 million in 2024 to USD 8,402.1 million by 2032, at a CAGR of 10.5%.
- Rising prevalence of neurological disorders such as Parkinson’s, epilepsy, and chronic pain is driving strong demand.
- Advancements in minimally invasive and non-invasive technologies are enhancing patient acceptance and outcomes.
- High costs of devices and limited accessibility in developing regions act as major restraints.
- North America leads the market with 42% share due to advanced healthcare infrastructure and innovation adoption.
- Europe holds 28% share supported by robust regulatory frameworks and government-backed healthcare initiatives.
- Asia-Pacific accounts for 20% share and is the fastest-growing region, fueled by rising healthcare spending and expanding patient access.
Market Drivers
Rising Prevalence of Neurological Disorders and Chronic Conditions Fueling Growth
The Neurostimulation Devices Market is expanding due to the increasing incidence of neurological disorders such as Parkinson’s disease, epilepsy, and chronic pain conditions. It is benefiting from rising demand for alternative treatment methods where traditional drugs are less effective. Patients suffering from long-term pain or motor disorders are actively seeking implantable and non-invasive devices. Healthcare providers are endorsing these solutions because they offer targeted and sustained relief. Growing cases of depression and migraine are also boosting adoption rates. Governments and health organizations are focusing on reducing the burden of neurological diseases. These supportive measures are accelerating investments in advanced medical devices. The rising need for improved patient quality of life continues to drive significant momentum across global markets.
- For example, Nevro’s Senza® system has been implanted in approximately 132,000 patients globally, delivering long-term relief for back and leg pain. The pivotal SENZA-RCT trial recorded 5% back pain responders and 72.9% leg pain responders at two years, with patients experiencing therapy that remains paresthesia-free.
Technological Advancements Enhancing Device Performance and Patient Outcomes
The Neurostimulation Devices Market is strongly driven by rapid improvements in device design and functionality. Manufacturers are focusing on wireless, rechargeable, and miniaturized systems that improve convenience and durability. It is witnessing a shift toward precision therapy through closed-loop stimulation technologies. This evolution ensures tailored stimulation patterns that optimize treatment outcomes. Research initiatives are enabling integration of digital platforms and AI to personalize therapies. Patients are gaining access to less invasive surgical procedures, reducing risks and recovery time. Healthcare providers are increasingly adopting next-generation devices due to their efficiency and reliability. The technological landscape continues to redefine treatment standards in neurostimulation, propelling global market growth.
Supportive Regulatory Environment and Favorable Reimbursement Policies
The Neurostimulation Devices Market is gaining traction from supportive regulatory frameworks and reimbursement systems in developed countries. It is supported by approvals from agencies that accelerate commercialization of advanced therapies. Insurance coverage for procedures involving neurostimulation devices enhances affordability and accessibility. Governments are recognizing the clinical benefits of these treatments and expanding policy support. Strong collaboration between industry players and healthcare authorities strengthens market growth. Manufacturers are encouraged to innovate due to transparent approval pathways. Increasing clinical trials are validating safety and efficacy, encouraging higher adoption. Reimbursement incentives are ensuring both patients and hospitals embrace neurostimulation technology widely.
- For example, Abbott’s Proclaim XR spinal cord stimulation system received FDA approval on September 26, 2019. It delivers up to 10 years of battery life at low-dose BurstDR™ settings, supports remote therapy adjustments through the NeuroSphere™ Virtual Clinic, and is MRI-ready with expanded compatibility. In January 2023, the FDA approved an additional indication for treating painful diabetic peripheral neuropathy.
Growing Awareness and Rising Demand for Non-Pharmacological Treatment Options
The Neurostimulation Devices Market is benefiting from heightened awareness about non-drug alternatives. Patients are increasingly aware of potential side effects of long-term pharmaceutical use. It is driving greater interest in advanced devices that manage symptoms without dependency on drugs. Physicians are recommending neurostimulation devices as complementary solutions to conventional therapies. Expanding educational programs by hospitals and device makers is boosting awareness further. Patients are prioritizing personalized treatment experiences with minimal adverse reactions. The growing aging population is particularly drawn to non-invasive treatment options. Public awareness campaigns are ensuring stronger patient acceptance and sustained growth momentum for neurostimulation devices.
Market Trends
Integration of Digital Health Technologies in Neurostimulation Devices
The Neurostimulation Devices Market is witnessing a surge in integration with digital health platforms. Device manufacturers are embedding remote monitoring features to track patient outcomes more effectively. It is enabling physicians to make data-driven adjustments in real time. The adoption of mobile applications and cloud-based systems ensures improved connectivity between patients and providers. AI algorithms are being used to personalize therapy schedules and stimulation intensity. Digital ecosystems are expanding collaboration between doctors, patients, and caregivers. Integration with wearable technology is enhancing compliance and accessibility. This digital shift is redefining how neurostimulation therapies are delivered and optimized globally.
Expanding Applications Beyond Traditional Neurological Disorders
The Neurostimulation Devices Market is experiencing growth through expansion into non-traditional applications. Devices once limited to chronic pain or Parkinson’s are now targeting gastrointestinal and urological conditions. It is also gaining traction in obesity control and mental health treatments. Clinical research is supporting the efficacy of neurostimulation in broader therapeutic areas. Healthcare providers are increasingly adopting these devices to treat complex and multi-symptom conditions. The diversification of use cases is opening new revenue streams for manufacturers. Rising patient acceptance in non-conventional treatments is pushing this expansion further. The market scope is steadily widening, shaping long-term growth opportunities.
- For example, Medtronic’s InterStim™ sacral neuromodulation system has treated over 350,000 patients globally for conditions like overactive bladder and fecal incontinence. Clinical evidence shows it delivers three times greater quality of life improvement compared to standard medication-based therapy.
Focus on Minimally Invasive and Non-Invasive Device Solutions
The Neurostimulation Devices Market is trending toward minimally invasive and non-invasive therapies. Patients are seeking solutions that avoid complex surgical procedures. It is fostering development of external and implantable systems with simplified implantation techniques. Surgeons are adopting new methods that reduce procedural risks and downtime. The availability of portable, user-friendly systems is improving accessibility in outpatient settings. Patient comfort and ease of use remain critical factors in product design. Increasing demand for home-based neurostimulation devices is reinforcing this trend. The shift aligns with global healthcare priorities of efficiency, safety, and patient-centric care.
- For example, SPR Therapeutics’ SPRINT® PNS System has treated more than 20,000 patients globally. The device is a minimally invasive, outpatient 60-day treatment that requires no permanent implant, and physicians generally complete each procedure in under 30 minutes.
Collaborations, Mergers, and Expanding Global Market Reach
The Neurostimulation Devices Market is shaped by strategic alliances and corporate expansion. Companies are forming partnerships with hospitals, universities, and research institutes to accelerate innovation. It is also experiencing increased merger and acquisition activity to strengthen product portfolios. Global players are expanding into emerging markets with growing healthcare infrastructure. Local manufacturers are forming distribution partnerships to expand accessibility. Multinational firms are investing in localized manufacturing to reduce costs and meet regional demands. Collaborative efforts are driving faster adoption of cutting-edge devices worldwide. This consolidation of resources and expertise enhances competitiveness and long-term sustainability in the market.
Market Challenges Analysis
High Costs and Limited Accessibility to Advanced Devices
The Neurostimulation Devices Market faces barriers due to high treatment and device costs. It is restricting adoption in low and middle-income countries with limited healthcare budgets. Many patients cannot afford long-term therapies despite proven clinical benefits. Healthcare systems in developing regions struggle to cover expenses under public programs. Complex surgical implantation procedures also raise costs, limiting adoption. Hospitals face challenges in balancing investments with return on outcomes. Insurance coverage gaps persist in several emerging markets, further affecting accessibility. Limited affordability continues to constrain global penetration of neurostimulation technologies.
Safety Concerns and Technical Limitations Affecting Adoption
The Neurostimulation Devices Market is challenged by concerns over device safety and technical performance. It is facing scrutiny regarding risks such as infections, hardware failures, and lead migration. Some patients experience adverse reactions, reducing confidence in adoption. Battery-related complications and maintenance requirements increase operational issues. Technical limitations in stimulation precision also impact long-term treatment effectiveness. Physicians remain cautious in recommending devices without strong clinical validation. Manufacturers are under pressure to improve safety and reliability. Addressing these limitations remains critical for building broader acceptance and trust.
Market Opportunities
Expansion into Emerging Healthcare Markets with Growing Demand
The Neurostimulation Devices Market holds significant opportunities in emerging economies. It is positioned to benefit from rising investments in healthcare infrastructure in Asia-Pacific, Latin America, and the Middle East. Expanding patient populations with neurological disorders are creating demand for advanced treatment solutions. Local governments are launching initiatives to improve access to innovative therapies. Medical tourism is also attracting patients to regions with advanced care facilities. Companies entering these markets with affordable solutions will gain long-term advantages. Strengthening distribution networks and partnerships in these regions enhances accessibility. Emerging economies present untapped potential for accelerating global adoption of neurostimulation devices.
Innovation in Non-Invasive and Next-Generation Technologies
The Neurostimulation Devices Market is finding new opportunities in the development of non-invasive and next-gen systems. It is expected to witness higher adoption of wearable, wireless, and portable devices. Patients prefer solutions with minimal surgical risks and greater convenience. Integration of AI-driven stimulation and real-time monitoring is creating next-level therapies. Manufacturers investing in ergonomic and user-friendly designs will capture stronger market positions. Growth in outpatient and home-care settings is fueling demand for advanced systems. Device makers focusing on combining safety, comfort, and performance will secure competitive advantages. Innovation-led opportunities are paving the way for sustained expansion of the market.
Market Segmentation Analysis:
The Neurostimulation Devices Market is segmented
By product into deep brain stimulators, gastric electric stimulators, spinal cord stimulators, sacral nerve stimulators, vagus nerve stimulators, transcutaneous electrical nerve stimulation (TENS), and other products. Spinal cord stimulators lead adoption due to their effectiveness in treating chronic pain, while deep brain stimulators are gaining traction in neurological disorders such as Parkinson’s and dystonia. Vagus nerve stimulators and TENS devices are also widely used for non-invasive therapeutic solutions.
- For example, Boston Scientific’s Spectra WaveWriter™ Spinal Cord Stimulator system delivers both paresthesia-based and sub-perception therapies through Combination Therapy. It offers robust personalization via 32-contact leads, 4 ports, waveform automation, and Contour™ Field Shaping. Clinical data demonstrate nearly a 6-point pain score reduction after two years of use.
By application, the market covers Parkinson's disease, epilepsy, depression, dystonia, pain management, urinary and fecal incontinence, essential tremor, gastroparesis, and other applications. Pain management remains the dominant area due to growing cases of chronic pain worldwide. Parkinson’s disease and epilepsy represent strong segments due to rising prevalence and increasing reliance on advanced implantable solutions. Depression and other psychiatric conditions are emerging segments supported by expanding clinical evidence.
- For example, Abbott’s Infinity™ DBS system is FDA approved for treating Parkinson’s disease and essential tremor. It features directional lead technology, an upgradeable wireless platform with iOS-based programming, and includes the NeuroSphere™ Virtual Clinic for remote adjustments.
By end-user, the market is divided into clinics, hospitals, rehabilitation centers, specialty clinics, and medical clinics. Hospitals dominate usage due to access to advanced surgical infrastructure and multidisciplinary expertise. Specialty clinics are expanding their role by focusing on neurological and pain-related treatments. Rehabilitation centers contribute significantly by integrating neurostimulation therapies into long-term patient care. Clinics and medical clinics provide outpatient treatment options that improve accessibility and patient convenience.
Segmentation:
By Product:
- Deep Brain Stimulator
- Gastric Electric Stimulator
- Spinal Cord Stimulator
- Sacral Nerve Stimulator
- Vagus Nerve Stimulator
- Transcutaneous Electrical Nerve Stimulation (TENS)
- Other Products
By Application:
- Parkinson's Disease
- Epilepsy
- Depression
- Dystonia
- Pain Management
- Urinary and Fecal Incontinence
- Essential Tremor
- Gastroparesis
- Other Applications
By End-User:
- Clinics
- Hospitals
- Rehabilitation Centers
- Specialty Clinics
- Medical Clinics
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America holds the largest share of the Neurostimulation Devices Market with 42%. It benefits from advanced healthcare infrastructure, high adoption of innovative technologies, and strong presence of leading manufacturers. Favorable reimbursement policies support widespread use of implantable and non-invasive neurostimulation therapies. Rising cases of neurological disorders such as Parkinson’s disease and epilepsy further drive demand. It is also supported by continuous clinical research and strong collaborations between device makers and healthcare institutions. Expanding awareness about non-pharmacological treatment methods ensures steady growth across the United States and Canada.
Europe accounts for 28% of the Neurostimulation Devices Market, supported by government initiatives and robust medical device regulations. It benefits from increasing demand for non-invasive therapies and a high prevalence of neurological conditions. Countries such as Germany, the United Kingdom, and France are leading markets with advanced hospital networks. Favorable policy support encourages investment in patient-centric treatments. Rising adoption of advanced devices in Italy and Spain also strengthens regional growth. It is further shaped by strategic collaborations between European research institutes and industry players to accelerate product innovation.
Asia-Pacific represents 20% of the Neurostimulation Devices Market and is the fastest-growing regional segment. Rising healthcare spending, growing awareness, and an expanding patient base drive rapid adoption. Countries such as China, Japan, and India are key contributors due to increasing cases of chronic pain and neurological disorders. Hospitals and specialty clinics in the region are embracing advanced neurostimulation solutions. It is gaining momentum with medical tourism and expanding healthcare access in emerging economies. South Korea and Australia add to the region’s growth potential with investments in advanced therapeutic solutions. Middle East & Africa hold 6%, while South America contributes 4%, both showing steady adoption due to rising healthcare modernization.
Key Player Analysis:
- Medtronic plc
- Boston Scientific Corporation
- Abbott Laboratories
- Nevro Corporation
- LivaNova PLC
- NeuroPace, Inc.
- Axonics Modulation Technologies
- Inspire Medical Systems, Inc.
- Cochlear Limited
- NeuroSigma Inc.
- Neuralink
- Neuronetics
- Soterix Medical, Inc.
- SPR Therapeutics, Inc.
- NDI Medical, Inc.
Competitive Analysis:
The Neurostimulation Devices Market is highly competitive with global and regional players focusing on innovation and portfolio expansion. Leading companies such as Medtronic, Abbott, Boston Scientific, and Nevro dominate through strong product pipelines and established distribution networks. It is characterized by continuous advancements in device miniaturization, rechargeable systems, and digital integration to enhance patient outcomes. Companies are investing in clinical trials to expand therapeutic indications and strengthen regulatory approvals. Strategic partnerships with hospitals and research institutes are fostering innovation and broadening market presence. Emerging players are entering with cost-effective and non-invasive devices to capture opportunities in developing regions. Competition remains intense, with firms striving to balance affordability, technological advancements, and global accessibility. This competitive environment ensures steady innovation and improved treatment options for patients worldwide.
Recent Developments:
- In July 2025, Boston Scientific Corporation announced FDA approval of new spinal cord stimulation leads, the Linear™ 3-4 and Linear™ 3-6 Percutaneous Leads, designed to expand lead options for chronic pain management using its Precision Plus™ Spinal Cord Stimulator System.
- In February 2025, Medtronic plc received U.S. FDA approval for its BrainSense™ Adaptive deep brain stimulation (aDBS) system, the world's first closed-loop DBS system that self-adjusts therapy in real time based on individual brain activity for Parkinson’s disease patients.
- In January 2024, Nalu Medical, a U.S.-based company, announced the successful raising of $65 million in a Series E equity financing round. This funding is aimed at advancing the development of their innovative micro-implantable neurostimulation device designed to treat chronic neuropathic pain. The investment will support clinical trials, technology refinement, and expanding accessibility for patients suffering from chronic pain conditions.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising prevalence of neurological disorders and chronic pain will drive sustained adoption of advanced devices.
- Continuous advancements in minimally invasive and non-invasive technologies will increase acceptance among diverse patient groups.
- Integration of artificial intelligence, remote monitoring, and digital health platforms will transform treatment efficiency.
- Expanding healthcare infrastructure in emerging economies will create strong opportunities for device penetration.
- Increasing awareness of mental health conditions will broaden therapeutic applications of neurostimulation technologies.
- Strategic alliances between manufacturers, research institutions, and hospitals will strengthen innovation pipelines.
- Growing focus on personalized medicine will influence the design of tailored stimulation therapies.
- Expansion of reimbursement coverage across developed regions will improve affordability and access.
- Ongoing clinical trials will reinforce safety and efficacy, supporting adoption in new therapeutic areas.
- Rising investments in wearable, wireless, and home-based systems will ensure long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Neurological Disorders and Chronic Conditions
Increasing cases of Parkinson’s disease, epilepsy, chronic pain, and other neurological disorders are driving demand for neurostimulation devices as patients and healthcare providers seek effective alternatives to traditional drug therapies.
Technological Advancements in Device Design and Functionality
Innovations such as wireless, rechargeable, and miniaturized neurostimulation systems, along with closed-loop and AI-integrated technologies, are improving patient outcomes and expanding the range of treatable conditions.
Supportive Regulatory Environment and Reimbursement Policies
Favorable regulatory approvals and expanded insurance coverage in developed markets are making neurostimulation therapies more accessible and affordable, encouraging both hospitals and patients to adopt these advanced solutions.
Growing Awareness and Preference for Non-Pharmacological Treatments
Patients and physicians are increasingly aware of the risks associated with long-term pharmaceutical use, leading to greater adoption of neurostimulation devices as safer, non-drug alternatives for managing chronic and neurological conditions.
Expansion into Emerging Markets
Rising healthcare investments, increasing incidence of neurological disorders, and improved access to advanced treatments in Asia-Pacific, Latin America, and the Middle East & Africa are creating significant growth opportunities for neurostimulation device manufacturers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Neurostimulation Devices Market, and what is its projected size in 2032?
Which segment is leading the market share in terms of indication?
Which segment is expected to post the highest CAGR during the forecast period in terms of implantability?
Which region is fueling the growth of the neurostimulation devices market?
Who are the major players in the global Neurostimulation Devices Market?
What are the major market drivers of the global Neurostimulation Devices market?
What are the major market restraints of the Neurostimulation Devices market?
What are the major market opportunities of the global Neurostimulation Devices market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Deep Brain Stimulator
- 1.2.2 Gastric Electric Stimulator
- 1.2.3 Spinal Cord Stimulator
- 1.2.4 Sacral Nerve Stimulator
- 1.2.5 Vagus Nerve Stimulator
- 1.2.6 Transcutaneous Electrical Nerve Stimulation (TENS)
- 1.2.7 Other Products
- 1.3 By End-User
- 1.3.1 Clinics
- 1.3.2 Hospitals
- 1.3.3 Rehabilitation Centers
- 1.3.4 Specialty Clinics
- 1.3.5 Medical Clinics
- 1.4 By Application
- 1.4.1 Parkinson's Disease
- 1.4.2 Epilepsy
- 1.4.3 Depression
- 1.4.4 Dystonia
- 1.4.5 Pain Management
- 1.4.6 Urinary and Fecal Incontinence
- 1.4.7 Essential Tremor
- 1.4.8 Gastroparesis
- 1.4.9 Other Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,780 million → 2032: USD 8,402.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Neurostimulation Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Neurostimulation Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Neurostimulation Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Neurostimulation Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Neurostimulation Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Neurostimulation Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Neurostimulation Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Neurostimulation Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,780 million → 2032: USD 8,402.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Neurostimulation Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Deep Brain Stimulator
- 12.3.7.2 Gastric Electric Stimulator
- 12.3.7.3 Spinal Cord Stimulator
- 12.3.7.4 Sacral Nerve Stimulator
- 12.3.7.5 Vagus Nerve Stimulator
- 12.3.7.6 Transcutaneous Electrical Nerve Stimulation (TENS)
- 12.3.7.7 Other Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Clinics
- 12.4.7.2 Hospitals
- 12.4.7.3 Rehabilitation Centers
- 12.4.7.4 Specialty Clinics
- 12.4.7.5 Medical Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Parkinson's Disease
- 12.5.7.2 Epilepsy
- 12.5.7.3 Depression
- 12.5.7.4 Dystonia
- 12.5.7.5 Pain Management
- 12.5.7.6 Urinary and Fecal Incontinence
- 12.5.7.7 Essential Tremor
- 12.5.7.8 Gastroparesis
- 12.5.7.9 Other Applications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Neurostimulation Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Neurostimulation Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Neurostimulation Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Neurostimulation Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Boston Scientific Corporation
- 18.4 Abbott Laboratories
- 18.5 Nevro Corporation
- 18.6 LivaNova PLC
- 18.7 NeuroPace, Inc.
- 18.8 Axonics Modulation Technologies
- 18.9 Inspire Medical Systems, Inc.
- 18.10 Cochlear Limited
- 18.11 SPR Therapeutics, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

