
Market Overview
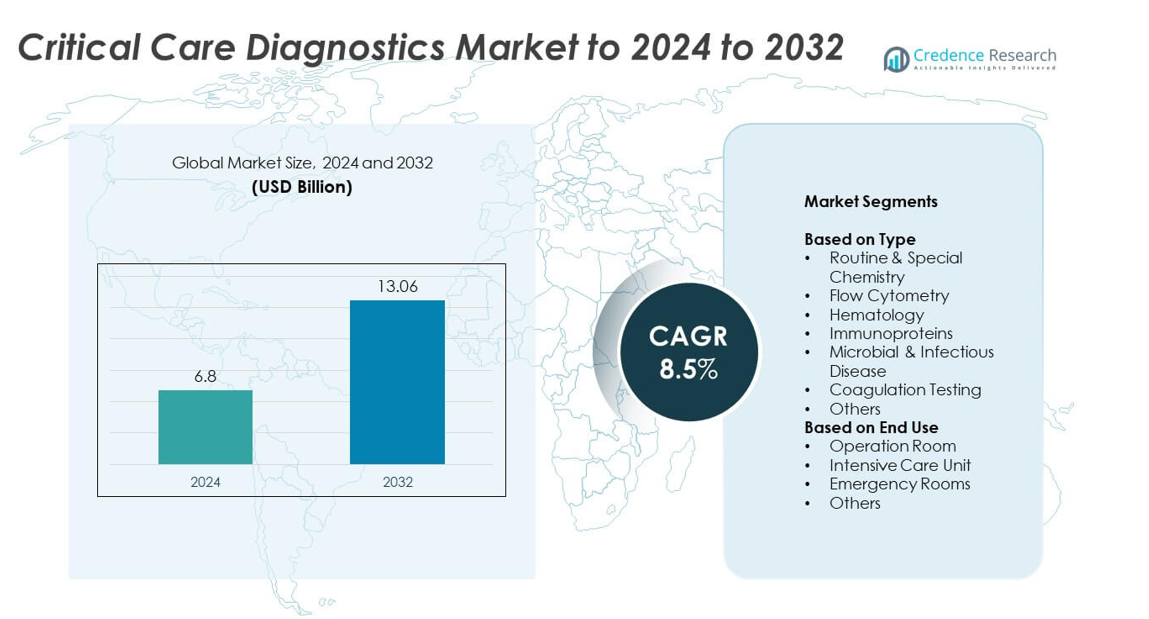
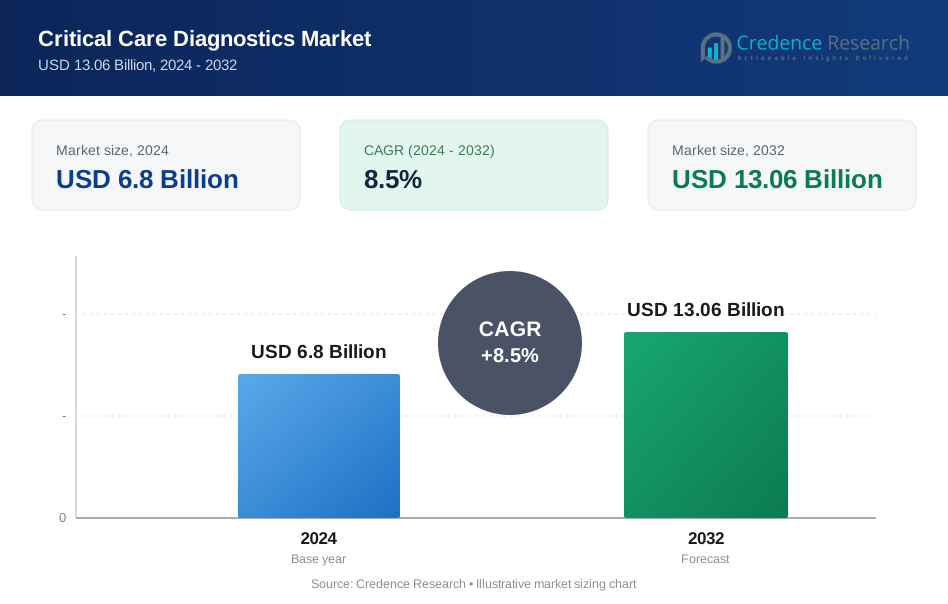
Critical Care Diagnostics Market size was valued at USD 6.8 Billion in 2024 and is anticipated to reach USD 13.06 Billion by 2032, at a CAGR of 8.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Critical Care Diagnostics Market Size 2024 | USD 6.8 Billion |
| Critical Care Diagnostics Market, CAGR | 8.5% |
| Critical Care Diagnostics Market Size 2032 | USD 13.06 Billion |
The critical care diagnostics market is led by prominent players such as Siemens Healthcare Private Limited, BD, Bayer AG, EKF Diagnostics, Abbott, F. Hoffmann-La Roche Ltd, Danaher, bioMérieux, Chembio Diagnostics, and Roche. These companies focus on advancing diagnostic technologies, expanding point-of-care testing, and integrating AI-driven systems to enhance patient outcomes. The competitive landscape is shaped by continuous innovation, regulatory compliance, and strategic collaborations with healthcare providers. Regionally, North America dominates the global market with a 38% share in 2024, supported by advanced healthcare infrastructure, strong R&D capabilities, and high adoption of real-time diagnostic systems across intensive and emergency care units.
Market Insights
- The critical care diagnostics market was valued at USD 6.8 Billion in 2024 and is projected to reach USD 13.06 Billion by 2032, growing at a CAGR of 8.5%.
- Growth is driven by rising cases of sepsis, cardiac, and respiratory disorders, alongside expanding ICU facilities and adoption of point-of-care testing.
- Key trends include integration of AI-based diagnostic tools, automation, and the shift toward molecular and personalized testing to enhance speed and accuracy.
- The market is highly competitive, with global players focusing on innovation, partnerships, and portfolio expansion to strengthen their presence.
- North America leads with a 38% market share, followed by Europe at 27% and Asia Pacific at 22%, while the routine and special chemistry segment dominates by type, accounting for the largest share in 2024.
Market Segmentation Analysis:
By Type
The routine and special chemistry segment held the dominant share in the critical care diagnostics market in 2024. This segment accounted for nearly 28% of the total market due to its vital role in assessing patient metabolic profiles and organ functions. The demand for rapid biochemical testing has increased across ICUs and emergency departments for real-time decision-making. Growth is driven by advancements in automated analyzers, integration of point-of-care systems, and increased adoption of multiparameter testing panels that enhance diagnostic speed and accuracy in critical settings.
- For instance, Beckman Coulter’s AU5800 processes up to 2,000 tests/hour per module.
By End Use
Intensive care units represented the largest share of the critical care diagnostics market in 2024, contributing about 40% of total revenue. These units rely heavily on real-time diagnostic data to guide treatment in life-threatening conditions such as sepsis, cardiac arrest, and respiratory failure. The segment’s growth is fueled by the rising number of critically ill patients, expansion of advanced ICU facilities, and integration of bedside testing technologies that reduce turnaround times and improve clinical outcomes for patients under intensive monitoring.
- For instance, Radiometer’s ABL90 FLEX PLUS reports results in 35 seconds on up to 19 parameters, including blood gases, metabolites like creatinine and urea, electrolytes, and oximetry measurements.
Key Growth Drivers
Rising Prevalence of Chronic and Critical Illnesses
The growing incidence of sepsis, cardiovascular diseases, and respiratory disorders is fueling demand for advanced critical care diagnostics. Hospitals and ICUs are increasingly investing in real-time testing systems to support rapid intervention and improved patient outcomes. Early detection tools, such as high-sensitivity troponin assays and multiplex molecular diagnostics, are becoming essential in managing complex cases. The expanding elderly population further intensifies the need for accurate and quick diagnostic evaluations in intensive and emergency care settings.
- For instance, Siemens’ Atellica VTLi delivers hs-cTnI results in 8 minutes.
Technological Advancements in Diagnostic Systems
Continuous innovation in point-of-care devices, biosensors, and molecular testing platforms is transforming the critical care diagnostics market. Automated systems now deliver faster results with improved accuracy, enabling immediate treatment decisions in life-threatening conditions. Integration of AI-based analytics supports predictive diagnostics and helps clinicians interpret complex data efficiently. These technological improvements enhance workflow efficiency, reduce diagnostic errors, and strengthen overall patient management in high-pressure critical environments.
- For instance, Cepheid's GeneXpert system returns PCR results in a variable amount of time depending on the assay; the Xpert Xpress SARS-CoV-2 assay, can produce positive results in as little as 25 minutes or negative results in around 45 minutes, while other tests like the Xpert MTB/RIF assay for tuberculosis take approximately 90 minutes to under two hours.
Rising Adoption of Point-of-Care Testing (POCT)
The increasing implementation of POCT in intensive care and emergency departments is a key growth driver. Portable diagnostic instruments reduce turnaround times and improve clinical response for patients requiring immediate care. Healthcare facilities are adopting POCT for tests like arterial blood gases, cardiac biomarkers, and coagulation due to its convenience and reliability. The trend aligns with the growing emphasis on decentralized diagnostics that minimize laboratory dependency while maintaining high accuracy levels.
Key Trends & Opportunities
Integration of Artificial Intelligence and Data Analytics
Artificial intelligence is reshaping critical care diagnostics through predictive modeling and automated analysis. AI-enabled systems assist clinicians in detecting abnormalities and predicting patient deterioration before visible symptoms appear. Integration with cloud-based diagnostic platforms allows seamless data sharing across departments, supporting precision medicine and reducing errors. This trend presents opportunities for healthcare providers to enhance efficiency and clinical decision-making in critical settings.
- For instance, Philips’ eICU hub can manage 50–500 remote ICU beds.
Growing Demand for Personalized and Molecular Diagnostics
Advances in genomics and molecular assays are creating opportunities for precision-based critical care testing. Personalized diagnostics enable targeted treatment approaches for patients with severe infections or immune responses. The shift toward molecular-based testing supports early pathogen identification, optimizing antibiotic use and reducing resistance risks. These developments are fostering a new era of tailored diagnostics for critically ill patients across hospitals and specialized care units.
- For instance, bioMérieux’s BioFire BCID2 detects 43 targets in ~1 hour from positive cultures.
Expansion of Critical Care Infrastructure
The expansion of hospitals and ICU facilities, particularly in emerging economies, is opening new growth opportunities. Governments and private investors are focusing on strengthening healthcare infrastructure to manage rising critical illness cases. Increased healthcare spending and strategic collaborations between medical device firms and hospitals are accelerating diagnostic system adoption. This expansion supports wider availability of advanced testing systems across both developed and developing regions.
Key Challenges
High Cost of Advanced Diagnostic Equipment
The high cost of sophisticated diagnostic analyzers and consumables poses a major challenge for healthcare providers. Smaller hospitals and facilities in developing regions struggle with budget limitations, restricting access to advanced testing systems. Additionally, the maintenance and calibration costs of these instruments increase operational expenses. These financial barriers slow the adoption of next-generation diagnostic technologies in low-resource settings, impacting market penetration.
Lack of Skilled Professionals and Integration Barriers
A shortage of trained laboratory and critical care staff limits the effective use of advanced diagnostic systems. Complex equipment requires specialized handling and accurate interpretation to ensure reliable outcomes. Integration challenges between diagnostic devices and hospital information systems also create workflow inefficiencies. Addressing these gaps through targeted training programs and interoperability standards is essential to enhance diagnostic reliability and clinical efficiency in critical environments.
Regional Analysis
North America
North America held the largest share of around 38% in the critical care diagnostics market in 2024. The region benefits from advanced healthcare infrastructure, high adoption of point-of-care testing, and strong presence of major diagnostic companies. Growing prevalence of chronic illnesses such as sepsis, cardiac disorders, and respiratory failures continues to drive market growth. The United States dominates the regional landscape due to significant investments in ICU modernization and AI-driven diagnostic systems, while Canada focuses on improving access to rapid testing solutions in emergency and intensive care facilities.
Europe
Europe accounted for nearly 27% of the global critical care diagnostics market in 2024, supported by a well-established hospital network and favorable regulatory environment. Countries such as Germany, France, and the United Kingdom lead in adopting advanced diagnostic technologies for intensive and emergency care. The region’s emphasis on patient safety, coupled with increased funding for early disease detection programs, strengthens market expansion. Moreover, the integration of molecular diagnostics and automation in hospital laboratories continues to enhance testing efficiency and clinical decision-making in European healthcare systems.
Asia Pacific
Asia Pacific captured about 22% of the critical care diagnostics market in 2024, driven by rapid healthcare infrastructure development and rising investments in hospital expansion. Countries like China, India, and Japan are experiencing growing demand for point-of-care and molecular testing solutions. The increasing burden of infectious diseases and chronic health conditions has accelerated diagnostic equipment adoption. Government initiatives promoting healthcare digitization and intensive care upgrades are fostering market growth, while partnerships between global diagnostic firms and local providers enhance regional access to advanced testing technologies.
Latin America
Latin America represented nearly 8% of the global critical care diagnostics market in 2024, with Brazil and Mexico serving as key growth centers. Expanding healthcare budgets and improved hospital infrastructure are encouraging the deployment of automated diagnostic systems. The region is witnessing gradual adoption of point-of-care technologies to address emergency care needs. Public health programs targeting infection control and early disease diagnosis are also supporting market progress. However, economic disparities and limited access to advanced testing in rural areas continue to restrain overall market potential across Latin America.
Middle East and Africa
The Middle East and Africa region accounted for about 5% of the critical care diagnostics market in 2024. Growth is primarily driven by rising investments in hospital infrastructure and intensive care facilities in Gulf Cooperation Council countries. Increased awareness of early diagnostic interventions for critical conditions such as sepsis and cardiac disorders is boosting demand. South Africa and Saudi Arabia are emerging as key markets with expanding healthcare modernization programs. Despite these advances, limited diagnostic capabilities in lower-income nations remain a challenge for wider adoption across the region.
Market Segmentations:
By Type
- Routine & Special Chemistry
- Flow Cytometry
- Hematology
- Immunoproteins
- Microbial & Infectious Disease
- Coagulation Testing
- Others
By End Use
- Operation Room
- Intensive Care Unit
- Emergency Rooms
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The critical care diagnostics market is highly competitive, with major players such as Siemens Healthcare Private Limited, BD, Bayer AG, EKF Diagnostics, Abbott, F. Hoffmann-La Roche Ltd, Danaher, bioMérieux, Chembio Diagnostics, and Roche leading innovation and expansion. The market is characterized by continuous advancements in diagnostic technologies, automation, and integration of point-of-care testing systems to enhance speed and accuracy. Companies are focusing on strategic collaborations with hospitals and research institutions to strengthen their clinical presence. Product differentiation through AI-enabled platforms and molecular testing solutions is becoming a key competitive factor. Manufacturers are also expanding their global distribution networks to cater to rising demand in developing regions. Continuous R&D investments, coupled with efforts to gain regulatory approvals for new diagnostic assays, are driving portfolio diversification. The competitive environment is shifting toward smart, connected, and patient-centric diagnostic solutions that improve critical care outcomes and operational efficiency in healthcare facilities.
Key Player Analysis
- Siemens Healthcare Private Limited
- BD
- Bayer AG
- EKF Diagnostics
- Abbott
- Hoffmann-La Roche Ltd
- Danaher
- bioMérieux, Inc.
- Chembio Diagnostics, Inc.
- Roche
Recent Developments
- In 2025, Siemens Healthineers unveiled several innovations for critical care at the Asian Oceanian Congress of Radiology (AOCR), including the MAGNETOM Flow MRI.
- In 2025, Roche unveiled its "sequencing by expansion" (SBX) technology, offering enhanced speed, throughput, and flexibility for next-generation sequencing.
- In 2023, Abbott launched its "Vertigo Coach" app in India, a digital health solution to help patients manage their condition
Report Coverage
The research report offers an in-depth analysis based on Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for rapid and accurate diagnostic testing will continue to rise in intensive care settings.
- Integration of artificial intelligence will enhance early disease detection and clinical decision-making.
- Point-of-care testing adoption will expand across hospitals and emergency departments for faster results.
- Molecular diagnostics and genomic testing will gain importance in infection and sepsis management.
- Hospitals will increasingly invest in connected diagnostic platforms for real-time data sharing.
- Emerging economies will witness strong growth due to healthcare infrastructure expansion.
- Automation and miniaturization of diagnostic devices will improve testing accuracy and efficiency.
- Partnerships between healthcare providers and diagnostic firms will accelerate technology integration.
- Rising focus on personalized medicine will drive demand for patient-specific diagnostic tools.
- Continued government support and funding for critical care research will strengthen market development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Critical Care Diagnostics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Critical Care Diagnostics Market projected to grow between 2025 and 2032?
Which Critical Care Diagnostics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Critical Care Diagnostics Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.8 Billion → 2032: USD 13.06 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Critical Care Diagnostics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Critical Care Diagnostics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Critical Care Diagnostics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Critical Care Diagnostics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Critical Care Diagnostics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Critical Care Diagnostics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Critical Care Diagnostics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Critical Care Diagnostics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.8 Billion → 2032: USD 13.06 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Critical Care Diagnostics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Critical Care Diagnostics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Critical Care Diagnostics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Critical Care Diagnostics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
