
Market Overview
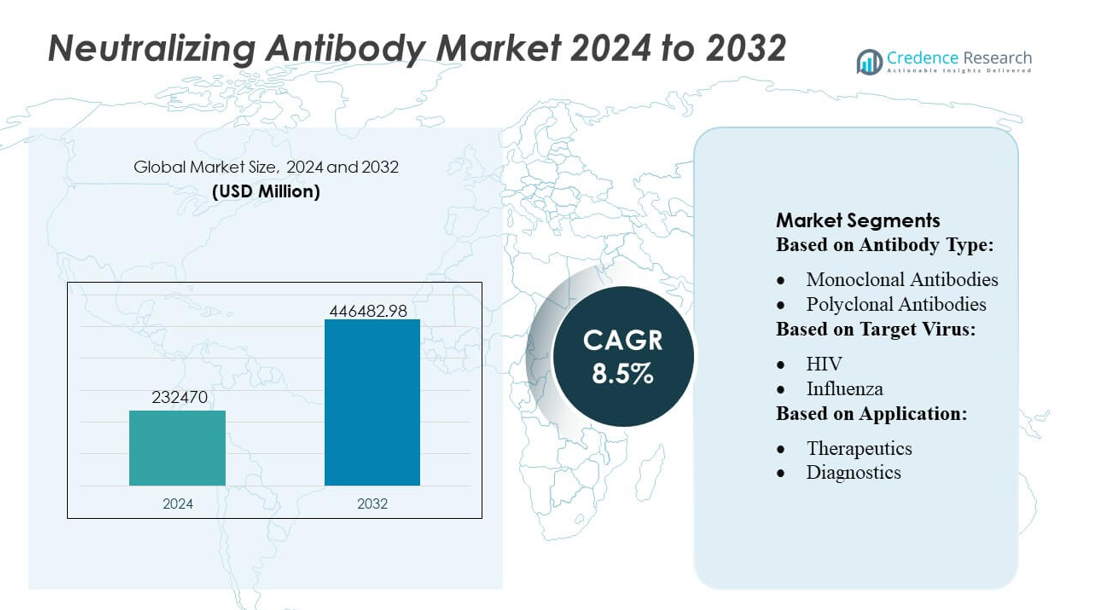
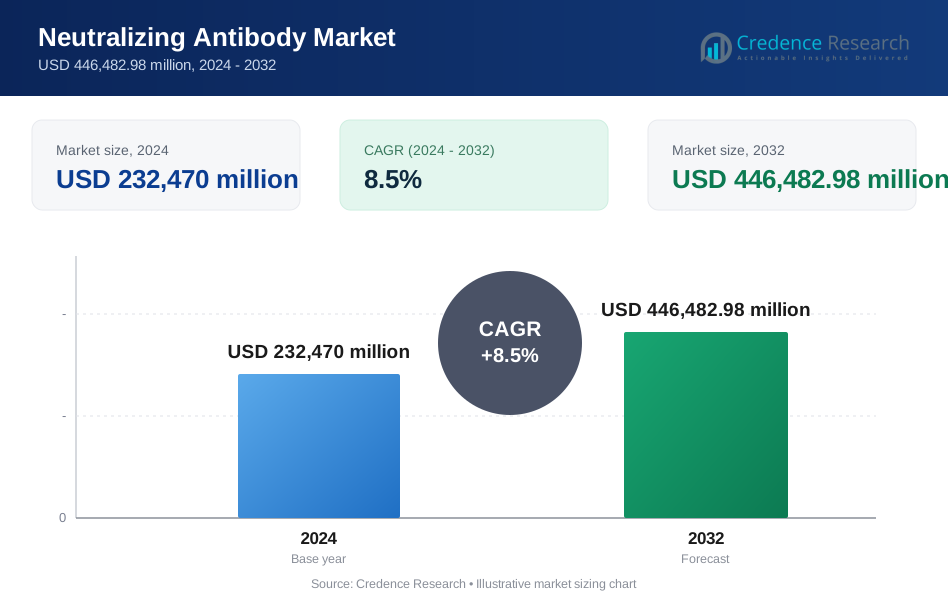
Neutralizing Antibody Market size was valued USD 232470 million in 2024 and is anticipated to reach USD 446482.98 million by 2032, at a CAGR of 8.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Neutralizing Antibody Market Size 2024 | USD 232470 million |
| Neutralizing Antibody Market, CAGR | 8.5% |
| Neutralizing Antibody Market Size 2032 | USD 446482.98 million |
The global neutralizing antibody market features major players such as Pfizer Inc., Regeneron Pharmaceuticals, Inc., AstraZeneca PLC, Roche Holding AG, Eli Lilly and Company, Sanofi SA, GlaxoSmithKline plc, Merck & Co., Inc., and Johnson & Johnson, each maintaining strong R&D pipelines and broad therapeutic portfolios. These firms spearhead development of monoclonal and bispecific neutralizing antibodies targeting infectious diseases and oncology indications, leveraging robust clinical programs and manufacturing capacity. The market exhibits moderate concentration, with top-tier companies sustaining leadership through innovation, regulatory approvals, and global distribution networks. Regionally, North America leads the neutralizing antibody market, accounting for approximately 42% of global share, supported by advanced healthcare infrastructure, high biologics adoption rates, and strong investment in biotechnology. The dominance of North America underscores its critical role in shaping market trends, funding, and therapeutic adoption worldwide.
Market Insights
- The Neutralizing Antibody Market was valued at USD 232,470 million in 2024 and is projected to reach USD 446,482.98 million by 2032, registering a CAGR of 8.5%.
- Market growth is driven by increasing adoption of monoclonal and bispecific antibodies for infectious diseases and oncology, supported by expanding clinical pipelines from leading developers.
- A key trend includes rising integration of AI-driven antibody discovery platforms, enabling faster identification of high-affinity neutralizing antibodies and strengthening innovation among top-tier companies.
- Competitive intensity remains high as Pfizer, Regeneron, AstraZeneca, Roche, and Eli Lilly continue to secure regulatory approvals; however, restraints include high production costs, complex manufacturing, and supply-chain dependencies for biologics.
- Regionally, North America holds 42% share, driven by strong biologics uptake, while among segments, monoclonal neutralizing antibodies dominate due to broad therapeutic applicability and extensive commercialization by global pharmaceutical leaders.
Market Segmentation Analysis:
By Antibody Type
Monoclonal antibodies dominate the Neutralizing Antibody Market with an estimated 72–75% share, supported by their high specificity, consistent batch performance, and expanded clinical adoption across infectious disease management. Their rapid scale-up through recombinant platforms and strong regulatory approval pipeline further strengthens leadership. Polyclonal antibodies maintain steady demand in niche and emergency-use applications, particularly where broad epitope recognition provides therapeutic advantage. Growth across both categories is reinforced by rising viral mutation rates, increasing global surveillance programs, and accelerating investments in precision antibody engineering.
- For instance, Abbott’s SARS-CoV-2 IgG test running on its ARCHITECT and Alinity platforms demonstrated a specificity of 99.6% and sensitivity of 100% when administered 14 or more days after symptoms onset.
By Target Virus
SARS-CoV-2 remains the leading target virus with an estimated 48–50% share, driven by global vaccination programs, variant-focused therapeutic development, and ongoing demand for next-generation neutralizing antibody candidates. HIV represents the second-largest segment due to long-term research funding, development of broadly neutralizing antibodies, and persistent global disease burden. Influenza, Ebola, Zika, and Hepatitis C collectively contribute incremental growth as manufacturers enhance antibody libraries for emerging and re-emerging pathogens. The expansion of pandemic-preparedness frameworks and cross-reactive antibody platforms continues to support diversified pipeline development across all viral categories.
- For instance, AstraZeneca’s Evusheld (tixagevimab–cilgavimab) demonstrated a mean serum half-life of approximately 90 days due to its YTE-engineered Fc region, and its PROVENT Phase III trial reported a 77% reduction in symptomatic COVID-19 at 28 days and 83% at 6 months, supported by neutralization potency with IC50 values as low as 13.7 ng/mL against the ancestral SARS-CoV-2 strain.
By Application
Therapeutics account for the dominant application segment with an estimated 62–65% share, as neutralizing antibodies gain significant traction for acute treatment, post-exposure prophylaxis, and high-risk patient management. Diagnostics follow, supported by antibody-based rapid assays, advanced neutralization tests, and laboratory-developed testing solutions that require high-affinity antibody reagents. Research and development applications accelerate as biotechnology firms expand screening programs, structural-biology studies, and high-throughput antibody discovery platforms. Growth in this segment is reinforced by increased funding for virology research, development of variant-responsive antibodies, and integration of AI-driven antibody design systems.
Key Growth Drivers
Rapid Advancement in Antibody Engineering Technologies
The market grows strongly as antibody engineering technologies evolve toward higher affinity, improved neutralization potency, and broader epitope recognition. Advances in Fc engineering, structure-guided design, and optimized expression systems enable faster development of next-generation neutralizing antibodies with enhanced stability and reduced immunogenicity. Automated screening platforms and AI-driven predictive models accelerate candidate selection and reduce R&D timelines. These capabilities support expanded therapeutic pipelines, strengthen preclinical success rates, and attract sustained investments from biotechnology firms and government-funded infectious disease programs.
- For instance, Eli Lilly exemplifies this with its development of bamlanivimab (LY-CoV555) and etesevimab (LY-CoV016) for SARS-CoV-2 neutralization.
Rising Global Burden of Infectious Diseases and Variant Emergence
Increasing incidence of viral outbreaks and the persistence of high-burden diseases such as HIV, influenza, and hepatitis C significantly fuel market expansion. New viral mutations and frequent variant emergence intensify demand for neutralizing antibodies that retain broad protection while offering rapid therapeutic response. Public health agencies and international consortia continue to prioritize funding for antiviral drug development, pandemic preparedness, and immunotherapeutic research. This ecosystem supports accelerated clinical trials, emergency-use authorizations, and expansion of neutralizing antibody libraries for both emerging and re-emerging pathogens.
- For instance, DS-5670 recently showed in a Phase 3 booster trial that one dose yielded a geometric mean titer (GMT) of blood neutralizing antibodies against the omicron BA.5 subvariant that was non-inferior to the active comparator vaccine at four weeks after administration.
Growing Adoption of Antibody-Based Therapeutics in High-Risk Patient Groups
Neutralizing antibodies gain traction as frontline or adjunct therapies for immunocompromised, elderly, and high-risk individuals who respond inadequately to vaccines. Their rapid onset of action, targeted mechanism, and ability to reduce viral load elevate clinical relevance across hospital and outpatient settings. Increasing integration of monoclonal antibody therapies into treatment guidelines for respiratory and blood-borne viral infections strengthens adoption. Expanded insurance reimbursement, improved manufacturing scalability, and greater clinical evidence supporting early-stage intervention further accelerate uptake across developed and emerging markets.
Key Trends & Opportunities
Expansion of Broadly Neutralizing Antibodies and Multi-Specific Platforms
A major trend centers on the development of broadly neutralizing antibodies and multi-specific constructs capable of targeting multiple epitopes simultaneously. These platforms offer resilience against viral escape and demonstrate enhanced neutralization breadth across variants. Opportunities emerge as biotech firms explore trispecific, bispecific, and combination-antibody formats, supported by structural biology insights and next-generation sequencing tools. Growing interest in pan-virus antibody candidates incentivizes strategic partnerships and cross-pathogen R&D programs aligned with global pandemic-preparedness strategies.
- For instance, (GSK4182136) has shown potent live-virus neutralization in preclinical assays, binding to a conserved epitope on the SARS-CoV-2 spike protein and maintaining neutralizing activity in pseudovirus tests against multiple variants.
Increasing Use of AI and High-Throughput Screening for Antibody Discovery
AI-assisted modeling, machine-learning–guided epitope prediction, and high-throughput microfluidic screening redefine antibody discovery processes. These tools improve candidate accuracy, shorten development timelines, and enhance prediction of cross-reactive neutralization profiles. Pharma and biotech companies increasingly invest in digital discovery platforms and automated cell-line development systems to expand antibody libraries. The trend creates opportunities for scalable, fast-response programs capable of addressing emerging pathogens within compressed development windows, strengthening industry readiness for future outbreaks.
- For instance, JNJ‑79635322 (JNJ-5322). In a Phase 1 trial of 36 patients with relapsed or refractory multiple myeloma treated at the recommended Phase 2 dose, JNJ-5322 achieved an overall response rate (ORR) of 86.1%, and in 27 patients naïve to BCMA and GPRC5D–directed therapies the ORR reached 100%.
Growth in Diagnostic and Surveillance Applications
Neutralizing antibodies play a growing role in diagnostic assays designed for variant detection, immune-response monitoring, and viral neutralization testing. Demand rises for high-affinity antibodies suitable for rapid tests, pseudovirus neutralization platforms, and laboratory-developed confirmatory assays. Opportunities emerge as global surveillance systems expand, requiring more precise reagents to track immune escape and monitor population-level immunity. This trend supports a broader shift toward integrated diagnostics-therapeutics models and strengthens collaboration between diagnostic developers and antibody manufacturers.
Key Challenges
High Production Costs and Complex Manufacturing Requirements
The market faces limitations due to high manufacturing costs, stringent purification requirements, and reliance on advanced bioreactor infrastructure. Producing consistent, high-potency neutralizing antibodies requires tight process control, increasing operational expenditure for both small and large manufacturers. Supply-chain constraints for critical raw materials and sensitivity to scale-up inefficiencies further elevate production challenges. These cost pressures reduce accessibility in low-resource regions and challenge broad adoption without supportive reimbursement frameworks or government procurement programs.
Risk of Viral Escape and Limited Long-Term Efficacy
A persistent challenge arises from viral mutations that diminish the long-term efficacy of existing neutralizing antibody therapies. Rapid antigenic drift, recombination events, and emergence of immune-evasive variants reduce neutralization potency, requiring continuous reformulation of antibody candidates. This dynamic environment increases R&D complexity and can shorten commercial lifecycles. Maintaining clinical relevance demands ongoing surveillance, accelerated redesign platforms, and multi-epitope targeting strategies that can withstand evolutionary pressure and reduce the likelihood of therapeutic resistance.
Regional Analysis
North America
North America leads the Neutralizing Antibody Market with an estimated 38–40% share, driven by strong biopharmaceutical infrastructure, rapid adoption of antibody-based therapeutics, and extensive funding for infectious disease research. The region benefits from advanced clinical trial networks, high diagnostic penetration, and consistent government support for pandemic-preparedness programs. Major companies expand antibody discovery pipelines through AI-driven platforms and large-scale bioreactor systems, strengthening production capabilities. Robust healthcare expenditure, high awareness of immunotherapeutic applications, and active incorporation of neutralizing antibodies into treatment guidelines further reinforce the region’s dominant position in global market growth.
Europe
Europe holds approximately 28–30% market share, supported by strong R&D intensity, advanced biotechnology ecosystems, and rising investments in antiviral immunotherapies. Countries such as Germany, the U.K., and France drive innovation through public–private research partnerships and growing adoption of monoclonal antibody therapies in infectious disease management. Regulatory frameworks that emphasize safety and accelerated approval for high-need therapeutics help expand market penetration. Increasing focus on cross-border surveillance, early pathogen detection, and development of variant-resistant neutralizing antibodies continues to strengthen Europe’s strategic role in shaping clinical and commercial advancements across the global market.
Asia-Pacific
Asia-Pacific accounts for an estimated 22–24% share, propelled by expanding biotechnology hubs, rising incidence of infectious diseases, and improving access to advanced therapeutic platforms. China, Japan, South Korea, and India enhance market growth through increased investments in antibody engineering, biomanufacturing capacity, and academic–industry collaborations. Growing clinical trial participation and heightened government priorities around outbreak preparedness support broader adoption of neutralizing antibodies. Improved regulatory harmonization and rapid expansion of CRO-led research further elevate the region’s competitiveness, positioning Asia-Pacific as one of the fastest-growing markets with strong long-term development potential.
Latin America
Latin America captures around 6–7% market share, supported by rising awareness of monoclonal antibody–based treatments and growing national initiatives to strengthen infectious disease management. Brazil and Mexico lead regional demand with expanding diagnostic infrastructure, improved vaccine-response monitoring, and adoption of antibody technologies for high-risk populations. Limited biomanufacturing capacity and cost constraints temper growth, yet ongoing partnerships with global pharmaceutical companies help introduce advanced neutralizing antibody therapies. Increased investment in public health resilience, faster regulatory approvals for innovative biologics, and government-backed surveillance programs continue to support gradual but steady market expansion.
Middle East & Africa
The Middle East & Africa region holds an estimated 4–5% share, characterized by rising healthcare modernization efforts and increasing interest in antibody-based therapeutics for viral outbreaks. Gulf countries including the UAE and Saudi Arabia stimulate demand through enhanced clinical infrastructure, greater funding for biologics, and partnerships with global biotech firms. Broader adoption remains challenged by high treatment costs and limited local production capacity, particularly in Sub-Saharan Africa. However, emerging vaccination programs, surveillance initiatives, and improved diagnostic capabilities support incremental growth, gradually expanding access to neutralizing antibodies across priority infectious disease applications.
Market Segmentations:
By Antibody Type:
- Monoclonal Antibodies
- Polyclonal Antibodies
By Target Virus:
- HIV
- Influenza
By Application:
- Therapeutics
- Diagnostics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Neutralizing Antibody Market features a competitive landscape anchored by Abbott Laboratories, AstraZeneca plc, Pfizer Inc, Eli Lilly And Company, Daiichi Sankyo Company, Limited, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Amgen Inc., Novartis AG, and Merck & Co., Inc. the Neutralizing Antibody Market continues to strengthen as major biopharmaceutical companies expand their focus on advanced immunotherapies, variant-resistant antibody constructs, and rapid-response antiviral platforms. Manufacturers prioritize high-affinity monoclonal antibody development, multi-specific antibody engineering, and accelerated discovery pipelines supported by AI-driven epitope prediction and high-throughput screening systems. Strategic partnerships with biotechnology firms, research institutes, and government health agencies enhance clinical translation and enable faster progression from preclinical evaluation to regulatory approval. Companies also invest heavily in scalable bioreactor infrastructure and continuous manufacturing technologies, improving production efficiency and ensuring rapid supply availability during outbreak-driven demand surges.
Key Player Analysis
- Abbott Laboratories
- AstraZeneca plc
- Pfizer Inc
- Eli Lilly And Company
- Daiichi Sankyo Company, Limited
- Johnson & Johnson Services, Inc.
- GlaxoSmithKline plc
- Amgen Inc.
- Novartis AG
- Merck & Co., Inc.
Recent Developments
- In November 2024, BioNTech announced an agreement to acquire Biotheus, securing worldwide rights to their promising bispecific antibody BNT327 (targeting PD-L1 and VEGF-A) and expanding BioNTech's oncology pipeline, giving them access to Biotheus' antibody platform and manufacturing in China. The deal, completed in early 2025, involved cash and stock, with milestone payments, aiming to use BNT327 as a core treatment for various cancers.
- In February 2024, Biocytogen and Gilead Sciences announced a major agreement where Gilead gained access to Biocytogen's extensive human antibody library (from their RenMice platforms) for three years to discover and develop new antibody drugs, with options for global development, milestone payments, and royalties for Biocytogen, highlighting a key trend in the ADC (Antibody-Drug Conjugate) space.
- In November 2023, Almirall for moderate-to-severe atopic dermatitis (AD) in adults and adolescents (12+ years, 40kg+) eligible for systemic therapy, marking a significant step for this IL-13 inhibitor in Europe, with launches beginning in Germany
Report Coverage
The research report offers an in-depth analysis based on Antibody Type, Target Virus, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as neutralizing antibodies become central to next-generation antiviral and immunotherapy strategies.
- Developers will advance antibody engineering platforms to improve potency, stability, and manufacturability.
- Partnerships between biotech firms and vaccine manufacturers will accelerate rapid-response antibody programs.
- Broader clinical adoption will rise with growing evidence supporting long-term protection across multiple infectious diseases.
- Pipeline diversification will strengthen as companies target respiratory, vector-borne, and emerging pathogens.
- Manufacturing capacity will increase through greater investment in continuous and single-use bioprocessing systems.
- Regulatory pathways will streamline as agencies refine evaluation frameworks for fast-acting biologics.
- Real-world data integration will enhance post-market surveillance and guide precision immunotherapy development.
- Competitive differentiation will intensify as firms leverage AI-driven antibody discovery and structural prediction tools.
- Global access will improve as technology transfer and regional production enable broader availability in developing markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Advancement in Antibody Engineering Technologies
Innovations in Fc engineering, structure-guided design, and AI-driven discovery platforms are enabling the development of next-generation neutralizing antibodies with higher affinity, improved stability, and broader epitope recognition, accelerating clinical pipelines and market expansion.
Rising Global Burden of Infectious Diseases and Variant Emergence
Frequent outbreaks and the emergence of new viral variants, such as SARS-CoV-2 and its subtypes, are driving demand for neutralizing antibodies that can provide rapid, targeted therapeutic responses and maintain efficacy against evolving pathogens.
Growing Adoption in High-Risk Patient Groups
Neutralizing antibodies are increasingly used as frontline or adjunct therapies for immunocompromised, elderly, and high-risk populations who may not respond adequately to vaccines, supporting broader clinical adoption and market growth.
Expansion of Broadly Neutralizing and Multi-Specific Antibody Platforms
The development of broadly neutralizing and multi-specific antibodies capable of targeting multiple viral epitopes simultaneously is enhancing resilience against viral escape, attracting investment, and opening new therapeutic opportunities.
Integration of AI and High-Throughput Screening in Antibody Discovery
AI-assisted modeling and high-throughput screening technologies are streamlining the identification and optimization of potent neutralizing antibodies, reducing R&D timelines and increasing the pace of innovation in the market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Neutralizing Antibody Market?
At what Compound Annual Growth Rate is the Neutralizing Antibody Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Neutralizing Antibody Market?
What are some challenges faced by the Neutralizing Antibody Market?
Who are the major players in the Neutralizing Antibody Market?
Which segment is leading the market share?
Who are the leading companies in the Neutralizing Antibody Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Therapeutics
- 1.2.2 Diagnostics
- 1.2.3 Research & Development
- 1.3 By Target Virus
- 1.3.1 SARS-CoV-2
- 1.3.2 HIV
- 1.3.3 Influenza
- 1.3.4 Ebola
- 1.3.5 Zika
- 1.3.6 Hepatitis C
- 1.4 By Antibody Type
- 1.4.1 Monoclonal Antibodies
- 1.4.2 Polyclonal Antibodies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 232,470 million → 2032: USD 446,482.98 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Neutralizing Antibody Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Neutralizing Antibody Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Neutralizing Antibody Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Neutralizing Antibody Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Neutralizing Antibody Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Neutralizing Antibody Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Neutralizing Antibody Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Neutralizing Antibody Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 232,470 million → 2032: USD 446,482.98 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Neutralizing Antibody Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Therapeutics
- 12.3.7.2 Diagnostics
- 12.3.7.3 Research & Development
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Target Virus - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 SARS-CoV-2
- 12.4.7.2 HIV
- 12.4.7.3 Influenza
- 12.4.7.4 Ebola
- 12.4.7.5 Zika
- 12.4.7.6 Hepatitis C
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Antibody Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Monoclonal Antibodies
- 12.5.7.2 Polyclonal Antibodies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Neutralizing Antibody End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Neutralizing Antibody Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Neutralizing Antibody Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Neutralizing Antibody Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Regeneron Pharmaceuticals, Inc.
- 18.4 AstraZeneca PLC
- 18.5 Roche Holding AG
- 18.6 Eli Lilly and Company
- 18.7 Sanofi SA
- 18.8 GlaxoSmithKline plc
- 18.9 Merck & Co., Inc.
- 18.10 Johnson & Johnson
- 18.11 Abbott Laboratories
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

