
Market Overview
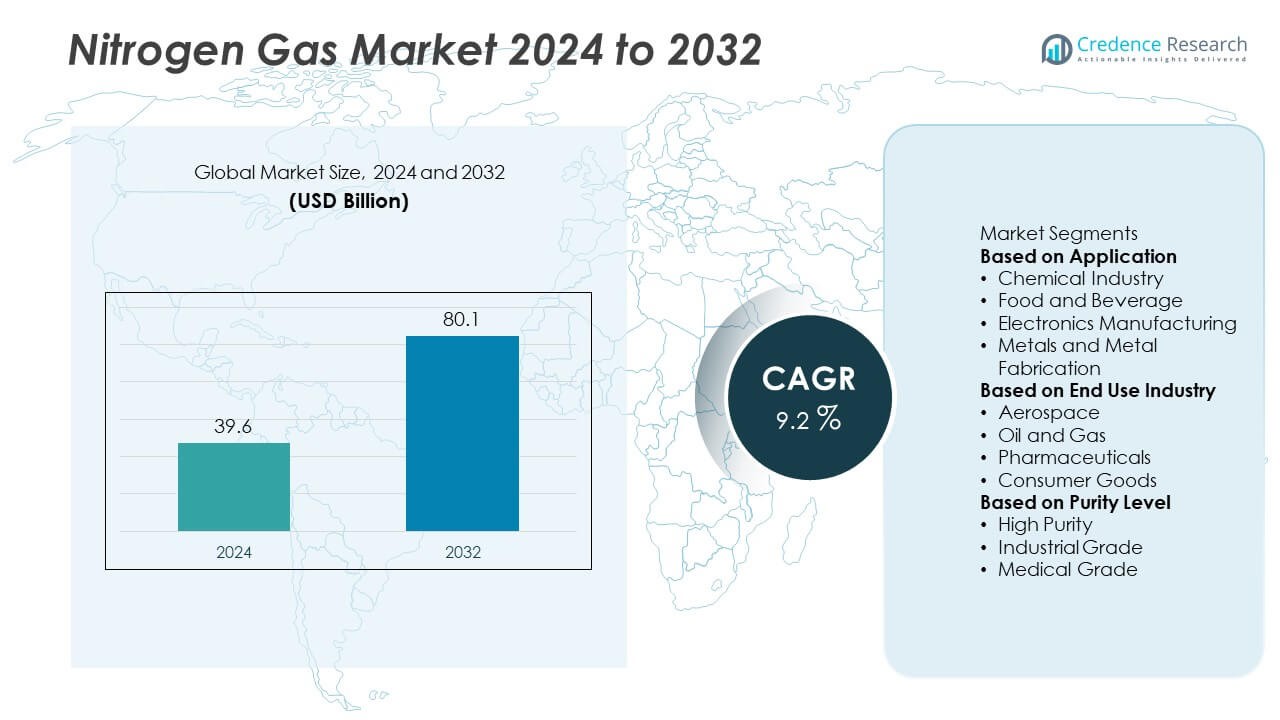
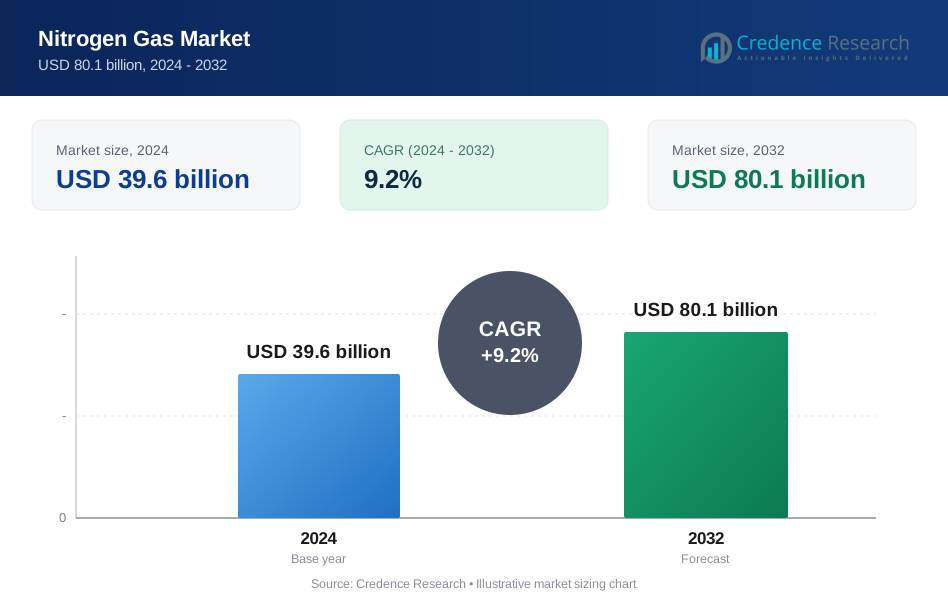
The Nitrogen Gas Market was valued at USD 39.6 billion in 2024 and is projected to reach USD 80.1 billion by 2032, expanding at a CAGR of 9.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Nitrogen Gas Market Size 2024 | USD 39.6 Billion |
| Nitrogen Gas Market, CAGR | 9.2% |
| Nitrogen Gas Market Size 2032 | USD 80.1 Billion |
The Nitrogen Gas Market grows through rising demand from food packaging, healthcare, electronics, and energy sectors. It benefits from strict quality standards in pharmaceuticals and biotechnology, where nitrogen ensures product stability and safe storage. Expanding semiconductor manufacturing drives adoption of ultra-high-purity nitrogen to prevent contamination.
The Nitrogen Gas Market demonstrates strong presence across all major regions, driven by diverse industrial and consumer applications. Asia-Pacific leads with significant demand from electronics, pharmaceuticals, and food processing industries in China, Japan, South Korea, and India. Europe advances with sustainability-focused adoption in food preservation, healthcare, and advanced manufacturing, supported by strict environmental regulations. North America shows steady growth through strong demand from biotechnology, energy, and packaged food sectors, while Latin America and the Middle East & Africa expand through oil, gas, and industrial applications. It benefits from modernization of infrastructure and adoption of on-site generation systems across these regions. Key players shaping the market include Linde, a global leader in industrial gases, Air Products and Chemicals, known for advanced on-site generation solutions, Yara International, a major supplier of nitrogen-based products, and Taiyo Nippon Sanso Corporation, which plays a crucial role in electronics and healthcare-focused nitrogen supply.
Market Insights
- The Nitrogen Gas Market was valued at USD 39.6 billion in 2024 and is expected to reach USD 80.1 billion by 2032, expanding at a CAGR of 9.2% during the forecast period.
- Rising demand from food packaging, pharmaceuticals, and biotechnology drives the market, with nitrogen ensuring longer shelf life, safe storage, and controlled atmospheres for sensitive products.
- Strong trends emerge in on-site nitrogen generation systems, ultra-high-purity nitrogen use in semiconductors, and adoption of sustainable production technologies powered by renewable energy sources.
- The market remains competitive with key players such as Linde, Air Products and Chemicals, Yara International, BASF, and Taiyo Nippon Sanso Corporation focusing on technological advancements and strategic partnerships.
- High production costs linked to energy-intensive processes and compliance with strict safety standards act as restraints, limiting rapid adoption in cost-sensitive industries and developing markets.
- Asia-Pacific leads due to strong demand from electronics, food, and healthcare, while Europe advances through sustainable packaging and pharmaceuticals. North America benefits from biotechnology and energy applications, with Latin America and Middle East & Africa expanding through oil, gas, and industrial sectors.
- Growing opportunities arise from healthcare expansion, semiconductor production, and adoption of eco-friendly nitrogen systems, positioning nitrogen gas as a critical enabler of innovation, safety, and efficiency across industries worldwide.
Market Drivers
Rising Demand from Food and Beverage Industry
The Nitrogen Gas Market benefits from strong demand in the food and beverage sector. Nitrogen extends shelf life by displacing oxygen and preventing spoilage in packaged goods. It is widely used in modified atmosphere packaging for meat, dairy, and ready-to-eat products. It ensures freshness and supports global supply chains. Growing demand for processed and convenience foods fuels wider application of nitrogen in packaging lines. It strengthens the market position of nitrogen as a critical enabler of food safety and quality.
- For instance, The CRYOLINE® CF is a cabinet freezer designed for batch freezing of smaller product quantities and is not an in-line system. A larger, continuous-belt unit like the CRYOLINE® CW or CRYOLINE® XF would be used for high-volume processing, as they are capable of rates over 500 kilograms per hour.
Expanding Applications in Healthcare and Pharmaceuticals
The Nitrogen Gas Market grows through rising usage in healthcare and pharmaceutical industries. Nitrogen provides an inert atmosphere for storing drugs, vaccines, and biological samples. It supports cryopreservation of cells and tissues in laboratories and medical research. It also plays a key role in drug manufacturing processes requiring controlled environments. Growing investments in biotechnology and personalized medicine increase its demand. It reinforces nitrogen’s value in ensuring quality and stability of sensitive medical products.
- For instance, Air Products and Chemicals supplied liquid nitrogen systems and specialized freezers for vaccine storage during the COVID-19 distribution phase. Storage units maintained ultra-cold temperatures, with some holding temperatures as low as -80°C to preserve the biological integrity of mRNA vaccines like those from Pfizer-BioNTech.
Increasing Use in Electronics and Semiconductor Manufacturing
The Nitrogen Gas Market expands with the growth of electronics and semiconductor manufacturing. Nitrogen offers a controlled environment that reduces oxidation during chip fabrication. It supports soldering, reflow processes, and cleaning of sensitive components. It ensures reliability and performance of microchips in advanced devices. Growing production of smartphones, electric vehicles, and consumer electronics drives demand for high-purity nitrogen. It highlights the importance of nitrogen in sustaining innovation across technology-driven sectors.
Rising Demand in Oil, Gas, and Industrial Applications
The Nitrogen Gas Market gains momentum from its use in oil, gas, and broader industrial applications. Nitrogen is applied in enhanced oil recovery, pressure maintenance, and pipeline purging. It also provides inerting and blanketing solutions in chemical manufacturing and metal processing. It enhances safety by reducing fire and explosion risks in hazardous environments. Expanding energy exploration projects and industrial operations sustain steady demand. It underlines nitrogen’s critical role in supporting large-scale industrial efficiency and safety.
Market Trends
Growing Shift Toward On-Site Nitrogen Generation Systems
The Nitrogen Gas Market shows a rising preference for on-site generation systems over bulk supply. Industries adopt membrane and pressure swing adsorption technologies to produce nitrogen directly at facilities. It reduces reliance on external suppliers and ensures continuous availability. On-site systems also lower operational costs and enhance supply chain efficiency. Growing demand from food packaging, electronics, and chemical plants accelerates this trend. It positions localized generation as a strategic solution for industries requiring high-purity nitrogen.
- For instance, Parker Hannifin offers several NITROSource on-site nitrogen generator systems, including the advanced NITROSource Plus, that can produce ultra-high purity nitrogen up to 99.999% or even 99.9995%. While the systems are modular and can be combined for very high output, a single generator's maximum flow rate varies greatly depending on the required purity level.
Increasing Role of High-Purity Nitrogen in Advanced Manufacturing
The Nitrogen Gas Market benefits from the expanding use of ultra-high-purity nitrogen in precision manufacturing. Semiconductor, pharmaceutical, and aerospace sectors require nitrogen with purity levels exceeding 99.999%. It prevents contamination, oxidation, and unwanted reactions in sensitive production processes. Growing adoption of nanotechnology and miniaturized components strengthens the requirement for ultra-pure gases. It highlights nitrogen’s role in safeguarding product integrity in high-tech industries. Rising investment in advanced electronics and cleanroom operations fuels this trend further.
- For instance, Taiyo Nippon Sanso supplies ultra-high-purity nitrogen with 99.9999% purity levels to Japanese semiconductor fabs, supporting advanced lithography and chip fabrication processes requiring contamination-free environments.
Integration of Digital Monitoring and Smart Gas Management
The Nitrogen Gas Market evolves with the adoption of digital monitoring systems for gas production and distribution. Smart sensors and IoT platforms enable real-time tracking of flow rates, purity, and pressure. It ensures process reliability and prevents costly downtime in industrial operations. Remote monitoring also allows predictive maintenance and optimized energy consumption. Industries benefit from greater efficiency and improved compliance with safety standards. It reflects a shift toward intelligent gas management solutions that enhance operational resilience.
Growing Sustainability Focus Across End-Use Industries
The Nitrogen Gas Market aligns with global sustainability goals through energy-efficient production methods. Companies invest in eco-friendly nitrogen generation units that reduce carbon footprints. It supports industries aiming to balance productivity with environmental responsibility. Adoption of renewable energy sources to power gas production units is also increasing. Food, healthcare, and electronics industries emphasize nitrogen’s role in reducing waste and improving safety. It underscores how sustainability remains central to long-term market expansion strategies.
Market Challenges Analysis
High Production and Operational Costs
The Nitrogen Gas Market faces challenges from high production and operational costs linked to energy-intensive processes. Air separation units and cryogenic distillation systems require significant capital investment. It increases the financial burden on small and medium-scale industries with limited budgets. Rising electricity prices further add pressure, making nitrogen production less cost-effective in some regions. Maintenance of generation equipment and supply chain logistics also contribute to higher expenses. It limits broader adoption in industries where cost sensitivity remains a key factor.
Regulatory Compliance and Safety Concerns
The Nitrogen Gas Market also confronts strict regulatory requirements and safety concerns. Nitrogen is inert but poses asphyxiation risks in confined environments, requiring specialized handling protocols. It compels industries to invest in safety equipment and training, raising operational costs. Compliance with environmental regulations on gas emissions during production adds complexity for manufacturers. Variations in regional standards make it difficult for global suppliers to streamline processes. It creates barriers for expansion and slows adoption in markets with evolving safety frameworks.
Market Opportunities
Expansion in Healthcare and Biotechnology Applications
The Nitrogen Gas Market presents strong opportunities through rising demand in healthcare and biotechnology. Cryopreservation of cells, tissues, and reproductive materials requires consistent nitrogen supply to maintain ultra-low temperatures. It supports pharmaceutical manufacturing, where nitrogen provides controlled atmospheres for drug formulation and storage. Growing investments in gene therapy and advanced biologics increase its role in laboratory and clinical research. It also enhances vaccine preservation, strengthening cold chain infrastructure worldwide. The rapid expansion of healthcare and biotech industries opens significant growth avenues for nitrogen suppliers.
Adoption of On-Site Generation and Sustainable Solutions
The Nitrogen Gas Market gains opportunities from adoption of on-site generation systems and energy-efficient technologies. On-site production reduces dependency on external suppliers and ensures continuous availability for industries with high nitrogen needs. It enables cost savings and offers flexibility in managing gas purity and volume. The push for sustainability creates demand for eco-friendly nitrogen systems powered by renewable energy sources. It supports industries such as food packaging, electronics, and chemicals in meeting green production targets. Growing adoption of sustainable gas solutions positions nitrogen as a critical enabler of industrial innovation and efficiency.
Market Segmentation Analysis:
By Application
The Nitrogen Gas Market is segmented by application into food packaging, medical, electronics, chemicals, and oil and gas. Food packaging dominates due to nitrogen’s ability to displace oxygen and extend product shelf life. It is widely applied in modified atmosphere packaging for meat, dairy, and snacks. Medical applications include cryopreservation and controlled atmospheres for drug storage and manufacturing. Electronics manufacturing relies on nitrogen for soldering, reflow, and oxidation prevention in semiconductor production. In oil and gas, nitrogen supports pressure maintenance, well stimulation, and pipeline purging. It shows growing use across diverse applications, reflecting its role as a versatile industrial gas.
- For instance, Air Products and Chemicals supplies over 1,500 nitrogen generation systems worldwide, including units capable of delivering 10,000 Nm³/hour to support oilfield operations and semiconductor manufacturing facilities.
By End Use Industry
The Nitrogen Gas Market serves end use industries such as food and beverage, healthcare, electronics, chemicals, and energy. The food and beverage sector accounts for significant demand due to increased consumption of packaged and processed foods. Healthcare relies on nitrogen for biological storage, cryogenics, and pharmaceutical processes. Electronics manufacturers require high-purity nitrogen for cleanroom operations and advanced chip fabrication. In chemicals, nitrogen ensures inert conditions in reactors and storage facilities. Energy and oil sectors adopt nitrogen for enhanced oil recovery and fire prevention. It highlights nitrogen’s cross-industry relevance, supporting both consumer-driven and industrial markets.
- For instance, Linde does operate multiple air separation units in Germany, supplying various industries, including healthcare, with gases like high-purity oxygen and nitrogen. While customized Linde plants can produce between 1,000 and 5,500 tons of oxygen per day, a 2,000 tpd capacity is a significant, but not unprecedented, amount for a single plant, typically serving very large industrial customers.
By Purity Level
The Nitrogen Gas Market is segmented by purity level into high purity, ultra-high purity, and standard grade. High-purity nitrogen is widely used in electronics, healthcare, and laboratories where contamination risks must be minimized. Ultra-high-purity nitrogen, exceeding 99.999% purity, is critical in semiconductor manufacturing and advanced pharmaceuticals. Standard-grade nitrogen finds application in industries such as food packaging, welding, and metal fabrication. It ensures cost-effective solutions for processes that do not require extremely high specifications. The growing demand for ultra-high-purity nitrogen reflects advancements in technology-intensive industries. It underscores how different purity levels align with diverse operational needs across sectors.
Segments:
Based on Application
- Chemical Industry
- Food and Beverage
- Electronics Manufacturing
- Metals and Metal Fabrication
Based on End Use Industry
- Aerospace
- Oil and Gas
- Pharmaceuticals
- Consumer Goods
Based on Purity Level
- High Purity
- Industrial Grade
- Medical Grade
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds around 23% share of the Nitrogen Gas Market, supported by strong industrial, healthcare, and food packaging demand. The United States dominates the region due to its large-scale pharmaceutical production, advanced biotechnology research, and expanding frozen and packaged food industry. Canada contributes with rising investments in healthcare infrastructure and industrial manufacturing, while Mexico strengthens its position through a growing electronics and automotive base. It benefits from mature supply networks and wide adoption of on-site nitrogen generation technologies across industries. The energy sector in the U.S. also drives nitrogen demand for oil recovery and pipeline purging. Regional suppliers focus on developing high-purity and ultra-high-purity nitrogen systems to meet the needs of semiconductor and biotechnology industries.
Europe
Europe accounts for about 27% of the Nitrogen Gas Market, with Germany, France, and the UK leading adoption. Strong emphasis on food preservation and packaging supports consistent nitrogen use across the region. Healthcare and pharmaceutical industries also create robust demand, particularly in vaccine production and biologics storage. It sees rapid adoption of eco-friendly nitrogen generation systems aligned with European Union sustainability goals. Electronics and semiconductor growth in countries such as Germany and the Netherlands further push the need for ultra-high-purity nitrogen. Energy companies across Norway and the UK offshore oil and gas fields also drive demand for nitrogen applications in exploration and safety. The presence of multinational industrial gas companies ensures competitive innovation and steady supply.
Asia-Pacific
Asia-Pacific dominates the Nitrogen Gas Market with nearly 35% share, led by China, Japan, South Korea, and India. China drives significant demand from its expanding electronics, automotive, and food processing sectors. Japan and South Korea rely heavily on ultra-high-purity nitrogen for semiconductor and advanced electronics production. India shows rising demand from pharmaceuticals, biotechnology, and packaged foods, supported by rapid urbanization and healthcare growth. It also benefits from strong investment in energy and petrochemical industries across the region. Increasing preference for on-site nitrogen generation systems reduces operational costs and ensures consistent supply for high-volume industries. Asia-Pacific’s dominance is reinforced by large-scale industrialization and continuous expansion of high-tech sectors.
Latin America
Latin America represents around 8% of the Nitrogen Gas Market, with Brazil and Mexico as the largest contributors. Brazil’s strong food and beverage industry fuels nitrogen adoption in packaging and preservation. Mexico shows growing usage in electronics, automotive, and healthcare applications. It faces infrastructure challenges but steadily embraces on-site generation systems to improve reliability and reduce costs. Oil and gas exploration in Brazil and Mexico also drives nitrogen demand for enhanced recovery and safety processes. Governments encourage modernization across industrial operations, supporting gradual adoption of advanced nitrogen technologies. Latin America’s position continues to strengthen through international collaborations and regional investment in manufacturing capabilities.
Middle East & Africa
The Middle East & Africa account for approximately 7% of the Nitrogen Gas Market, supported by energy, healthcare, and industrial applications. The Middle East shows high demand in oil and gas projects where nitrogen is critical for well stimulation, pipeline purging, and safety. Africa contributes with rising demand from food preservation, healthcare, and chemical industries, particularly in countries like South Africa and Nigeria. It also benefits from growing infrastructure investments and regional industrialization efforts. However, limited technological infrastructure restricts faster adoption of high-purity nitrogen applications. Suppliers work with local governments and companies to expand access to modern nitrogen generation solutions. The region continues to show steady growth potential through expansion in both energy and consumer industries.
Key Player Analysis
- CF Industries
- NOVA Chemicals
- Linde
- Taiyo Nippon Sanso Corporation
- BASF
- Yara International
- Nippon Gases
- Gases Specialty
- Air Products and Chemicals
- Showa Denko
Competitive Analysis
The competitive landscape of the Nitrogen Gas Market features leading players such as Linde, Air Products and Chemicals, Yara International, BASF, Taiyo Nippon Sanso Corporation, Nippon Gases, Showa Denko, NOVA Chemicals, CF Industries, and Gases Specialty. These companies focus on strengthening their portfolios through technological innovation, large-scale production facilities, and global distribution networks. They emphasize on-site nitrogen generation systems, ultra-high-purity nitrogen supply, and energy-efficient production technologies to meet growing demand across food packaging, healthcare, and semiconductor industries. Strategic partnerships, acquisitions, and joint ventures are key approaches used to expand regional presence and gain competitive advantage. Sustainability is also central, with players investing in renewable-powered nitrogen plants and carbon-reduction initiatives. Competitive differentiation is shaped by product quality, purity levels, and integration of digital monitoring solutions to improve supply reliability. Intense rivalry pushes each company to enhance operational efficiency and target emerging opportunities in Asia-Pacific, Europe, and North America, reinforcing nitrogen’s role as an essential industrial gas across diverse sectors.
Recent Developments
- In July 2025, CF Industries began operations at its Donaldsonville Complex CO₂ dehydration and compression unit, enabling permanent sequestration of up to 2 million metric tons of CO₂ per year.
- In July 2025, Linde plans construction of a new ASU in Brownsville, Texas, supplying liquid nitrogen, oxygen, and argon, expected operational in Q1 2026 to support aerospace applications.
- In June 2025, Linde signed a long-term agreement to supply nitrogen and oxygen to the massive Blue Point low‑carbon ammonia facility in Louisiana.
- In February 2025, Air Products exited three U.S.-based projects and recorded a pre-tax charge not to exceed USD 3.1 billion.
Report Coverage
The research report offers an in-depth analysis based on Application, End Use Industry, Purity Level and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Nitrogen supply integration with renewable-powered air separation units will expand in high-demand regions.
- On-site nitrogen generator deployment will increase across food packaging and electronics plants.
- Suppliers will focus on ultra-high-purity nitrogen to support semiconductor and biotech sectors.
- Modular and compact generation systems will gain traction in remote or flexible industrial setups.
- Digital monitoring and IoT-based control will become standard in nitrogen generation systems.
- Clean ammonia and green nitrogen derived from renewable hydrogen will enter fertilizer and industrial gas segments.
- Emerging economies will drive localized nitrogen production to support expanding manufacturing and packaging industries.
- Collaboration between gas producers and renewable energy providers will enhance carbon-efficient production.
- Asia-Pacific will strengthen its leadership through infrastructure investments and on-site generation uptake.
- Growth of cryogenic air separation unit markets will support scalable nitrogen supply in heavy industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Food Packaging and Preservation
Nitrogen gas is widely used in modified atmosphere packaging to extend shelf life and maintain freshness of perishable foods, supporting the global growth of processed and convenience food markets.
Growth in Healthcare and Pharmaceutical Applications
The need for inert atmospheres in drug manufacturing, cryopreservation, and vaccine storage is driving increased nitrogen demand, especially as biotechnology and personalized medicine investments rise.
Rising Demand for Ultra-High-Purity Nitrogen in Electronics
Semiconductor and advanced electronics manufacturing require ultra-high-purity nitrogen to prevent contamination and oxidation, with Asia-Pacific leading demand due to its robust electronics sector.
Adoption of On-Site Nitrogen Generation Systems
Industries are increasingly installing on-site nitrogen generators to ensure continuous supply, reduce operational costs, and improve supply chain efficiency, particularly in food, electronics, and chemical plants.
Industrial and Energy Sector Applications
Nitrogen is essential for enhanced oil recovery, pipeline purging, and inerting in hazardous environments, supporting safety and efficiency in oil, gas, and heavy industrial operations worldwide.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Nitrogen Gas, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Nitrogen Gas market projected to grow between 2025 and 2032?
Which Nitrogen Gas market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Nitrogen Gas market?
Who are the leading companies in the Nitrogen Gas market?
Which region commanded the largest share of the Nitrogen Gas market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Food Packaging
- 1.2.2 Medical
- 1.2.3 Electronics Manufacturing
- 1.2.4 Chemical Industry
- 1.2.5 Oil and Gas
- 1.2.6 Metals and Metal Fabrication
- 1.3 By Purity Level
- 1.3.1 High Purity
- 1.3.2 Ultra-High Purity
- 1.3.3 Standard/Industrial Grade
- 1.3.4 Medical Grade
- 1.4 By End Use Industry
- 1.4.1 Food and Beverage
- 1.4.2 Healthcare
- 1.4.3 Electronics
- 1.4.4 Chemicals
- 1.4.5 Energy
- 1.4.6 Aerospace
- 1.4.7 Consumer Goods
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 39.6 billion → 2032: USD 80.1 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Nitrogen Gas Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Nitrogen Gas Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Nitrogen Gas Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Nitrogen Gas Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Nitrogen Gas Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Nitrogen Gas Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Nitrogen Gas Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Nitrogen Gas Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 39.6 billion → 2032: USD 80.1 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Nitrogen Gas Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food Packaging
- 12.3.7.2 Medical
- 12.3.7.3 Electronics Manufacturing
- 12.3.7.4 Chemical Industry
- 12.3.7.5 Oil and Gas
- 12.3.7.6 Metals and Metal Fabrication
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Purity Level - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 High Purity
- 12.4.7.2 Ultra-High Purity
- 12.4.7.3 Standard/Industrial Grade
- 12.4.7.4 Medical Grade
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverage
- 12.5.7.2 Healthcare
- 12.5.7.3 Electronics
- 12.5.7.4 Chemicals
- 12.5.7.5 Energy
- 12.5.7.6 Aerospace
- 12.5.7.7 Consumer Goods
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Nitrogen Gas End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Nitrogen Gas Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Nitrogen Gas Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Nitrogen Gas Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Linde
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Air Products and Chemicals
- 18.4 Yara International
- 18.5 BASF
- 18.6 Taiyo Nippon Sanso Corporation
- 18.7 Nippon Gases
- 18.8 Showa Denko
- 18.9 NOVA Chemicals
- 18.10 CF Industries
- 18.11 Gases Specialty
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
