
Market Overview
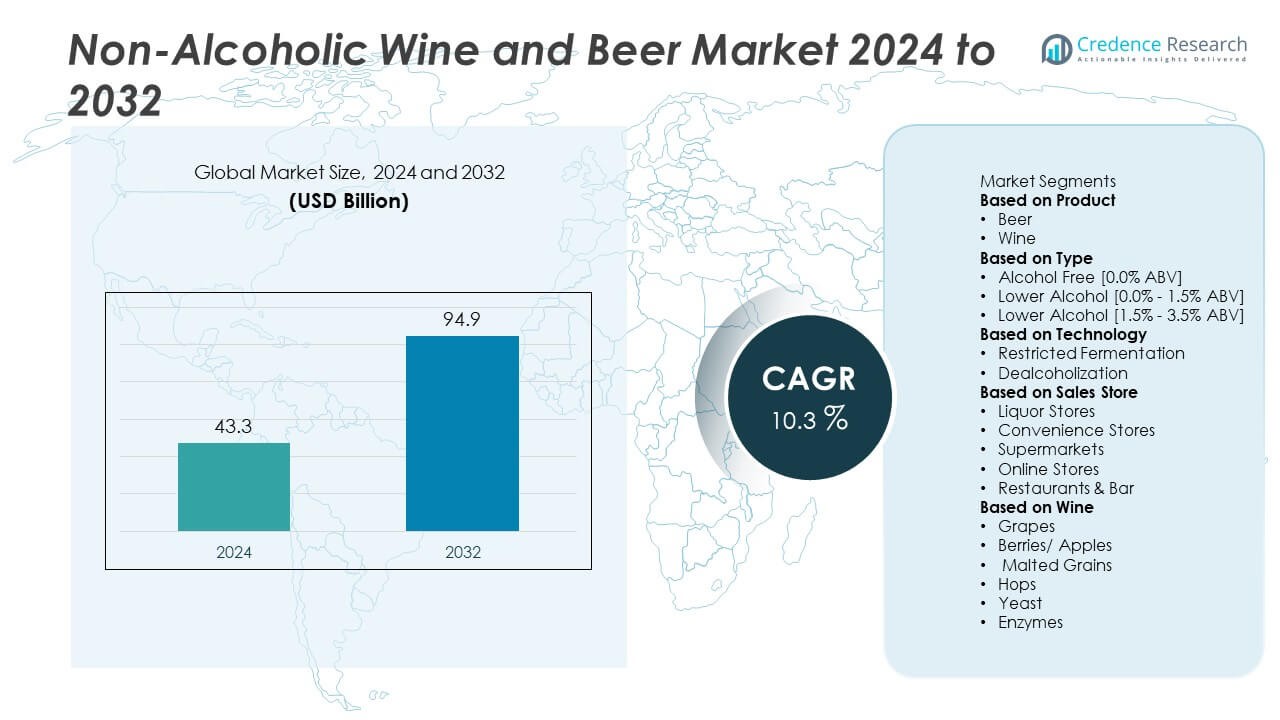
The Non-Alcoholic Wine and Beer Market size was valued at USD 43.3 billion in 2024 and is projected to reach USD 94.9 billion by 2032, growing at a CAGR of 10.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Non-Alcoholic Wine and Beer Market Size 2024 | USD 43.3 Billion |
| Non-Alcoholic Wine and Beer Market, CAGR | 10.3% |
| Non-Alcoholic Wine and Beer Market Size 2032 | USD 94.9 Billion |
The Non-Alcoholic Wine and Beer Market grows steadily, driven by rising health awareness, stricter alcohol regulations, and increasing demand for mindful drinking alternatives. Consumers adopt alcohol-free beverages to maintain wellness while enjoying social experiences, boosting preference for low-calorie and natural formulations.
The Non-Alcoholic Wine and Beer Market demonstrates strong regional diversity, with Europe leading due to a long-standing culture of alcohol-free brewing and innovation, while North America shows rapid growth driven by health-conscious consumers and robust retail networks. Asia-Pacific emerges as a dynamic region, fueled by rising disposable incomes, urbanization, and younger demographics embracing mindful consumption. The Middle East & Africa also reflect significant potential, supported by cultural and religious acceptance of non-alcoholic beverages, while Latin America steadily expands through growing lifestyle awareness. Key players shape this global landscape by combining innovation, distribution, and branding. Heineken N.V. invests in premium alcohol-free variants with global reach, while Anheuser-Busch InBev leverages extensive brewing expertise to diversify product portfolios. Carlsberg expands its footprint through craft-inspired options, and Suntory Beer strengthens market penetration across Asia with tailored non-alcoholic solutions. Collectively, these players drive product quality, consumer trust, and widespread adoption.
Market Insights
- The Non-Alcoholic Wine and Beer Market was valued at USD 43.3 billion in 2024 and is projected to reach USD 94.9 billion by 2032, expanding at a CAGR of 10.3% during the forecast period.
- Rising health awareness, stricter alcohol regulations, and shifting consumer behavior toward mindful drinking act as primary drivers that stimulate consistent demand for alcohol-free beverages.
- Key trends include the integration of functional ingredients, premiumization, and the use of advanced brewing technologies that improve taste profiles and expand product acceptance among health-conscious and younger demographics.
- Competitive intensity is high, with global leaders such as Heineken N.V., Anheuser-Busch InBev, Carlsberg, and Suntory Beer investing in innovation, premium variants, and distribution expansion, while niche players like Big Drop Brewing and Pierre Chavin focus on differentiation and craft-style offerings.
- Major restraints include high production costs, limited ability to fully replicate traditional taste, regulatory complexities across regions, and persistent consumer perceptions that alcohol-free products lack authenticity.
- Regional dynamics show Europe leading due to strong brewery traditions, North America advancing with retail and e-commerce adoption, Asia-Pacific emerging as the fastest-growing market, the Middle East & Africa benefiting from cultural acceptance, and Latin America expanding through urban demand.
- Strategic opportunities lie in innovation, partnerships with hospitality and retail networks, and expansion into emerging economies, where rising disposable incomes and changing lifestyles create a strong foundation for long-term market penetration and sustained growth.
Market Drivers
Rising Health Awareness and Shift Toward Low-Alcohol Alternatives
The Non-Alcoholic Wine and Beer Market benefits from rising global awareness about the negative health effects of alcohol consumption. Consumers seek alternatives that support wellness without sacrificing social experiences. The growing prevalence of lifestyle-related diseases such as liver disorders and obesity strengthens the demand for alcohol-free beverages. It addresses this trend by offering products that replicate traditional flavors while reducing health risks. Public health campaigns and stricter regulations on alcohol also reinforce this shift. A broader acceptance of mindful drinking practices creates a steady demand base across diverse demographics.
- For instance, in 2023, Heineken's non-alcoholic portfolio showed mixed results, with some markets experiencing strong growth and others facing declines. While the exact total sales volume for Heineken 0.0 in 2023 was not publicly disclosed, Heineken 0.0 was distributed in over 110 global markets, continuing its expansion. This growth, seen in markets like Brazil and the USA, reflects a broader consumer trend toward low and no-alcohol options.
Expanding Product Innovation and Premiumization
Continuous advancements in brewing and fermentation techniques accelerate product adoption in the Non-Alcoholic Wine and Beer Market. Brands introduce beverages with improved taste profiles, natural ingredients, and enhanced aromas to attract quality-conscious buyers. It capitalizes on premium positioning by offering artisanal and craft-style options that appeal to urban and millennial consumers. Companies also expand their portfolios to cover varied consumer preferences, from traditional lagers to sparkling grape-based products. This innovation-driven environment elevates consumer satisfaction and increases brand loyalty. The combination of authenticity and variety sets a strong foundation for sustained growth.
Growing Influence of Younger Demographics and Lifestyle Changes
The Non-Alcoholic Wine and Beer Market experiences strong demand from younger consumers who prioritize wellness and balance. Gen Z and millennials are more inclined to experiment with alcohol-free options that fit social occasions without compromising health goals. It aligns with evolving preferences that emphasize social inclusion while reducing alcohol dependency. The market benefits from cultural shifts where celebrations no longer require high-alcohol beverages to retain significance. Increased participation in “dry months” such as Dry January illustrates this behavioral change. Strong engagement from younger audiences ensures long-term consumption growth.
- For instance, Heineken reported that its Heineken 0.0 product grew by a low-teens percentage in the first half of 2022, with sales expanding in key markets like Brazil and Spain, underscoring the adoption of alcohol-free options.
Expanding Global Distribution Channels and Accessibility
The Non-Alcoholic Wine and Beer Market gains momentum through wider availability across retail, online, and hospitality platforms. Supermarkets, specialty stores, and e-commerce platforms enhance consumer access and visibility. It benefits from partnerships with restaurants, bars, and hotels that integrate alcohol-free beverages into their menus. The convenience of digital platforms also supports direct-to-consumer sales, reaching health-conscious buyers worldwide. Strong marketing strategies and branding campaigns increase awareness and trial rates. A diverse distribution network ensures consistent penetration into both developed and emerging regions, reinforcing market growth.
Market Trends
Rising Popularity of Functional and Wellness-Oriented Beverages
The Non-Alcoholic Wine and Beer Market embraces the trend of functional ingredients that extend beyond refreshment. Consumers increasingly prefer products infused with botanicals, vitamins, and adaptogens that align with wellness-focused lifestyles. It leverages this shift by offering beverages that combine taste with health benefits, appealing to fitness-conscious individuals. The rise of low-sugar and low-calorie formulations further drives product acceptance. Brands highlight clean labels and natural sourcing to strengthen credibility among discerning buyers. The integration of wellness attributes ensures broader appeal across global markets.
- For instance, Suntory launched its All-Free beer-like beverage in Japan in 2010. Since its launch, All-Free has gained significant popularity and is marketed as containing zero calories and zero sugar. The product helped establish Suntory as a leader in Japan's expanding market for non-alcoholic and health-oriented beverages, which is growing due to rising health consciousness and demographic shifts.
Technological Advancements in Brewing and Flavor Enhancement
The Non-Alcoholic Wine and Beer Market benefits from innovations that improve the sensory quality of alcohol-free products. Advanced dealcoholization processes allow beverages to retain authentic aromas and full-bodied taste. It gains traction through micro-brewing techniques and high-pressure fermentation methods that deliver consistency and flavor depth. Companies invest in research to replicate the complexity of traditional alcoholic beverages without compromising health standards. Such advancements increase consumer satisfaction and reduce barriers to adoption. The emphasis on technology-driven product development supports long-term competitiveness.
- For instance, For instance, Erdinger Weißbräu uses vacuum distillation technology in its Erdinger Weissbier Alkoholfrei. This process gently removes the alcohol while preserving the beer's traditional wheat flavor. The resulting beverage also has isotonic properties, meaning it allows for the rapid absorption of nutrients. Due to these characteristics, Erdinger Alkoholfrei is a popular recovery drink among athletes.
Sustainability and Eco-Friendly Packaging Solutions
The Non-Alcoholic Wine and Beer Market aligns with global sustainability initiatives by adopting environmentally responsible practices. Brands increasingly use recyclable materials, lightweight glass, and biodegradable packaging to reduce carbon footprints. It attracts eco-conscious consumers who prioritize sustainability in purchasing decisions. The shift toward renewable energy and water-efficient brewing processes reinforces brand reputation. Companies integrate ethical sourcing of ingredients to strengthen transparency and trust. Commitment to sustainability enhances both brand differentiation and market credibility.
Growing Acceptance Across Social and Cultural Platforms
The Non-Alcoholic Wine and Beer Market gains visibility in cultural and social settings that traditionally favored alcoholic beverages. Restaurants, bars, and event organizers integrate alcohol-free options into menus and celebrations. It benefits from rising popularity of mindful drinking movements that redefine social norms. Celebrity endorsements and marketing campaigns normalize alcohol-free consumption among wider audiences. Seasonal campaigns such as Dry January or Sober October reinforce market growth. Broader cultural acceptance ensures these beverages remain integral to lifestyle and social identity.
Market Challenges Analysis
High Production Costs and Limited Taste Replication
The Non-Alcoholic Wine and Beer Market faces significant challenges in maintaining authentic flavor profiles while removing alcohol. Advanced processes such as vacuum distillation and reverse osmosis increase production costs and limit scalability for smaller producers. It often struggles to match the sensory depth of traditional alcoholic beverages, leading to consumer hesitation in repeat purchases. The requirement for premium raw materials further raises expenses and narrows affordability in price-sensitive markets. Limited success in replicating aroma and texture can also reduce competitiveness against alcoholic alternatives. Brands continue to invest in innovation, yet consistent quality remains a pressing challenge.
Regulatory Barriers and Market Perception Issues
The Non-Alcoholic Wine and Beer Market must navigate complex regulations that vary across countries, creating barriers for global expansion. Labeling rules and alcohol thresholds often differ, complicating distribution and compliance. It also faces the challenge of changing consumer perceptions that link alcohol-free options with inferior taste or limited authenticity. Marketing campaigns need to educate buyers and reposition these beverages as premium lifestyle products. Strong competition from traditional alcoholic beverages further intensifies the struggle for visibility. Overcoming cultural bias and regulatory inconsistencies remains critical for broader market acceptance and long-term growth.
Market Opportunities
Expansion into Emerging Economies and Untapped Consumer Segments
The Non-Alcoholic Wine and Beer Market holds strong opportunities in emerging regions where rising disposable incomes and growing health awareness reshape consumption patterns. Rapid urbanization and expanding middle-class populations in Asia-Pacific, Latin America, and the Middle East create fertile ground for alcohol-free beverages. It benefits from governments promoting healthier lifestyles and regulating alcohol consumption more strictly. Untapped demographics, including younger consumers and women, represent a significant growth avenue. Cultural acceptance of non-alcoholic options also supports broader integration into traditional celebrations. Strategic entry into these markets ensures sustained global presence and revenue diversification.
Innovation in Product Diversification and Strategic Collaborations
The Non-Alcoholic Wine and Beer Market can strengthen its position by introducing diversified flavors, functional ingredients, and premium variants. Companies have the chance to differentiate through wellness-focused formulations that combine low-calorie content with natural additives. It can also leverage collaborations with hospitality, retail, and e-commerce platforms to increase visibility and accessibility. Partnerships with global food chains, sports events, and lifestyle brands open new channels for consumer engagement. Growing digital influence offers further opportunities through targeted online marketing and direct-to-consumer sales. Innovation-driven expansion creates long-term value and establishes stronger brand loyalty across regions.
Market Segmentation Analysis:
By Product
The Non-Alcoholic Wine and Beer Market is segmented into non-alcoholic wine and non-alcoholic beer, with beer accounting for a larger share due to its widespread cultural acceptance and established global demand. Non-alcoholic beer dominates consumption in Europe, North America, and Asia-Pacific, where breweries expand their portfolios with lagers, ales, and craft-inspired options. It appeals to younger consumers who seek healthier alternatives while maintaining the social aspects of drinking. Non-alcoholic wine shows strong growth potential as innovations improve taste and aroma retention, appealing to premium-oriented buyers. Sparkling variants also gain traction for their positioning in celebratory occasions. Both categories continue to evolve, driven by innovation and rising consumer awareness.
- For instance, In Germany, consumers drank 10.4 million hectoliters of alcohol-free beer in 2023, confirming a strong, growing market and significant brewery investment. The consumption figure is a key indicator of the industry's focus on this segment.
By Type
The market by type includes alcohol-free and low-alcohol variants, each catering to distinct consumer needs. Alcohol-free products with 0.0% ABV remain popular among health-conscious buyers and those avoiding alcohol for religious or lifestyle reasons. It benefits from stricter government regulations that promote safer consumption. Low-alcohol beverages, generally below 1.2% ABV, attract consumers who prefer reduced alcohol levels without fully eliminating it. These variants replicate traditional taste while offering a balanced choice for social occasions. The diversity within this segment ensures inclusivity for varied consumer groups. Strong demand from both categories drives steady market expansion.
By Technology
The Non-Alcoholic Wine and Beer Market leverages different production technologies, including dealcoholization and restricted fermentation. Dealcoholization techniques such as vacuum distillation, reverse osmosis, and membrane filtration dominate due to their ability to retain authentic flavors. It ensures higher product quality and supports premium positioning across developed markets. Restricted fermentation emerges as a cost-efficient method suitable for mass-market production, especially in emerging economies. Hybrid technologies that combine brewing precision with advanced filtration also expand adoption by addressing both taste and affordability. Continuous innovation in technology enhances product consistency and creates opportunities for global scalability.
- For instance, In July 2023, Anheuser-Busch InBev (AB InBev) announced a €31 million investment to upgrade its breweries in Belgium. This investment was aimed at expanding its non-alcoholic brewing and bottling capabilities and optimizing a new dealcoholization system. De-alcoholization is a primary method used to produce low- and no-alcohol beer.
Segments:
Based on Product
- Beer
- Wine
Based on Type
- Alcohol Free [0.0% ABV]
- Lower Alcohol [0.0% - 1.5% ABV]
- Lower Alcohol [1.5% - 3.5% ABV]
Based on Technology
- Restricted Fermentation
- Dealcoholization
Based on Sales Store
- Liquor Stores
- Convenience Stores
- Supermarkets
- Online Stores
- Restaurants & Bar
Based on Wine
- Grapes
- Berries/ Apples
- Malted Grains
- Hops
- Yeast
- Enzymes
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a significant share of the Non-Alcoholic Wine and Beer Market, accounting for around 32% of global revenue in 2024. The region benefits from rising health consciousness, growing popularity of mindful drinking, and strong marketing campaigns by established beverage companies. The United States leads the market with its robust demand for craft-style non-alcoholic beer and premium alcohol-free wines. Canada also contributes meaningfully, driven by government-led awareness programs on alcohol-related health risks. It thrives in North America due to the integration of non-alcoholic offerings in restaurants, bars, and social events, where inclusivity has become a key trend. Strong retail networks, e-commerce growth, and continuous product launches reinforce the region’s dominance.
Europe
Europe represents the largest share of the Non-Alcoholic Wine and Beer Market, contributing about 38% in 2024, supported by cultural acceptance of non-alcoholic beverages and strong brewery traditions. Germany leads with a long-standing history of alcohol-free beer production, followed by Spain, the United Kingdom, and France. The region benefits from consumers embracing low- or no-alcohol beverages as part of balanced lifestyles. It also receives support from strict regulations limiting alcohol marketing, which encourages consumers to explore safer alternatives. The demand for premium non-alcoholic wines has surged, particularly in France and Italy, where traditional wine consumption is deeply rooted. Continuous innovation by European brewers and winemakers secures the region’s leadership.
Asia-Pacific
Asia-Pacific emerges as the fastest-growing region, holding around 20% market share in 2024 and expected to expand rapidly during the forecast period. Rising disposable incomes, rapid urbanization, and cultural shifts toward healthier consumption patterns drive growth across China, Japan, India, and Australia. Japan leads with its established market for low- and no-alcohol beverages, while China shows increasing demand due to lifestyle changes among urban youth. It benefits from the strong presence of global breweries investing in local production facilities to tap into the expanding consumer base. E-commerce platforms and retail innovation enhance product accessibility, while growing social campaigns on health and fitness further stimulate adoption. Asia-Pacific is positioned to close the gap with Western markets over the coming years.
Middle East & Africa
The Middle East & Africa accounts for nearly 6% of the global Non-Alcoholic Wine and Beer Market in 2024, supported by cultural and religious factors that encourage alcohol-free consumption. Countries such as Saudi Arabia, the United Arab Emirates, and South Africa emerge as key markets with rising demand for premium alcohol-free beverages. It thrives in this region due to favorable acceptance in hospitality, tourism, and retail sectors, especially in the Gulf Cooperation Council (GCC) states. The growing expatriate population also boosts demand for diverse beverage options. However, limited local production and high import dependence remain challenges that shape pricing strategies. Expanding partnerships with international beverage companies are expected to enhance future market share.
Latin America
Latin America holds approximately 4% of the Non-Alcoholic Wine and Beer Market in 2024, with growth driven by urban centers in Brazil, Mexico, and Argentina. Rising awareness of health and wellness supports adoption, particularly among younger consumers seeking alternatives to traditional alcoholic beverages. It benefits from promotional campaigns linked to international lifestyle trends such as Dry January and sober living movements. Market penetration remains concentrated in urban areas due to limited distribution networks in rural zones. Partnerships between regional breweries and global players are expanding product availability. Although the market share is smaller compared to other regions, Latin America presents strong potential for long-term growth as consumer habits evolve.
Key Player Analysis
- Bernard Brewery
- Suntory Beer
- Big Drop Brewing
- Pierre Chavin
- Carlsberg
- Behnoush Iran
- Heineken N.V.
- Moscow Brewing Company
- Erdinger Weibbrau
- Anheuser-Bush InBev
Competitive Analysis
The competitive landscape of the Non-Alcoholic Wine and Beer Market is shaped by leading players including Heineken N.V., Anheuser-Busch InBev, Carlsberg, Suntory Beer, Bernard Brewery, Erdinger Weibbrau, Big Drop Brewing, Pierre Chavin, Moscow Brewing Company, and Behnoush Iran. These companies drive market momentum by focusing on innovation, product diversification, and premium positioning to meet the evolving preferences of health-conscious consumers. Global giants leverage their strong distribution networks, advanced brewing technologies, and extensive brand portfolios to maintain dominance, while regional and niche players differentiate through craft-inspired products, functional ingredients, and targeted consumer engagement. Strategic investments in dealcoholization processes and flavor enhancement technologies allow the market leaders to replicate authentic taste, improving adoption among traditional alcohol consumers. Sustainability practices such as eco-friendly packaging and responsible sourcing further enhance brand reputation and consumer trust. Collaborations with hospitality, e-commerce, and retail sectors expand visibility, while competitive intensity remains high with continuous product launches, aggressive marketing strategies, and expansion into emerging markets. This dynamic environment reinforces innovation-driven growth and positions established players to capture long-term opportunities in both developed and developing regions.
Recent Developments
- In April 2025, Heineken introduced The Heineken Studio in Amsterdam to showcase innovative beer-serving technology, including the ability to blend alcoholic and non-alcoholic Heineken.
- In April 2025, Carlsberg Britvic launched 1664 Bière 0.0% (Off Trade), following its early 2025 release in On Trade. The alcohol-free variant hit major UK retailers like ASDA, Tesco, and Waitrose, supported by a multimillion-pound campaign.
- In February 2025, AB InBev reaffirmed its ambition to have no‑ or low‑alcohol beer products represent at least 20% of its global beer volume by the end of 2025, noting that in FY2023, these variants accounted for 6.8%.
- In February 2025, Carlsberg (Germany) introduced Somersby Zero an alcohol-free cider with apple and yuzu & lemon flavors. The launch targets Germany first, with expansion planned for Poland and Sweden in 2026, backed by the brand’s largest-ever German marketing campaign.
Report Coverage
The research report offers an in-depth analysis based on Product, Type, Technology, Sales Store, Wine and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with strong adoption across health-conscious consumer groups.
- Demand will rise for premium non-alcoholic variants with authentic taste and aroma.
- Younger demographics will drive long-term growth through lifestyle shifts toward mindful drinking.
- Technological advancements in brewing and dealcoholization will enhance product quality.
- E-commerce and direct-to-consumer platforms will strengthen global accessibility.
- Sustainability in packaging and production will become a core competitive differentiator.
- Partnerships with hospitality, retail, and entertainment sectors will boost visibility.
- Emerging economies will create new opportunities through rising disposable incomes.
- Innovation in functional ingredients and wellness-focused beverages will diversify product offerings.
- Global players and niche breweries will intensify competition through continuous product launches.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness and Shift Toward Low-Alcohol Alternatives
Increasing global awareness of the health risks associated with alcohol consumption is prompting consumers to seek non-alcoholic alternatives that support wellness without sacrificing social experiences. Public health campaigns and stricter regulations on alcohol further reinforce this shift, creating a steady demand for alcohol-free wine and beer.
Expanding Product Innovation and Premiumization
Advancements in brewing and fermentation technologies have enabled brands to offer improved taste profiles, natural ingredients, and premium variants. This innovation attracts quality-conscious and younger consumers, elevating satisfaction and driving brand loyalty in the non-alcoholic segment.
Growing Influence of Younger Demographics and Lifestyle Changes
Gen Z and millennials are increasingly adopting alcohol-free beverages as part of a balanced lifestyle, prioritizing wellness and social inclusion. Their participation in trends like 'dry months' and preference for mindful drinking are fueling long-term market growth.
Expanding Global Distribution Channels and Accessibility
Wider availability of non-alcoholic wine and beer through supermarkets, specialty stores, e-commerce, and hospitality venues is making these products more accessible. Strategic partnerships and digital platforms are enhancing visibility and driving adoption across both developed and emerging markets.
Technological Advancements in Brewing and Flavor Enhancement
Innovations such as advanced dealcoholization and micro-brewing techniques are improving the sensory quality of non-alcoholic beverages, helping to replicate authentic flavors and aromas. This reduces consumer hesitation and increases repeat purchases, supporting market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Non-Alcoholic Wine and Beer, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Non-Alcoholic Wine and Beer market projected to grow between 2025 and 2032?
Which Non-Alcoholic Wine and Beer market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Non-Alcoholic Wine and Beer market?
Who are the leading companies in the Non-Alcoholic Wine and Beer market?
Which region commanded the largest share of the Non-Alcoholic Wine and Beer market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Alcohol Free [0.0% ABV]
- 1.2.2 Lower Alcohol [0.0% - 1.5% ABV]
- 1.2.3 Lower Alcohol [1.5% - 3.5% ABV]
- 1.3 By Product
- 1.3.1 Beer
- 1.3.2 Wine
- 1.4 By Technology
- 1.4.1 Restricted Fermentation
- 1.4.2 Dealcoholization
- 1.5 By Sales Store
- 1.5.1 Liquor Stores
- 1.5.2 Convenience Stores
- 1.5.3 Supermarkets
- 1.5.4 Online Stores
- 1.5.5 Restaurants & Bar
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 43.3 billion → 2032: USD 94.9 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Non-Alcoholic Wine and Beer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Non-Alcoholic Wine and Beer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Non-Alcoholic Wine and Beer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Non-Alcoholic Wine and Beer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Non-Alcoholic Wine and Beer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Non-Alcoholic Wine and Beer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Non-Alcoholic Wine and Beer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Non-Alcoholic Wine and Beer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 43.3 billion → 2032: USD 94.9 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Non-Alcoholic Wine and Beer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Alcohol Free [0.0% ABV]
- 12.3.7.2 Lower Alcohol [0.0% - 1.5% ABV]
- 12.3.7.3 Lower Alcohol [1.5% - 3.5% ABV]
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Beer
- 12.4.7.2 Wine
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Restricted Fermentation
- 12.5.7.2 Dealcoholization
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Store - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Liquor Stores
- 12.6.7.2 Convenience Stores
- 12.6.7.3 Supermarkets
- 12.6.7.4 Online Stores
- 12.6.7.5 Restaurants & Bar
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Non-Alcoholic Wine and Beer Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Non-Alcoholic Wine and Beer Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Non-Alcoholic Wine and Beer Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Heineken N.V.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Anheuser-Busch InBev
- 17.4 Carlsberg
- 17.5 Suntory Beer
- 17.6 Bernard Brewery
- 17.7 Erdinger Weibbrau
- 17.8 Big Drop Brewing
- 17.9 Pierre Chavin
- 17.10 Moscow Brewing Company
- 17.11 Behnoush Iran
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

