
Market Overview
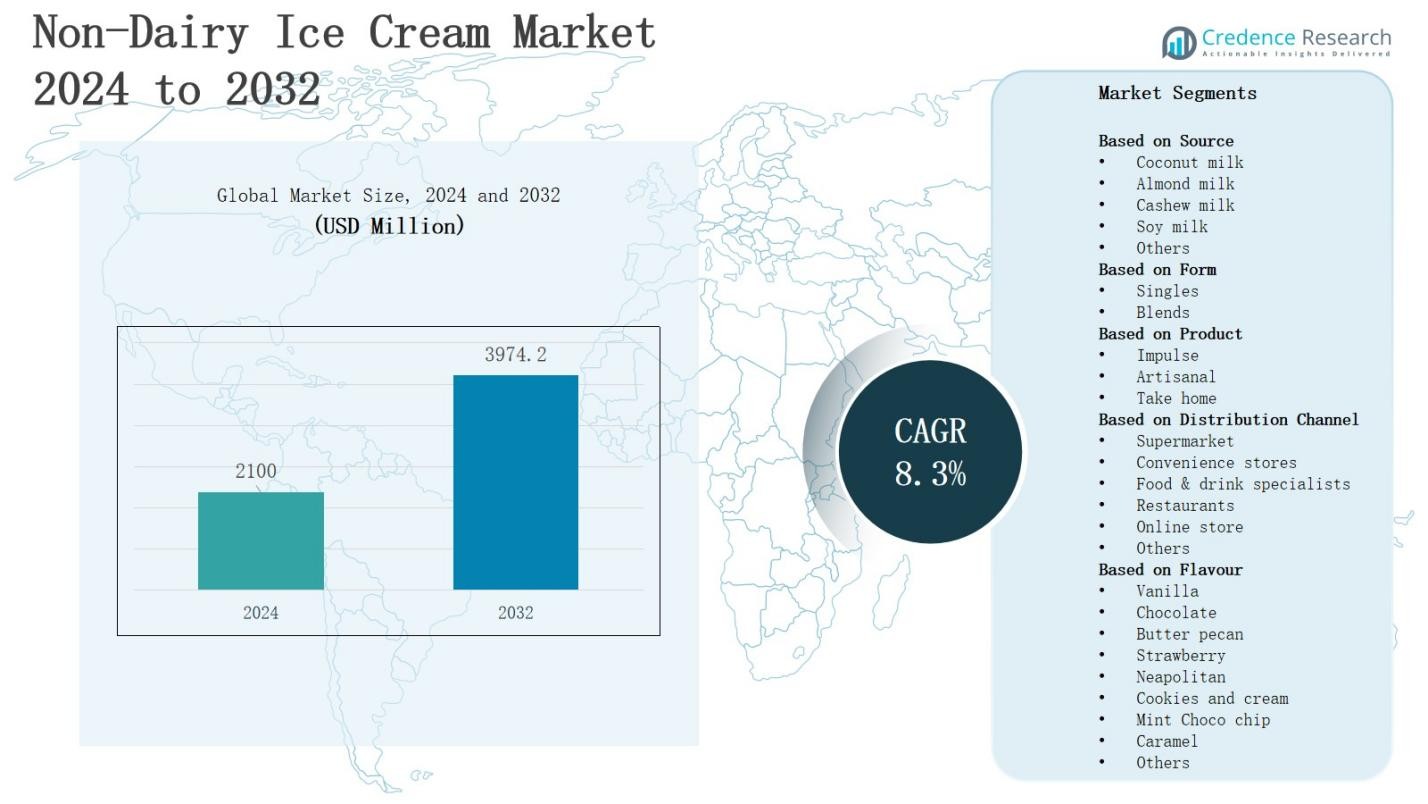
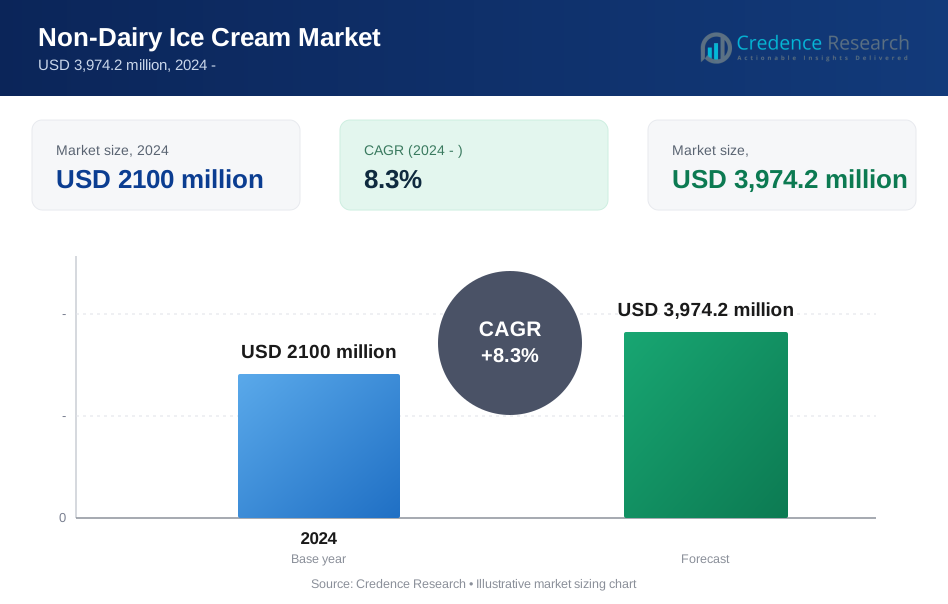
The Non-Dairy Ice Cream Market is projected to grow from USD 2100 million in 2024 to USD 3974.2 million by 2032, registering a CAGR of 8.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Non-Dairy Ice Cream Market Size 2024 | USD 2100 Million |
| Non-Dairy Ice Cream Market, CAGR | 8.3% |
| Non-Dairy Ice Cream Market Size 2032 | USD 3974.2 Million |
The non-dairy ice cream market is driven by rising consumer demand for plant-based alternatives, growing lactose intolerance cases, and increasing vegan lifestyles. Health-conscious consumers prefer dairy-free options with lower cholesterol and allergen-free benefits, boosting adoption across regions. Expanding product innovation, including flavors, textures, and protein-rich formulations, strengthens market appeal. Trends highlight the shift toward clean-label, organic, and sustainably sourced ingredients, as well as the use of alternative bases such as almond, coconut, oat, and soy milk. Premium offerings, eco-friendly packaging, and strong presence on e-commerce platforms further enhance growth and shape competitive dynamics in this market.
The non dairy ice cream market shows strong geographical diversity, led by North America with the largest share, followed by Europe and the rapidly growing Asia-Pacific region. Latin America and the Middle East & Africa are smaller but expanding markets supported by rising health awareness and modern retail growth. It is driven by leading players such as Danone, General Mills, Bliss Unlimited, Eden Creamery, NadaMoo, Swedish Glace, Dream, Over The Moo, Happy Cow, and The Booja-Booja, all competing through innovation, sustainability, and broad distribution networks.
Market Insights
- The non dairy ice cream market will grow from USD 2100 million in 2024 to USD 3974.2 million by 2032, registering an 8.3% CAGR, driven by plant-based demand and vegan lifestyles.
- Coconut milk leads the source segment with 32% share in 2024, followed by almond milk at 26%, soy milk at 18%, cashew milk at 14%, and other sources, including oat, at 10%.
- Singles dominate the form segment with 61% share in 2024, reflecting consumer preference for consistency in taste and texture, while blends capture 39% share with rising adoption.
- Impulse products lead by product type with 45% share, followed by take-home formats at 37% and artisanal products at 18%, supported by growing demand for indulgent, premium, clean-label offerings.
- North America holds 38% share, Europe 27%, Asia-Pacific 22%, Latin America 7%, and Middle East & Africa 6%, with growth driven by awareness, retail expansion, and premium product innovations.
Market Drivers
Rising Demand for Plant-Based Alternatives
The non dairy ice cream market is expanding due to increasing adoption of plant-based diets. Consumers are choosing dairy-free options to align with vegan, vegetarian, and flexitarian lifestyles. It benefits from the growing perception that plant-based foods are healthier, offering lower fat and cholesterol levels. Companies are responding with diverse formulations using almond, oat, soy, and coconut bases. This broad variety attracts health-conscious buyers while meeting dietary restrictions effectively. The demand continues to strengthen global sales.
Health and Wellness Focus Among Consumers
The non dairy ice cream market is gaining traction due to rising concerns over lactose intolerance and dairy allergies. Consumers seek alternatives that avoid digestive discomfort while still delivering indulgence. It is increasingly positioned as a healthier option with fewer allergens and lower saturated fat levels. Manufacturers highlight added functional benefits such as protein or fiber content. This alignment with wellness trends enhances consumer trust. Growing awareness of balanced nutrition strengthens its competitive position in the frozen dessert sector.
- For instance, Halo Top Creamery introduced dairy‑free options made with coconut milk that offer lower calories and higher protein compared to many traditional ice creams.
Product Innovation and Flavor Diversification
The non dairy ice cream market benefits from continuous innovation in flavors, textures, and nutritional profiles. Manufacturers are introducing gourmet options and experimenting with natural sweeteners to meet diverse preferences. It is also witnessing growth in premium offerings with organic and clean-label ingredients. Flavor variety ranging from classic chocolate to exotic fruit blends attracts wider demographics. This product differentiation builds brand loyalty and consumer excitement. Expanding flavor portfolios drive repeat purchases across multiple retail and online channels.
- For instance, Coconut Bliss expanded its portfolio with flavors such as Dark Chocolate Salted Caramel made with organic coconut milk, responding to rising demand for both indulgent and clean‑label options.
Sustainability and Ethical Consumerism
The non dairy ice cream market is shaped by rising demand for eco-friendly and ethical products. Consumers value sustainable sourcing, recyclable packaging, and cruelty-free production practices. It appeals strongly to environmentally aware demographics that connect food choices with sustainability. Brands emphasizing transparency in sourcing and production are gaining a competitive advantage. Ethical positioning enhances brand image and consumer loyalty. This trend drives both niche and mainstream adoption, supporting long-term growth within global frozen dessert markets.
Market Trends
Innovation in Ingredients and Formulations
The non dairy ice cream market is witnessing rapid innovation in ingredients to meet evolving consumer expectations. Brands are developing products with oat, cashew, almond, soy, and coconut milk to replace traditional dairy bases. It benefits from increasing consumer demand for functional ingredients such as added protein, probiotics, and reduced sugar. Clean-label and organic formulations are gaining traction, reflecting consumer preference for transparency. These innovations expand market reach by aligning with health-focused and ethical purchasing behaviors.
- For instance, Van Leeuwen’s utilizes cashew and oat milk as base ingredients, creating rich flavors like pistachio and oat milk chocolate crunch with cookie dough, emphasizing smoothness and novel tastes.
Premiumization and Flavor Diversification
The non dairy ice cream market is experiencing strong growth from premiumization strategies adopted by leading brands. Companies are introducing gourmet flavors, unique textures, and indulgent inclusions such as nut clusters, fruit swirls, and plant-based chocolate. It is expanding appeal beyond traditional vegan consumers to mainstream buyers seeking luxury indulgence. Exotic flavor combinations and limited-edition launches create excitement among younger demographics. This trend strengthens brand positioning in retail and foodservice channels, driving repeat purchases and higher revenue streams.
- For instance, Ben & Jerry’s expanded their plant-based line with exotic flavors and mix-ins such as plant-based chocolate chunks and fruit swirls, targeting younger demographics with a focus on responsible sourcing and richer textures.
Expansion of Distribution Channels
The non dairy ice cream market is benefitting from wider availability across supermarkets, convenience stores, specialty outlets, and online platforms. Growing penetration in e-commerce, supported by delivery apps and subscription models, is fueling access and sales. It appeals strongly to urban consumers who value convenience and variety. Retailers are allocating larger shelf space to plant-based frozen desserts. Partnerships with cafes and restaurants further strengthen market presence. This diversification enhances visibility, improves accessibility, and sustains competitive growth momentum.
Sustainability and Ethical Branding
The non dairy ice cream market is increasingly shaped by rising consumer interest in sustainability and ethical sourcing. Brands emphasize recyclable packaging, carbon footprint reduction, and cruelty-free production processes to align with eco-conscious values. It resonates strongly with younger demographics who prioritize ethical consumption. Transparency in ingredient sourcing enhances consumer trust and loyalty. Companies adopting strong sustainability narratives are strengthening brand image globally. This focus is transforming purchasing decisions and driving broader acceptance of dairy-free frozen desserts.
Market Challenges Analysis
High Production Costs and Pricing Pressure
The non dairy ice cream market faces challenges due to high production costs and pricing disparities compared to conventional ice cream. Premium plant-based ingredients such as almond, cashew, and oat bases are often more expensive, raising overall manufacturing expenses. It struggles to achieve price parity, making products less accessible to price-sensitive consumers. Rising costs for packaging, logistics, and cold chain storage further add to the burden. This limits affordability and slows adoption in emerging markets where consumers prioritize cost-effective options.
Taste, Texture, and Consumer Acceptance Barriers
The non dairy ice cream market continues to face obstacles in delivering taste and texture comparable to traditional dairy products. Consumers often perceive differences in creaminess, flavor richness, and mouthfeel, which restricts repeat purchases. It requires continuous innovation to close this sensory gap and improve overall product experience. Brand loyalty is difficult to build when mainstream consumers hesitate to switch from dairy-based ice cream. Negative perceptions impact marketing efforts. Overcoming these barriers is critical to expanding global adoption.
Market Opportunities
Rising Demand in Emerging Economies
The non dairy ice cream market holds strong opportunities in emerging regions where rising disposable incomes and changing dietary preferences are reshaping consumption patterns. Growing middle-class populations in Asia-Pacific, Latin America, and the Middle East are driving higher demand for premium and health-focused frozen desserts. It benefits from increasing awareness of plant-based nutrition and the influence of Western dietary trends. Expanding retail infrastructure and online grocery platforms further boost accessibility. This creates new revenue streams and long-term growth potential.
Innovation and Customization Potential
The non dairy ice cream market offers opportunities through innovation in flavors, formats, and functional benefits. Consumers are showing interest in products with added protein, probiotics, and reduced sugar content. It also gains from rising demand for customized offerings that cater to dietary needs such as keto-friendly, gluten-free, and allergen-free options. Developing indulgent yet health-oriented products strengthens consumer appeal. Collaborations with foodservice outlets and co-branding initiatives expand visibility. These efforts enhance competitive positioning and drive global adoption rates.
Market Segmentation Analysis:
By Source
The non dairy ice cream market by source is dominated by coconut milk, holding around 32% share in 2024. Its creamy texture, wide availability, and consumer perception of being natural and allergen-friendly make it the most preferred base. Almond milk follows with 26% share, driven by its light taste and nutritional value. Soy milk accounts for 18% share, appealing to cost-sensitive buyers. Cashew milk captures 14% share, favored for premium offerings. Other sources contribute 10% share, including oat and rice milk innovations.
- For instance, Naturals Ice Cream in India is a pioneer of the popular Tender Coconut flavor, made with real malai from tender coconuts sourced locally.
By Form
In terms of form, singles lead the non dairy ice cream market with 61% share in 2024, as consumers prefer single-source bases for consistency in taste and texture. It benefits from strong popularity of coconut and almond milk products across mainstream retail shelves. Blends hold 39% share, gaining traction due to their ability to combine nutritional benefits and unique flavor profiles. Manufacturers are increasingly experimenting with blend-based recipes to attract health-conscious and adventurous consumers seeking novelty.
By Product
By product type, impulse products dominate the non dairy ice cream market with 45% share in 2024, driven by strong sales in convenience stores and quick-service outlets. Take-home formats follow closely with 37% share, supported by family consumption and availability in larger pack sizes through supermarkets and online channels. Artisanal products hold 18% share, reflecting rising demand for premium, handcrafted, and clean-label options. Growing consumer interest in indulgence and premiumization continues to push artisanal offerings into niche but expanding segments.
- For instance, Unilever expanded its Magnum Non-Dairy bars, a popular impulse purchase available through convenience channels and quick-service outlets.
Segments:
Based on Source
- Coconut milk
- Almond milk
- Cashew milk
- Soy milk
- Others
Based on Form
- Singles
- Blends
Based on Product
- Impulse
- Artisanal
- Take home
Based on Distribution Channel
- Supermarket
- Convenience stores
- Food & drink specialists
- Restaurants
- Online store
- Others
Based on Flavour
- Vanilla
- Chocolate
- Butter pecan
- Strawberry
- Neapolitan
- Cookies and cream
- Mint Choco chip
- Caramel
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the non dairy ice cream market with 38% share in 2024, driven by high consumer awareness and strong demand for plant-based foods. The region benefits from a well-established vegan community and wide retail availability across supermarkets, specialty stores, and online platforms. It gains momentum from innovation in flavors, clean-label products, and sustainable packaging. Rising lactose intolerance cases further fuel adoption. Strong presence of leading brands and investments in premium product development strengthen market growth across the United States and Canada.
Europe
Europe accounts for 27% share of the non dairy ice cream market in 2024, supported by rising health-consciousness and increasing preference for dairy-free lifestyles. The region shows strong demand in countries like Germany, the UK, and France, where consumers value sustainability and organic offerings. It benefits from strict food labeling regulations that encourage transparency and trust. Growth in artisanal and premium plant-based desserts enhances product acceptance. The market is further strengthened by expanding vegan populations and innovative retail distribution strategies.
Asia-Pacific
Asia-Pacific holds 22% share in the non dairy ice cream market in 2024, emerging as the fastest-growing regional segment. Rising disposable incomes, urbanization, and growing middle-class populations drive higher demand for healthier and premium desserts. It benefits from increasing lactose intolerance prevalence across China, India, and Southeast Asia. Global and local brands are expanding product portfolios to match regional taste preferences. Rapid growth of e-commerce and modern retail further accelerates sales. This region offers significant long-term growth potential.
Latin America
Latin America captures 7% share in the non dairy ice cream market in 2024, supported by increasing adoption of plant-based diets and influence from global food trends. Brazil and Mexico lead consumption, driven by younger demographics seeking healthier indulgence options. It faces challenges from higher product pricing compared to traditional ice cream, but rising awareness is creating opportunities. Expanding distribution networks and greater availability in retail outlets strengthen visibility. Growing interest in sustainable and ethical products boosts regional market growth.
Middle East & Africa
The Middle East & Africa account for 6% share in the non dairy ice cream market in 2024, with growth supported by increasing urban populations and rising health awareness. Demand is concentrated in Gulf countries where premium and imported brands dominate. It benefits from growing hospitality and foodservice sectors that introduce dairy-free desserts into menus. Limited cold-chain infrastructure poses a challenge, yet expanding modern retail helps improve accessibility. Consumer preference for lactose-free and healthier indulgence continues to strengthen adoption.
Key Player Analysis
- NadaMoo
- Swedish Glace
- General Mills
- The Booja-Booja
- Bliss Unlimited
- Happy Cow
- Over The Moo
- Danone
- Eden Creamery
- Dream
Competitive Analysis
The non dairy ice cream market is highly competitive, characterized by strong brand positioning, continuous innovation, and expanding distribution strategies. Key players such as Danone, General Mills, Bliss Unlimited, Eden Creamery, NadaMoo, Swedish Glace, Dream, Over The Moo, Happy Cow, and The Booja-Booja compete by introducing diverse flavors, plant-based formulations, and premium offerings to capture wider consumer segments. It is shaped by increasing demand for clean-label, organic, and allergen-free products that align with health and sustainability trends. Companies are strengthening their presence across supermarkets, specialty stores, and online channels, while partnerships with foodservice outlets enhance visibility. Investment in product differentiation, marketing, and eco-friendly packaging is driving brand loyalty. Emerging regional players are challenging global leaders with locally tailored flavors and competitive pricing. Innovation in functional ingredients such as protein-enriched and low-sugar variants is further intensifying rivalry. The competitive landscape reflects a balance of global corporations leveraging scale advantages and niche brands focusing on authenticity, taste, and ethical sourcing, ensuring sustained dynamism across the industry.
Recent Developments
- In August 2025, Japanese food tech startup Kinish introduced The Rice Creamery, a rice-based plant ice cream brand with 60% less sugar and 62% lower greenhouse gas emissions.
- In early 2024, Perfect Day partnered with Unilever’s Breyers to unveil a lactose-free chocolate ice cream made with animal-free whey protein to promote sustainable dairy alternatives.
- In January 2025, Breyers introduced a new Non‑Dairy Chocolate ice cream made with an oat‑milk base, offering the classic creamy experience in a dairy‑free format.
- In January 2025, Ben & Jerry’s introduced a new Bohemian Raspberry non‑dairy flavor, expanding its dairy-free lineup with a fruity, indulgent offering.
Report Coverage
The research report offers an in-depth analysis based on Source, Form, Product, Distribution Channel, Flavour and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising vegan and flexitarian lifestyles will drive strong global demand for non dairy ice cream.
- Growing health awareness will increase preference for lactose-free, allergen-free, and low-cholesterol frozen dessert options.
- Product innovation in flavors, textures, and functional benefits will attract wider consumer demographics worldwide.
- Expansion of e-commerce platforms and subscription models will enhance consumer accessibility and brand visibility.
- Premium and artisanal offerings will strengthen positioning, catering to indulgent consumers seeking clean-label authenticity.
- Sustainability initiatives, including eco-friendly packaging and ethical sourcing, will shape long-term consumer loyalty patterns.
- Strategic partnerships with restaurants, cafes, and foodservice outlets will expand market penetration and distribution.
- Emerging economies will witness rising adoption driven by urbanization, disposable income, and modern retail growth.
- Technological advancements in plant-based formulations will improve taste, texture, and product acceptance among mainstream consumers.
- Competition among global leaders and regional players will intensify, encouraging continuous innovation and differentiation strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Plant-Based and Vegan Lifestyle Adoption
Increasing numbers of consumers are adopting plant-based, vegan, and flexitarian diets, driving demand for non-dairy ice cream as a preferred alternative to traditional dairy desserts.
Health and Wellness Focus
Rising awareness of lactose intolerance, dairy allergies, and the desire for lower cholesterol and allergen-free foods is pushing consumers toward non-dairy ice cream options that align with health and wellness trends.
Product Innovation and Flavor Diversification
Continuous innovation in flavors, textures, and nutritional profiles - including protein-rich, clean-label, and organic offerings - attracts a broader consumer base and encourages repeat purchases.
Sustainability and Ethical Consumerism
Growing consumer preference for sustainably sourced ingredients, recyclable packaging, and cruelty-free production is boosting the appeal of non-dairy ice cream, especially among environmentally conscious demographics.
Expansion of Distribution Channels
Wider availability across supermarkets, convenience stores, specialty outlets, and online platforms, including e-commerce and delivery apps, is making non-dairy ice cream more accessible and driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for non dairy ice cream market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the non dairy ice cream market projected to grow between 2025 and 2032?
Which non dairy ice cream market segment held the largest share in 2024?
What are the primary factors fueling the growth of the non dairy ice cream market?
Who are the leading companies in the non dairy ice cream market?
Which region commanded the largest share of the non dairy ice cream market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Singles
- 1.2.2 Blends
- 1.3 By Source
- 1.3.1 Coconut milk
- 1.3.2 Almond milk
- 1.3.3 Cashew milk
- 1.3.4 Soy milk
- 1.3.5 Others
- 1.4 By Product
- 1.4.1 Impulse
- 1.4.2 Artisanal
- 1.4.3 Take home
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2100 million → 2032: USD 3,974.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Non-Dairy Ice Cream Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Non-Dairy Ice Cream Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Non-Dairy Ice Cream Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Non-Dairy Ice Cream Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Non-Dairy Ice Cream Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Non-Dairy Ice Cream Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Non-Dairy Ice Cream Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Non-Dairy Ice Cream Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2100 million → 2032: USD 3,974.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Non-Dairy Ice Cream Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Singles
- 12.3.7.2 Blends
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coconut milk
- 12.4.7.2 Almond milk
- 12.4.7.3 Cashew milk
- 12.4.7.4 Soy milk
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Impulse
- 12.5.7.2 Artisanal
- 12.5.7.3 Take home
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Non-Dairy Ice Cream Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Non-Dairy Ice Cream Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Non-Dairy Ice Cream Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Danone
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 General Mills
- 17.4 Bliss Unlimited
- 17.5 Eden Creamery
- 17.6 NadaMoo
- 17.7 Swedish Glace
- 17.8 Dream
- 17.9 Over The Moo
- 17.10 Happy Cow
- 17.11 The Booja-Booja
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

