
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Caffeinated Beverage Market Size 2024 | USD 86,163.52 million |
| North America Caffeinated Beverage Market, CAGR | 4.81% |
| North America Caffeinated Beverage Market Size 2032 | USD 1,25,501.18 million |
Market Overview
North America Caffeinated Beverage market size was valued at USD 86,163.52 million in 2024 and is anticipated to reach USD 1,25,501.18 million by 2032, at a CAGR of 4.81% during the forecast period (2024-2032).
The North America Caffeinated Beverage market is driven by increasing consumer demand for energy-boosting drinks like coffee and energy beverages, as consumers seek enhanced alertness and productivity. The growing preference for ready-to-drink options, such as bottled coffee and energy drinks, reflects the demand for convenience in busy lifestyles. Additionally, the market is benefiting from innovation in beverage formulations, with new flavors and healthier ingredient options attracting health-conscious consumers. The rise of functional beverages, incorporating added benefits like vitamins and electrolytes, is further fueling market growth. Sustainability initiatives by companies, including eco-friendly packaging and sourcing of ethical ingredients, are also gaining traction among environmentally aware consumers. With an increasing number of consumers adopting caffeinated beverages as part of their daily routine, the market is expected to expand steadily, driven by both evolving consumer preferences and ongoing product innovations.
The North America Caffeinated Beverage market is primarily driven by the U.S., Canada, and Mexico, each exhibiting unique consumption patterns and preferences. In the U.S., there is a strong demand for energy drinks, ready-to-drink (RTD) coffee, and functional beverages, with major players like Nestlé, Red Bull, PepsiCo, and The Coca-Cola Company dominating the market. Canada mirrors U.S. trends, with an increasing focus on health-conscious and premium beverage options, creating opportunities for both international and local brands. In Mexico, energy drinks are highly popular, especially among younger consumers, and RTD coffee and tea are gaining traction in urban areas. Key players such as Red Bull and PepsiCo have a significant presence, while local brands also contribute to market growth. These players continually innovate, introducing new flavors and functional ingredients to cater to shifting consumer preferences in each region.
Market Insights
- The North America Caffeinated Beverage market was valued at USD 86,163.52 million in 2024 and is projected to reach USD 1,25,501.18 million by 2032, growing at a CAGR of 4.81% during the forecast period.
- The global caffeinated beverage market was valued at USD 252,050.67 million in 2024 and is expected to reach USD 369,284.04 million by 2032, growing at a CAGR of 4.89%.
- Increasing consumer demand for functional beverages with added health benefits, such as vitamins and electrolytes, is driving market growth.
- Specialty beverages, including cold brew coffee and energy drinks with natural ingredients, are becoming more popular among health-conscious consumers.
- Intense competition from both established global brands and local players is making market differentiation a key challenge for companies.
- Health concerns regarding excessive caffeine intake, particularly among vulnerable populations, are restraining market expansion.
- The U.S. dominates the market, with Canada and Mexico showing strong growth potential, driven by increasing urbanization and consumer interest in RTD options.
- Key players such as Nestlé, Red Bull, PepsiCo, and The Coca-Cola Company lead the competitive landscape.
Report Scope
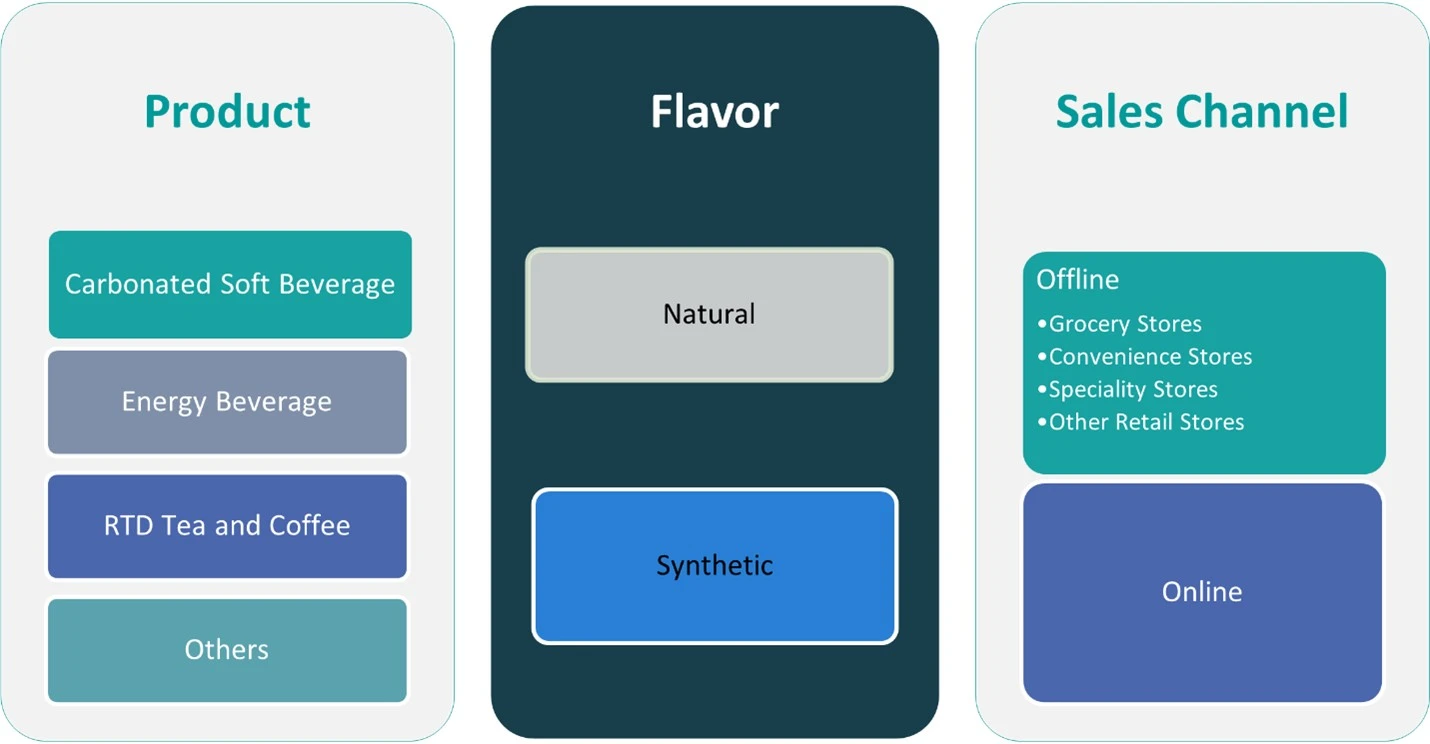
This report segments the North America Caffeinated Beverage Market as follows:
Market Drivers
Rising Demand for Energy Drinks and Coffee
One of the primary drivers of the North America Caffeinated Beverage market is the growing consumer preference for energy-boosting drinks, such as coffee and energy drinks. With the increasing pace of modern life, many individuals rely on caffeinated beverages to stay alert, enhance productivity, and maintain focus throughout the day. For instance, the U.S. caffeine market is experiencing steady growth, driven by increasing demand for caffeinated products in beverages, snacks, and energy foods. Coffee, particularly in various ready-to-drink formats, has gained immense popularity across the region, appealing to consumers who seek both a caffeine boost and convenience. Similarly, energy drinks have become a staple for individuals who require immediate and sustained energy, whether for work or physical activities. This surge in demand is expected to continue driving the market, as caffeinated beverages have solidified their place in North American daily consumption patterns.
Sustainability and Eco-Friendly Practices
Sustainability has become a significant consideration for consumers when choosing caffeinated beverages, and companies in North America are responding accordingly. Increasing environmental awareness among consumers is prompting brands to adopt eco-friendly practices in sourcing, production, and packaging. For instance, the North American beverage industry is prioritizing sustainable packaging solutions to align with consumer expectations and regulatory requirements. Many companies are investing in sustainable sourcing of coffee beans, particularly through fair trade and organic certifications, to appeal to ethically conscious consumers. Additionally, the use of recyclable or biodegradable packaging, as well as initiatives to reduce carbon footprints, is gaining traction. This commitment to sustainability resonates with younger, environmentally aware consumers, further driving demand for brands that prioritize eco-conscious practices. As sustainability becomes an essential factor in purchasing decisions, companies that adopt greener approaches are likely to benefit from increased consumer loyalty and market share.
Convenience of Ready-to-Drink Beverages
The convenience factor associated with ready-to-drink (RTD) beverages is a significant market driver in North America. Busy lifestyles, particularly among working professionals and younger generations, have led to a preference for on-the-go, pre-packaged beverages. Ready-to-drink coffee, iced lattes, and energy drinks offer a convenient solution for consumers seeking caffeine without the need for preparation. As a result, the RTD segment is witnessing strong growth, with innovations in packaging, such as single-serve bottles and cans, making these beverages highly accessible. This trend is amplified by the availability of these drinks in retail locations such as convenience stores, supermarkets, and vending machines, which further enhances their accessibility to a wide range of consumers.
Health-Conscious Consumption and Functional Beverages
Health-consciousness is another key driver of the North America Caffeinated Beverage market. As more consumers shift towards healthier lifestyles, they seek beverages that provide not only energy but also functional benefits. Many consumers now prefer beverages with added health benefits, such as vitamins, minerals, antioxidants, and electrolytes, in addition to caffeine. The growing demand for functional beverages, which are designed to improve physical and mental well-being, has led to the emergence of drinks that combine caffeine with other wellness-enhancing ingredients. This shift toward healthier formulations and the demand for low-sugar, organic, and natural caffeinated options are expected to continue driving market growth in the coming years. Brands are increasingly focusing on developing products that align with these health trends while maintaining the energizing effects of caffeine.
Market Trends
Shift Towards Premium and Specialty Caffeinated Drinks
One of the most notable trends in the North America Caffeinated Beverage market is the shift towards premium and specialty drinks. Consumers are becoming more discerning in their beverage choices, seeking higher-quality coffee, energy drinks, and functional beverages that offer unique flavors, aromas, and health benefits. Specialty coffee, such as cold brew, nitro coffee, and single-origin brews, is gaining popularity, with consumers willing to pay a premium for these unique and artisanal offerings. For instance, the market has seen a migration to higher-value, more artisanal products, prompting manufacturers to upgrade packaging and branding. This trend is also seen in energy drinks, where consumers are gravitating toward premium brands that use natural ingredients, offer a variety of flavors, and provide added functional benefits like electrolytes and adaptogens. As demand for more sophisticated and high-end options grows, the market is expected to see increased competition among brands to cater to these refined tastes.
Integration of Functional Ingredients
The integration of functional ingredients into caffeinated beverages is another key trend reshaping the market. Beyond traditional caffeine, consumers are increasingly seeking beverages that provide additional health benefits, such as antioxidants, vitamins, electrolytes, and adaptogens. For example, energy drinks are now commonly infused with ingredients like B-vitamins, amino acids, and electrolytes, designed to improve mental clarity, hydration, and physical performance. For instance, the U.S. Food and Drug Administration (FDA) has noted a rising trend in the approval of caffeine-based products, supporting market expansion. Coffee brands are also capitalizing on this trend by introducing functional blends that combine caffeine with added health benefits like probiotics, turmeric, or collagen. This movement toward functional beverages reflects broader consumer interest in wellness and self-care, making it a key driver of market growth as more people opt for beverages that support their overall health goals.
Growth of Plant-Based and Alternative Caffeinated Beverages
As the demand for plant-based products continues to rise, the North America Caffeinated Beverage market is witnessing the growth of plant-based and alternative caffeinated drinks. Consumers are increasingly looking for caffeine sources that align with their dietary preferences, including plant-based options such as coffee alternatives made from ingredients like matcha, yerba mate, or guayusa. These alternatives appeal to individuals who avoid traditional coffee or energy drinks due to dietary restrictions, caffeine sensitivity, or personal preference. Plant-based milks, such as oat and almond milk, are also becoming popular additions to coffee drinks, catering to vegan and lactose-intolerant consumers. This trend is expanding the range of caffeinated beverages available in the market and contributing to the diversification of offerings.
E-Commerce and Direct-to-Consumer Sales Channels
The rise of e-commerce and direct-to-consumer (DTC) sales channels is transforming how caffeinated beverages reach consumers in North America. The convenience and accessibility of online shopping have made it easier for consumers to purchase their favorite caffeinated drinks directly from brands’ websites or third-party platforms. Subscription-based models, where consumers receive regular shipments of their preferred beverages, are gaining popularity, providing both convenience and cost savings. Additionally, brands are leveraging social media platforms and digital marketing to engage with consumers, build brand loyalty, and drive sales. This trend has become especially pronounced in the wake of the COVID-19 pandemic, as more consumers opt to shop online for their beverages rather than visit physical retail locations, contributing to the growth of e-commerce in the sector.
Market Challenges Analysis
Health Concerns and Regulatory Scrutiny
A significant challenge facing the North America Caffeinated Beverage market is growing health concerns regarding the consumption of high-caffeine products, particularly among vulnerable populations such as adolescents and individuals with underlying health conditions. Excessive caffeine intake can lead to negative health effects such as anxiety, insomnia, high blood pressure, and heart palpitations. For instance, the U.S. Food and Drug Administration (FDA) has stated that 400 milligrams per day is generally considered safe for healthy adults, but many Americans underestimate the safe limit. As awareness of these health risks increases, there is heightened scrutiny from health organizations and regulators. In response, several North American countries have introduced or are considering regulations on caffeine content, labeling requirements, and marketing strategies, particularly for energy drinks targeted at younger consumers. Companies in the caffeinated beverage sector must navigate these regulatory hurdles while ensuring that their products remain safe and appealing to consumers. Striking a balance between product innovation and consumer health concerns will be a key challenge for industry players moving forward.
Intense Competition and Market Saturation
The North American Caffeinated Beverage market is also experiencing intense competition and market saturation, particularly within the coffee and energy drink segments. Established brands, such as Starbucks and Red Bull, dominate the market, making it challenging for new entrants to capture market share. Additionally, the proliferation of private-label and store-brand caffeinated beverages, which often offer lower prices, intensifies competition. As the market matures, companies must focus on differentiating their products through innovation, branding, and unique value propositions to stand out in a crowded market. Furthermore, the growth of healthier, functional beverages means that brands must continually adapt to shifting consumer preferences for natural ingredients, lower sugar content, and sustainable packaging. In such a competitive landscape, maintaining market share and profitability requires constant innovation and effective marketing strategies.
Market Opportunities
The North America Caffeinated Beverage market presents significant opportunities driven by evolving consumer preferences and emerging trends. As health-consciousness continues to rise, there is growing demand for beverages that offer functional benefits beyond caffeine, such as added vitamins, electrolytes, and antioxidants. Companies can capitalize on this opportunity by developing new caffeinated drinks that cater to these wellness-focused consumers. By incorporating natural and organic ingredients, including adaptogens and probiotics, brands can differentiate their products and tap into the expanding market for functional and health-enhancing beverages. Additionally, the increasing preference for plant-based options provides another opportunity for growth, with consumers seeking alternatives to traditional coffee and energy drinks. Plant-based caffeinated beverages, such as those made with matcha or yerba mate, present a promising avenue for brands to attract a broader demographic, including vegan and lactose-intolerant consumers.
Another key opportunity lies in the rise of e-commerce and direct-to-consumer (DTC) sales channels. As online shopping continues to grow, particularly after the pandemic, brands can expand their reach and enhance customer engagement through digital platforms. Subscription-based services for regular deliveries of caffeinated beverages could also prove lucrative, offering both convenience for consumers and consistent revenue for companies. Moreover, the ability to engage directly with consumers through social media and targeted digital marketing campaigns enables brands to build loyalty and drive repeat purchases. This shift toward DTC sales, coupled with innovations in product offerings, allows companies to capitalize on a more personalized and direct approach to marketing and sales. By embracing these opportunities, brands can strengthen their market position and cater to the evolving preferences of North American consumers.
Market Segmentation Analysis:
By Product:
The North America Caffeinated Beverage market can be segmented into four primary product categories: carbonated soft beverages, energy beverages, ready-to-drink (RTD) tea and coffee, and others. Among these, energy beverages hold the largest market share, driven by the growing consumer demand for drinks that provide an immediate energy boost, particularly among younger consumers and individuals with active lifestyles. Energy drinks are commonly marketed with added functional benefits like electrolytes, vitamins, and amino acids, making them increasingly popular for both physical and mental performance. RTD tea and coffee are experiencing significant growth, particularly in the convenience-driven market, as consumers seek easy-to-consume, pre-brewed options. These beverages, often available in iced or cold brew formats, cater to the expanding preference for on-the-go, ready-made options. Carbonated soft beverages, while still a major player, are facing slight declines in growth as consumers shift towards healthier alternatives. The "others" category includes a variety of niche products such as caffeinated water and functional beverages, which are gaining popularity due to their perceived health benefits.
By Flavor:
Caffeinated beverages in North America are also segmented by flavor, primarily into natural and synthetic categories. Natural flavors are becoming increasingly popular as consumers shift toward more organic, clean-label products. This trend is driven by the growing demand for healthier, all-natural ingredients, with many consumers preferring beverages that contain minimal artificial additives. Brands that use natural flavors are attracting health-conscious consumers, particularly those seeking products with fewer preservatives and chemicals. In contrast, synthetic flavors, while still prevalent in the market, are seeing a decline as more consumers are scrutinizing the ingredients in their drinks. Synthetic flavors are often used in carbonated soft drinks and energy beverages, but their popularity is waning as a result of increased health awareness. The shift towards natural flavors presents significant opportunities for brands to innovate and align with consumer demands for cleaner, more transparent products. By focusing on natural ingredients, companies can appeal to a broader audience and gain a competitive edge.
Segments:
Based on Product:
- Carbonated Soft Beverage
- Energy Beverage
- RTD Tea and Coffee
- Others
Based on Flavor:
- Natural
- Synthetic
Based on Sales Channel:
- Offline
- Grocery Stores
- Convenience Stores
- Speciality Stores
- Other Retail Stores
- Online
Based on the Geography:
- U.S.
- Canada
- Mexico
Regional Analysis
U.S.
U.S. holds the largest share of the market, accounting for approximately 75% of the total market. This is primarily driven by the high consumer demand for both energy drinks and ready-to-drink (RTD) coffee and tea. The U.S. is home to a large population of health-conscious consumers and a highly developed retail infrastructure, making it the most significant market for caffeinated beverages in North America. Major brands such as Red Bull, Monster, and Starbucks, along with an increasing number of local and regional players, are key factors contributing to the U.S.'s dominance in the market.
Canada
Canada holds the second-largest share in the North American market, contributing around 15% of the total market size. The Canadian market is similar to that of the U.S. in terms of consumer preferences for energy drinks and RTD beverages, though the market is slightly smaller in scale. The popularity of coffee and energy drinks is steadily growing, particularly among younger demographics. Furthermore, Canada's increasing inclination toward health-conscious and functional beverages, such as those offering natural ingredients or additional health benefits, has led to the expansion of niche product categories. This trend is expected to fuel further growth in the Canadian caffeinated beverage market.
Mexico
Mexico, while having the smallest market share in North America, is experiencing significant growth in its caffeinated beverage sector, contributing about 10% to the total market. Energy drinks are particularly popular in Mexico, with a large segment of consumers in urban areas opting for these beverages to stay energized throughout the day. Additionally, the growing popularity of RTD coffee and tea is starting to gain traction in major cities. Mexico's increasing urbanization, younger population, and rising disposable incomes make it an attractive market for global brands and local players aiming to tap into the demand for caffeinated beverages. As the market matures, new product innovations, including functional and flavored drinks, are expected to boost growth.
Key Player Analysis
- Nestlé
- Red Bull
- PepsiCo
- The Coca-Cola Company
- 5-hour ENERGY
Competitive Analysis
The North America Caffeinated Beverage market is highly competitive, with leading players such as Nestlé, Red Bull, PepsiCo, The Coca-Cola Company, and 5-hour ENERGY dominating the market. These companies have strong brand recognition and extensive distribution networks, allowing them to maintain a significant market share. These players are investing in the development of new flavors, low-sugar alternatives, and functional ingredients like electrolytes, vitamins, and antioxidants. The rise of plant-based and organic caffeinated options has further intensified competition, as consumers increasingly demand beverages that align with their health and sustainability goals. In addition to innovation, these companies are expanding their distribution channels, including the growing trend of e-commerce and direct-to-consumer sales. This allows brands to reach a broader audience while offering personalized experiences and subscription-based services. Strong branding and targeted marketing campaigns also play a crucial role in differentiating products in a saturated market. The competitive landscape is also influenced by pricing strategies, with some players leveraging economies of scale to offer lower-priced alternatives, while others focus on premium, higher-margin products. As the market matures, successful companies will continue to adapt to shifting consumer preferences and regulatory changes, positioning themselves for sustained growth in the North American market.
Recent Developments
- In March 2025, PepsiCo expanded its Pepsi MAX Caffeine Free line with a new 500ml bottle in the UK, responding to rising demand for caffeine-free and sugar-free colas among younger consumers.
- In February 2025, Coca-Cola introduced Simply Pop, a prebiotic, fruit juice-enriched soda targeting the “better-for-you” market segment, competing with brands like Poppi and Olipop.
- In January 2025, Nestlé implemented a new global organizational structure for its Waters & Premium Beverages division, operating as a standalone business.
- In June 2024, the Starbucks Corporation, one of the renowned brands in caffeinated beverages industry launched new range of Caramel Vanilla Swirl Iced Coffee, handcrafted energy drinks and few other products. Starbucks Tripleshot Energy drink, recently launched offering is characterized by 65mg of caffeine content, protein, B vitamins. The products is provided in three flavor choices including dark caramel, bold mocha, and rich vanilla.
- In February 2024, Dunkin’, one of the applauded brands in food & beverages industry introduced SPARKD' Energy by Dunkin’, iced beverages equipped with minerals, vitamins and some amount of caffeine. The flavors include berry burst entailing strawberry and raspberry, and peach sunshine featuring lychee and juicy peach flavors.
Market Concentration & Characteristics
The North America Caffeinated Beverage market exhibits a moderate to high level of market concentration, with a few dominant players holding a significant share across various product categories. These leading companies leverage strong brand equity, extensive distribution networks, and continuous product innovation to maintain their competitive advantage. The market is characterized by high consumer awareness, strong brand loyalty, and evolving preferences for functional, low-sugar, and health-oriented beverages. While large multinational corporations control a substantial portion of the market, there is a growing presence of niche and regional brands that cater to specialized consumer needs such as organic, plant-based, or clean-label caffeinated beverages. The market also reflects characteristics of rapid innovation, where new product launches and flavor variations are key strategies for sustaining consumer engagement. Moreover, convenience and on-the-go consumption trends are shaping product formats, especially in ready-to-drink categories. As a result, the market remains dynamic and competitive, driven by both innovation and consumer-centric offerings
Report Coverage
The research report offers an in-depth analysis based on Product, Flavor, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth driven by rising demand for functional and energy-boosting beverages.
- Consumers will increasingly prefer products with natural caffeine sources and clean-label ingredients.
- Ready-to-drink coffee and tea segments are projected to gain further traction due to convenience and health appeal.
- Innovation in flavors, packaging, and functional benefits will remain central to product development strategies.
- Online and direct-to-consumer sales channels are likely to expand, enhancing market reach and accessibility.
- Sustainable sourcing and eco-friendly packaging will become key focus areas for brand differentiation.
- Health-conscious consumers will drive demand for low-sugar, organic, and plant-based caffeinated beverages.
- Companies are expected to invest more in marketing targeted at young, active, and wellness-focused demographics.
- Cross-category product collaborations may rise, combining caffeine with hydration or nutritional benefits.
- Growth opportunities will emerge in Mexico and Canada as urbanization and disposable income levels increase.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Convenience of Ready-to-Drink Beverages
Busy lifestyles and the need for on-the-go consumption are fueling demand for ready-to-drink (RTD) coffee, tea, and energy drinks, which offer consumers a quick and accessible caffeine boost without preparation.
Health-Conscious and Functional Beverage Trends
Consumers are increasingly seeking caffeinated beverages that provide added health benefits, such as vitamins, electrolytes, and antioxidants, driving innovation in product formulations and the growth of functional beverage segments.
Sustainability and Eco-Friendly Practices
Rising environmental awareness is prompting brands to adopt sustainable sourcing, eco-friendly packaging, and ethical ingredient practices, which resonate with younger, environmentally conscious consumers and influence purchasing decisions.
Shift Toward Premium and Specialty Products
There is a growing preference for premium, artisanal, and specialty caffeinated drinks such as cold brew, nitro coffee, and energy drinks with natural ingredients, as consumers seek unique flavors and higher-quality experiences.
Expansion of E-Commerce and Direct-to-Consumer Channels
The growth of online shopping and subscription-based models is making caffeinated beverages more accessible, allowing brands to reach a wider audience and build stronger customer loyalty through digital engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the North America Caffeinated Beverage?
What factors are driving the growth of the North America Caffeinated Beverage?
What are the key segments within the North America Caffeinated Beverage?
Who are the major players in the North America Caffeinated Beverage?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Flavor
- 1.2.1 Natural
- 1.2.2 Synthetic
- 1.3 By Product
- 1.3.1 Carbonated Soft Beverage
- 1.3.2 Energy Beverage
- 1.3.3 RTD Tea and Coffee
- 1.3.4 Others
- 1.4 By Sales Channel
- 1.4.1 Offline
- 1.4.2 Grocery Stores
- 1.4.3 Convenience Stores
- 1.4.4 Speciality Stores
- 1.4.5 Other Retail Stores
- 1.4.6 Online
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 86,163.52 million → 2032: USD 1,25,501.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Caffeinated Beverage Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Caffeinated Beverage Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Caffeinated Beverage Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Caffeinated Beverage Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Caffeinated Beverage Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Caffeinated Beverage Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Caffeinated Beverage Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Caffeinated Beverage Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 86,163.52 million → 2032: USD 1,25,501.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Caffeinated Beverage Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Flavor - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Natural
- 12.3.7.2 Synthetic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Carbonated Soft Beverage
- 12.4.7.2 Energy Beverage
- 12.4.7.3 RTD Tea and Coffee
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Offline
- 12.5.7.2 Grocery Stores
- 12.5.7.3 Convenience Stores
- 12.5.7.4 Speciality Stores
- 12.5.7.5 Other Retail Stores
- 12.5.7.6 Online
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Caffeinated Beverage Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America Caffeinated Beverage Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 North America Caffeinated Beverage Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Nestlé
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Red Bull
- 17.4 PepsiCo
- 17.5 The Coca-Cola Company
- 17.6 5-hour ENERGY
- 17.7 Monster Beverage Corporation
- 17.8 Starbucks Corporation
- 17.9 Dunkin'
- 17.10 Keurig Dr Pepper
- 17.11 Rockstar Energy
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

