
Market Overview:
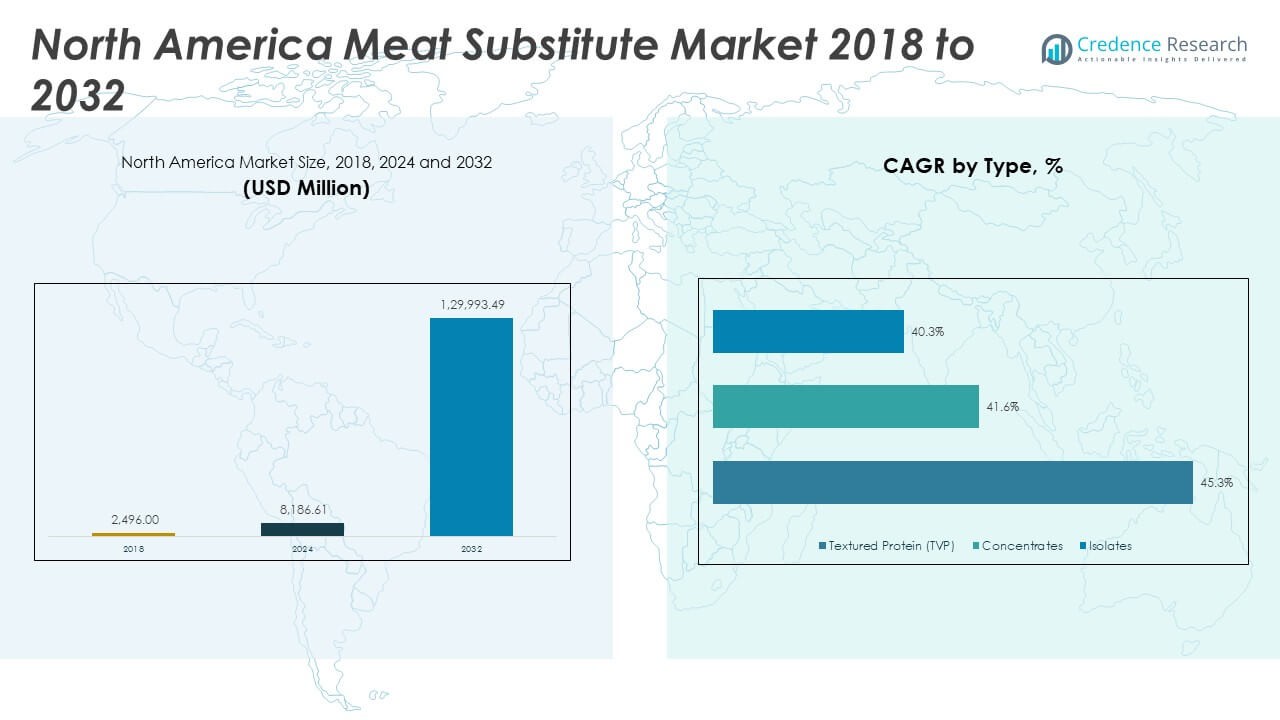
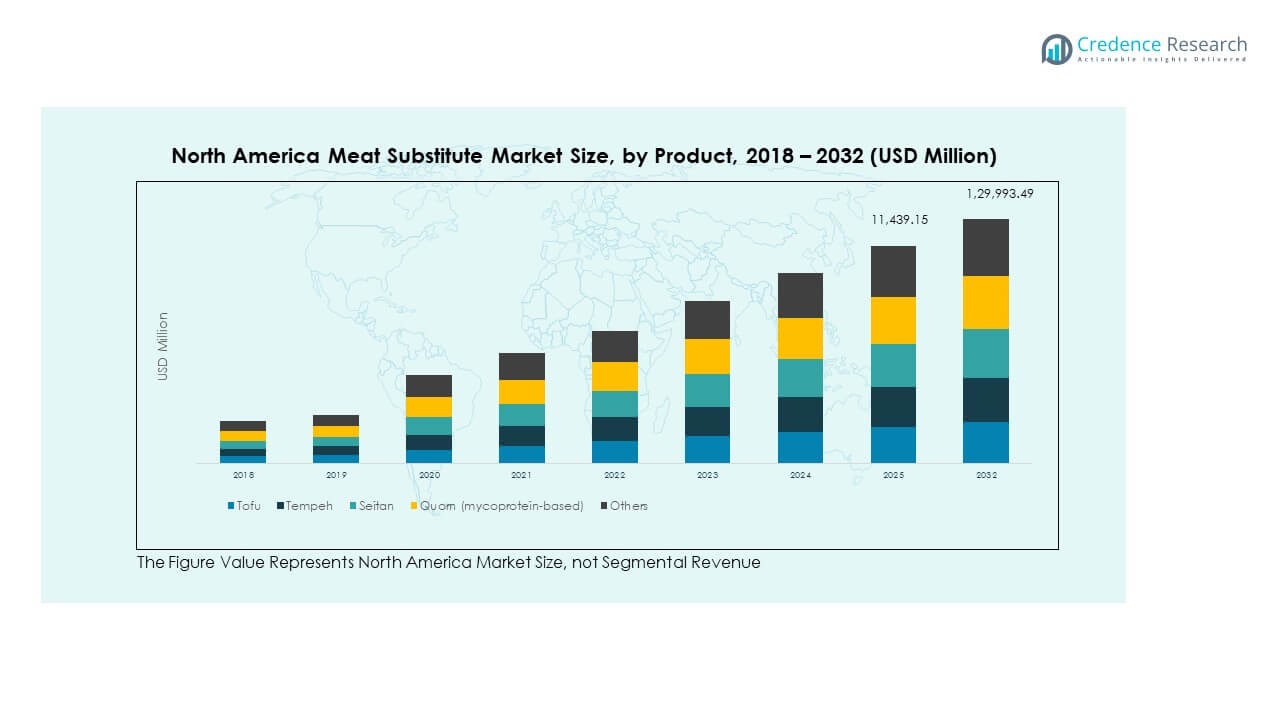
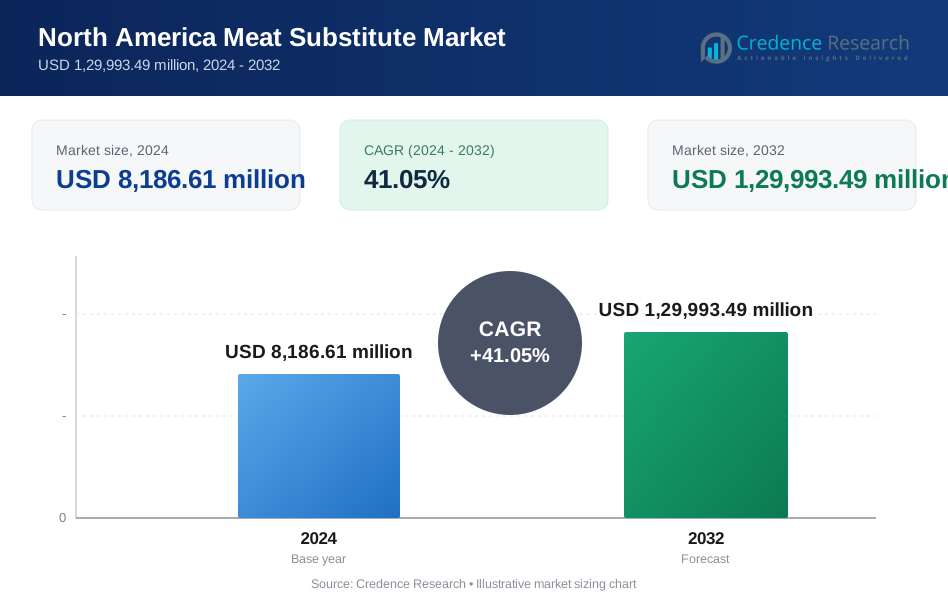
The North America Meat Substitute Market size was valued at USD 2,496.00 million in 2018 to USD 8,186.61 million in 2024 and is anticipated to reach USD 1,29,993.49 million by 2032, at a CAGR of 41.05% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Meat Substitute Market Size 2024 | USD 8,186.61 Million |
| North America Meat Substitute Market, CAGR | 41.05% |
| North America Meat Substitute Market Size 2032 | USD 1,29,993.49 Million |
The market growth is driven by rising consumer awareness of health, sustainability, and ethical food choices. Growing concerns about the environmental impact of animal farming have encouraged demand for plant-based proteins. Rising lactose intolerance and meat-related health risks are pushing consumers toward alternatives. Companies are innovating with advanced technologies to deliver products with better taste, texture, and nutritional profiles. Strong marketing campaigns and partnerships with foodservice outlets are further fueling adoption. Increased availability of meat substitutes across retail and online platforms has expanded consumer access, supporting widespread market acceptance.
The United States dominates the regional landscape due to strong investments in food technology, established retail networks, and consumer openness to sustainable products. Canada is emerging with increasing adoption driven by growing vegan and flexitarian populations. Mexico is showing potential as rising urbanization and awareness of health benefits expand demand. North America’s cultural diversity, combined with a strong focus on innovation, positions the region as a leader in global meat substitute trends, creating opportunities for both established companies and new entrants.
Market Insights:
- The North America Meat Substitute Market was valued at USD 2,496.00 million in 2018, increased to USD 8,186.61 million in 2024, and is projected to reach USD 1,29,993.49 million by 2032, growing at a CAGR of 41.05%.
- The United States held 68% share in 2024, supported by strong retail networks and food technology leadership, while Canada followed with 20% share driven by rising vegan and flexitarian populations, and Mexico accounted for 12% due to increasing urban demand.
- Mexico is the fastest-growing regional market with a 12% share, supported by its young population, urban expansion, and rising awareness of health and sustainability.
- Among products, tofu and tempeh together accounted for 38% share in 2024, highlighting their established cultural acceptance and versatility in consumer diets.
- Quorn and other innovative products showed steady expansion with a combined 27% share, reflecting rising interest in mycoprotein-based and diversified meat substitute offerings.
Market Drivers:
Rising Health Awareness and Changing Dietary Preferences
The North America Meat Substitute Market is driven by increasing awareness of health and nutrition among consumers. Shifting dietary preferences are encouraging individuals to explore plant-based proteins as alternatives to red and processed meats. Concerns over obesity, diabetes, and cardiovascular diseases are pushing people toward healthier food choices. Growing adoption of vegetarian, vegan, and flexitarian lifestyles reflects the region’s evolving consumption patterns. It is witnessing greater acceptance across younger demographics who are highly conscious of long-term well-being. Food producers are focusing on delivering substitutes with enhanced nutritional value. Consumers are prioritizing balanced diets that combine taste with health benefits.
- For instance, Maple Leaf Foods expanded its plant-based protein portfolio with an investment into new production facilities in Indiana, including a $310 million plant-based meat plant, showcasing commitment to serving health-conscious consumers with innovative plant proteins.
Environmental Concerns and Sustainability Goals
Growing concern about the environmental footprint of livestock production is strengthening demand for substitutes. Consumers are becoming more aware of greenhouse gas emissions, deforestation, and water use linked to animal farming. It is benefiting from sustainability-driven policies across the region. Governments and institutions are promoting eco-friendly diets to reduce climate change impact. Food companies are aligning their strategies with corporate sustainability goals to meet consumer expectations. Investments in renewable resources for plant-based products are increasing to support green objectives. Rising eco-conscious consumer behavior is reshaping food habits at scale. This trend positions meat substitutes as sustainable alternatives with long-term appeal.
- For instance, Tyson Foods invested in cultured meat and plant-based alternatives through Tyson Ventures, co-leading a seed funding round of $2.2 million in Future Meat Technologies, advancing affordable, non-GMO cultured meat production that reduces environmental impacts compared to conventional livestock.
Technological Advancements in Product Development
Innovation in food technology is a key driver behind market expansion. Companies are investing in advanced processing techniques that improve the taste and texture of substitutes. Consumers now expect plant-based foods to closely resemble meat in appearance and flavor. It is witnessing a surge in research to enhance protein extraction, fermentation, and cell-based alternatives. Product launches are increasingly highlighting innovation in nutritional composition and functionality. Collaborations with research institutes are enabling better development pipelines. Brands are competing by offering options that replicate traditional meats more authentically. Continuous progress in this space is reinforcing consumer trust and market growth.
Expansion of Distribution Networks and Foodservice Adoption
Distribution and accessibility play a vital role in market development. The North America Meat Substitute Market is expanding through supermarkets, specialty stores, and online channels. It is also gaining traction in restaurants, fast-food chains, and institutional foodservice. Partnerships with leading retail and quick-service outlets are increasing product availability. Consumers prefer convenient purchasing options, which boosts online retail penetration. Growing demand in both urban and suburban markets supports the expansion of distribution networks. Strategic promotions and in-store visibility are enhancing consumer engagement. The availability of substitutes across diverse channels strengthens adoption and sustains long-term growth.
Market Trends:
Shift Toward Clean Label and Natural Ingredients
The North America Meat Substitute Market is experiencing a strong shift toward clean-label products. Consumers prefer substitutes made from natural, non-GMO, and minimally processed ingredients. This trend reflects increasing skepticism toward artificial additives and preservatives in food. Brands are highlighting transparency in sourcing and labeling to gain trust. It is pushing producers to reformulate products with recognizable, simple ingredients. Plant proteins such as pea, soy, and lentils are becoming popular bases. Clean-label positioning appeals to health-conscious shoppers across demographics. This movement strengthens brand credibility and long-term consumer loyalty.
- For instance, in 2023, new plant-based protein powder SKUs globally featured clean-label formulations with five or fewer ingredients, and North American launches particularly emphasized organic and non-GMO claims, with pea protein leading product introductions.
Growth of Hybrid and Blended Product Categories
Hybrid products combining plant-based and traditional meat are creating new growth avenues. Consumers open to reducing meat intake without fully eliminating it find blended options appealing. It is encouraging brands to design products that deliver familiar taste with reduced environmental impact. Hybrid formats allow companies to reach flexitarian consumers who represent a large share of the market. Retailers are dedicating space to blended product launches. Innovation in this space demonstrates adaptability to varied consumer preferences. Blended proteins help balance affordability, nutrition, and flavor. This trend supports expansion beyond niche vegan and vegetarian segments.
- For instance, Tyson Foods launched its 'Raised & Rooted' brand in 2019, offering blended food products combining meat and plant ingredients. By 2020, the brand expanded into Europe’s foodservice sector, signaling increasing retailer support and consumer interest in hybrid meat products.
Premiumization and Diversification of Offerings
The market is witnessing rising interest in premium products with gourmet appeal. Consumers are seeking substitutes that deliver restaurant-quality taste and texture. The North America Meat Substitute Market is responding by diversifying offerings beyond burgers and sausages. Companies are introducing seafood analogs, poultry alternatives, and ethnic-inspired dishes. It is fueling demand for innovation in frozen, chilled, and ready-to-eat segments. Premiumization aligns with affluent consumers who prioritize taste and quality. Brand differentiation is increasingly tied to unique flavors, cooking versatility, and authenticity. This strategy enhances competitive positioning in a growing market.
Integration of Meat Substitutes in Mainstream Food Culture
The adoption of substitutes is extending into mainstream culture. Celebrity endorsements and social media campaigns are amplifying visibility. It is becoming more common to find meat substitutes in everyday meals across households. Foodservice chains are featuring plant-based dishes as core menu items. Retail promotions highlight substitutes as regular pantry essentials. Partnerships with schools, hospitals, and institutional cafeterias are widening exposure. Consumer familiarity has shifted substitutes from occasional novelty to routine food choice. This integration signals a long-term cultural shift toward sustainable dietary practices.
Market Challenges Analysis:
High Production Costs and Pricing Pressures
The North America Meat Substitute Market faces challenges linked to high production costs. Ingredients such as pea protein and soy isolates require advanced processing that adds expense. It is difficult for companies to match the price competitiveness of traditional meat. Consumers often view substitutes as premium items rather than affordable staples. Rising input costs linked to supply chain volatility intensify the challenge. Retailers face hurdles in balancing affordability with profitability. Achieving economies of scale remains a priority for producers. These financial pressures may limit adoption among price-sensitive segments in the region.
Consumer Perception and Taste Acceptance Barriers
Taste, texture, and cultural habits pose significant challenges to growth. Consumers who are used to traditional meat often find substitutes less satisfying. The North America Meat Substitute Market is addressing these issues through continuous innovation. It is investing in research to replicate authentic flavor and mouthfeel. Misconceptions around nutrition and processing methods also hinder adoption. Some consumers perceive substitutes as overly processed, reducing trust. Educational campaigns are necessary to bridge these perception gaps. Overcoming cultural resistance and taste barriers is critical for sustained market penetration.
Market Opportunities:
Rising Adoption of Flexitarian and Younger Consumer Segments
The North America Meat Substitute Market holds opportunities through growing flexitarian lifestyles. Younger consumers are particularly drawn to sustainable and ethical diets. It is benefiting from social influence, with plant-based eating linked to wellness and identity. Expanding product variety increases appeal across different meal occasions. Retailers and foodservice players are actively promoting these products to youth-driven markets. Investment in branding and digital campaigns enhances reach. The region offers significant room to convert occasional buyers into regular consumers.
Innovation in Alternative Protein Sources and Culinary Applications
Future opportunities lie in diversifying protein sources beyond soy and pea. Companies are exploring chickpea, fava bean, algae, and mycoprotein to expand offerings. The North America Meat Substitute Market is opening space for unique flavors and textures. It is also finding applications in baked goods, ready meals, and snacks. Culinary integration across diverse cuisines creates new appeal. Partnerships with chefs and restaurants encourage experimentation and acceptance. This innovation-driven expansion promises to create broader consumer engagement.
Market Segmentation Analysis:
By Type
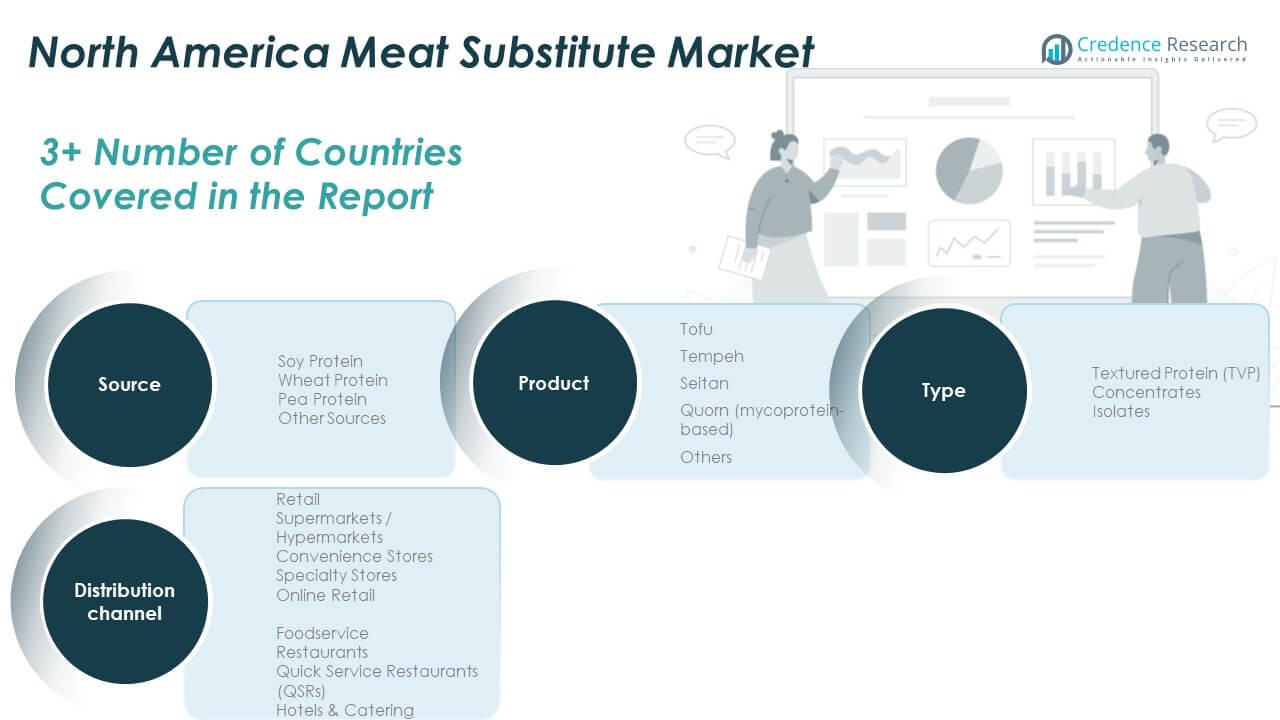
The North America Meat Substitute Market is segmented into textured protein (TVP), concentrates, and isolates. Textured protein dominates due to its wide use in processed foods and meat analogs. Concentrates are gaining traction in snacks and bakery applications. Isolates, known for high purity and protein content, are popular in functional food and beverages. It benefits from increasing demand for versatile protein formats.
- For instance, global production capacity for pea protein isolates reached around 200,000 metric tons in 2021, with North America playing a significant role, reflecting strong adoption of isolate protein formats in diverse food products.
By Source
Soy protein leads the segment because of its established supply base and affordability. Wheat protein attracts demand for its fibrous texture and suitability in bakery applications. Pea protein is expanding rapidly due to allergen-free appeal and sustainability benefits. Other sources, including chickpea and mycoprotein, are building niche opportunities in premium products. It reflects the region’s shift toward diverse protein bases.
By Product
Tofu and tempeh hold strong positions with their established cultural acceptance. Seitan appeals to consumers seeking high-protein, meat-like textures. Quorn, based on mycoprotein, is expanding through innovative launches. Other products, such as nuggets and patties, strengthen presence in mainstream retail and foodservice. It shows diversification beyond traditional soy-based items.
By Distribution Channel
Retail dominates with supermarkets, hypermarkets, and specialty stores offering extensive product ranges. Online retail is expanding quickly, driven by convenience and rising e-commerce adoption. Foodservice is a crucial growth engine, with restaurants and QSRs incorporating plant-based menu items. Hotels and catering are also introducing substitutes to align with consumer preferences. It demonstrates strong adoption across diverse purchasing channels.
Segmentation:
- By Type
- Textured Protein (TVP)
- Concentrates
- Isolates
- By Source
- Soy Protein
- Wheat Protein
- Pea Protein
- Other Sources
- By Product
- Tofu
- Tempeh
- Seitan
- Quorn (mycoprotein-based)
- Others
- By Distribution Channel
- Retail
- Supermarkets / Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Foodservice
- Restaurants
- Quick Service Restaurants (QSRs)
- Hotels & Catering
- By Country
- United States
- Canada
- Mexico
- Retail
Regional Analysis:
United States: Market Leader with Strong Innovation Base
The United States holds the largest share of the North America Meat Substitute Market, accounting for nearly 68% in 2024. Its dominance is driven by advanced food technology, strong retail networks, and consumer openness to sustainable diets. The country has seen rapid product innovation, with startups and established companies investing heavily in R&D. It benefits from widespread adoption across supermarkets, hypermarkets, and foodservice outlets. Growing awareness of environmental sustainability and health-related concerns is fueling demand. Partnerships between leading QSR chains and plant-based brands strengthen consumer reach. The U.S. continues to lead the region’s growth trajectory.
Canada: Rising Adoption Across Retail and Foodservice Channels
Canada accounts for around 20% of the regional market share, supported by growing vegan and flexitarian populations. Canadian consumers are increasingly receptive to plant-based alternatives due to health consciousness and ethical considerations. The retail sector, particularly specialty stores and online platforms, plays a central role in distribution. It is also witnessing significant traction in foodservice, with restaurants and hotels offering diverse plant-based menus. Government support for sustainability and eco-friendly consumption further encourages adoption. Domestic players and international brands are expanding operations to capture growing demand. Canada is positioning itself as an attractive growth hub in the regional landscape.
Mexico: Emerging Market with Expanding Urban Demand
Mexico holds nearly 12% of the regional share and is emerging as a fast-growing market. Increasing urbanization and rising disposable incomes are influencing dietary habits toward healthier and modern food choices. The North America Meat Substitute Market in Mexico benefits from a young demographic keen to explore new diets. It is supported by growing retail infrastructure, including supermarkets and online channels. Foodservice operators are gradually introducing substitutes to align with evolving consumer preferences. Awareness campaigns about nutrition and environmental impact are boosting acceptance. Mexico’s growing demand underscores its potential as a strategic expansion destination.
Key Player Analysis:
- ADM (US)
- Ingredion Incorporated
- DuPont
- PURIS
- Cargill
- Axiom Foods
- MGP Ingredients
- Garden Protein International
- Beyond Meat
Competitive Analysis:
The North America Meat Substitute Market is highly competitive, with global leaders and regional innovators driving expansion. Key companies include ADM, Beyond Meat, Cargill, Ingredion, DuPont, and PURIS, all focusing on diversified product portfolios. It is defined by constant innovation in taste, texture, and nutritional value to meet rising consumer expectations. Partnerships with retail chains and QSRs strengthen brand presence and improve consumer accessibility. Players are leveraging sustainability initiatives, clean-label strategies, and advanced processing technologies to capture market share. Competition is also shaped by mergers, acquisitions, and collaborations that expand distribution networks. The industry remains dynamic with both established firms and startups contributing to rapid growth.
Recent Developments:
- In May 2025, Ingredion emphasized innovations with pea protein and plant-based egg substitutes to address market demands around cost, taste, and nutrition in North America.
Report Coverage:
The research report offers an in-depth analysis based on type, source, product, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising health awareness will continue to boost adoption of substitutes.
- Sustainability goals will drive innovation in low-impact protein sources.
- Hybrid products will expand appeal to flexitarian consumers.
- Retail growth will accelerate through supermarkets and online platforms.
- Foodservice will integrate substitutes into core menu offerings.
- R&D will enhance authenticity in taste, texture, and nutrition.
- Pea protein and alternative sources will diversify market supply.
- Premiumization will attract affluent consumer groups.
- Mexico and Canada will emerge as secondary growth hubs.
- Strategic partnerships will reshape competitive dynamics across the region.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for North America Meat Substitute Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Meat Substitute Market projected to grow between 2024 and 2032?
Which North America Meat Substitute Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America Meat Substitute Market?
Who are the leading companies in the North America Meat Substitute Market?
Which region commanded the largest share of the North America Meat Substitute Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,186.61 million → 2032: USD 1,29,993.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Meat Substitute Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Meat Substitute Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Meat Substitute Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Meat Substitute Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Meat Substitute Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Meat Substitute Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Meat Substitute Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Meat Substitute Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,186.61 million → 2032: USD 1,29,993.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Meat Substitute Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 North America Meat Substitute Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America Meat Substitute Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 North America Meat Substitute Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
