
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market Size 2024 | USD 1,547.18 million |
| North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market CAGR | 7.79% |
| North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market 2032 | USD 2,806.10 million |
Market Overview
North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market size was valued at USD 1,547.18 million in 2024 and is anticipated to reach USD 2,806.10 million by 2032, at a CAGR of 7.73% during the forecast period (2024-2032).
The North America VNA and PACS market is driven by the increasing demand for efficient, interoperable healthcare solutions that streamline medical image management and improve patient care. The growing adoption of electronic health records (EHR) and the shift toward digital healthcare technologies are key factors driving the market. Additionally, advancements in cloud-based storage, along with the need for scalable and vendor-neutral solutions, are accelerating the growth of VNA. The rising prevalence of chronic diseases, an aging population, and the growing volume of medical imaging data further fuel the demand for robust PACS solutions. Furthermore, healthcare providers’ focus on enhancing diagnostic accuracy, reducing operational costs, and ensuring seamless data sharing across platforms are major market trends. As healthcare facilities seek to improve workflow efficiency and integrate multi-vendor systems, the adoption of VNA and PACS technologies is expected to expand significantly in the coming years.
The North America VNA and PACS market is characterized by significant geographical variation, with the U.S. leading the market due to its advanced healthcare infrastructure and adoption of digital health technologies. Canada follows with steady growth driven by government initiatives and a strong focus on interoperable healthcare solutions. Mexico, with its expanding healthcare sector, represents a growing opportunity for VNA and PACS adoption, especially as healthcare modernization continues. Key players in the market include GE Healthcare, IBM Watson Health, and Merge Healthcare (an IBM company), all of which provide advanced imaging solutions and healthcare IT systems. Other notable players include Carestream Health, Change Healthcare, McKesson Corporation, Intelerad Medical Systems, Sectra AB, Agfa HealthCare, and Ambra Health. These companies are at the forefront of technological innovation, offering a range of solutions that improve diagnostic capabilities, data management, and patient care across North America.
Market Insights
- The North America VNA and PACS market was valued at USD 1,547.18 million in 2024 and is expected to reach USD 2,806.10 million by 2032, growing at a CAGR of 7.73% from 2024 to 2032.
- The Global VNA and PACS market was valued at USD 4,411.05 million in 2024 and is expected to reach USD 8,046.15 million by 2032, growing at a CAGR of 7.80% from 2024 to 2032.
- Growing adoption of digital healthcare solutions and electronic health records (EHR) is driving demand for VNA and PACS technologies.
- Cloud-based VNA and PACS solutions are gaining traction due to their scalability, cost-effectiveness, and flexibility.
- The integration of Artificial Intelligence (AI) and Machine Learning (ML) in medical imaging is improving diagnostic accuracy and automation.
- High initial implementation costs and data security concerns are key market restraints.
- The U.S. dominates the market, followed by Canada and Mexico, with significant growth opportunities in Mexico's emerging healthcare sector.
- Key players include GE Healthcare, IBM Watson Health, Carestream Health, McKesson Corporation, and Sectra AB, competing on technology advancements and service offerings.
Report Scope
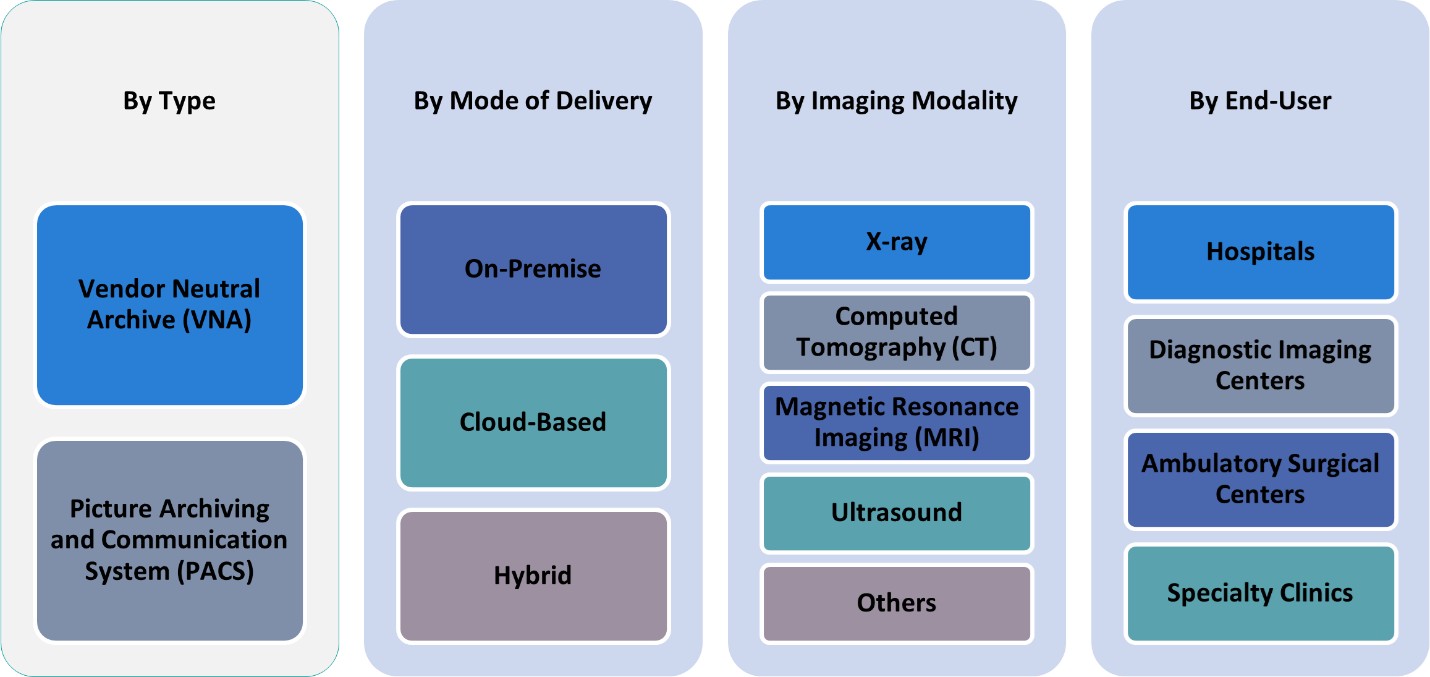
This report segments the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market as follows:
Market Drivers
Focus on Operational Efficiency and Cost Reduction
Healthcare organizations are under constant pressure to improve operational efficiency and reduce costs. VNA and PACS systems contribute significantly to these objectives by streamlining image management workflows and reducing the need for physical storage infrastructure. Traditional imaging systems often lead to inefficiencies in managing, archiving, and retrieving images, resulting in higher operational costs. In contrast, VNA and PACS offer centralized, digital storage that simplifies data access and management, reducing time and resources spent on handling images. For instance, the U.S. Government Accountability Office (GAO) has identified opportunities to improve efficiency and reduce costs in healthcare IT systems, including PACS and VNA adoption. Additionally, these solutions improve diagnostic accuracy and reduce the likelihood of redundant imaging procedures, which can further reduce healthcare costs. As a result, healthcare providers are increasingly adopting VNA and PACS solutions to improve efficiency, cut costs, and enhance patient care, fueling the market’s growth in North America.
Growing Adoption of Digital Healthcare Technologies
The rapid adoption of digital healthcare technologies is a significant driver for the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market. Healthcare organizations are increasingly shifting from paper-based systems to digital solutions for managing medical records and imaging data. The transition to Electronic Health Records (EHR) has created a strong demand for interoperable solutions that can efficiently store, retrieve, and manage medical images across different platforms. VNA and PACS are key components of this digital transformation, enabling seamless storage and sharing of imaging data while enhancing diagnostic capabilities. As healthcare providers move toward integrated digital ecosystems, the need for systems that support interoperability and data access across multiple devices and vendors continues to grow, further propelling the market.
Rising Prevalence of Chronic Diseases and Aging Population
The increasing prevalence of chronic diseases and the aging population are major factors driving the demand for advanced imaging solutions such as VNA and PACS in North America. Chronic conditions such as cardiovascular diseases, diabetes, and cancer require frequent medical imaging to monitor disease progression and guide treatment. As the elderly population grows, the need for diagnostic imaging services is expected to rise, increasing the volume of medical images generated. VNA and PACS systems help healthcare providers efficiently manage, store, and retrieve large quantities of imaging data, ensuring accurate and timely diagnoses. For instance, the Pan American Health Organization (PAHO) warns that rapid population aging has led to an increase in ill health and disabilities caused by noncommunicable diseases, urging countries to prepare their health systems. The growing demand for medical imaging to monitor these chronic conditions fuels the adoption of advanced VNA and PACS solutions, which can handle the growing workload associated with chronic disease management.
Advancements in Cloud-Based Solutions
The integration of cloud-based technologies into the healthcare sector is another major driver influencing the VNA and PACS market. Cloud-based PACS and VNA solutions offer significant advantages over traditional on-premise systems, including scalability, reduced infrastructure costs, and enhanced data security. With cloud storage, healthcare organizations can store large volumes of medical imaging data without the limitations of physical storage infrastructure. Additionally, cloud-based systems enable real-time access to images and patient data, improving workflow efficiency and collaboration among healthcare providers. As cloud computing continues to evolve and become more secure, healthcare institutions are increasingly adopting these solutions to manage imaging data, further driving the adoption of VNA and PACS technologies in the North American market.
Market Trends
Shift Towards Cloud-Based Solutions
One of the significant trends driving the North America VNA and PACS market is the increasing shift towards cloud-based solutions. Healthcare organizations are moving away from traditional on-premise systems to adopt cloud storage for managing medical images and patient data. For instance, government reforms such as the HITECH Act and ACA have encouraged the adoption of cloud-based PACS and VNA solutions to improve healthcare efficiency. Cloud-based VNA and PACS offer advantages such as scalability, reduced infrastructure costs, and greater flexibility. These solutions enable healthcare providers to access and share images securely across multiple locations and devices, enhancing collaboration and improving patient care. The cloud infrastructure also facilitates the storage of large volumes of medical imaging data without the constraints of physical storage, further encouraging the transition to cloud-based systems. As cloud technology continues to advance, it is expected that more healthcare institutions will opt for cloud-based VNA and PACS solutions, driving growth in the market.
Increasing Focus on Interoperability
Interoperability remains a crucial trend in the VNA and PACS market, driven by the need for seamless integration of imaging systems across different vendors, platforms, and healthcare systems. As healthcare providers strive to improve care coordination and streamline patient data sharing, they are increasingly adopting Vendor Neutral Archives (VNA) solutions that can bridge the gap between different imaging systems. For instance, North America is the largest market for VNA and PACS, with government incentives supporting data consolidation and exchange. VNA allows medical imaging data to be stored in a standardized format, enabling access regardless of the vendor of the imaging equipment. This trend towards interoperability not only improves operational efficiency but also enhances the quality of patient care by providing clinicians with a comprehensive view of patient history. The push for more interoperable solutions is gaining traction as healthcare systems move towards integrated, patient-centered care models.
Integration of Artificial Intelligence (AI) and Machine Learning (ML)
The integration of Artificial Intelligence (AI) and Machine Learning (ML) into VNA and PACS systems is an emerging trend that is revolutionizing the medical imaging sector. AI and ML technologies are being incorporated to automate the analysis of medical images, helping healthcare providers detect abnormalities and make more accurate diagnoses. These technologies enhance the efficiency of VNA and PACS systems by automating time-consuming tasks such as image classification and data processing. As AI and ML algorithms continue to evolve, their integration with VNA and PACS is expected to become more advanced, improving diagnostic accuracy and reducing the burden on radiologists and clinicians. This trend is shaping the future of medical imaging by making it more efficient, reliable, and data-driven.
Focus on Enhancing Patient Experience
Another growing trend in the VNA and PACS market is the increasing focus on enhancing the patient experience through improved imaging and quicker diagnosis. Healthcare organizations are adopting more advanced VNA and PACS solutions to improve workflow efficiency, reduce wait times, and enhance the accuracy of diagnoses. By providing clinicians with easy access to comprehensive and up-to-date medical imaging data, these systems enable faster decision-making and more personalized patient care. Additionally, the ability to store and retrieve medical images quickly supports faster diagnosis and treatment planning, which ultimately leads to a better patient experience. As patient satisfaction becomes an increasingly important metric for healthcare providers, the demand for VNA and PACS solutions that optimize workflow and improve care quality is expected to grow.
Market Challenges Analysis
High Implementation Costs
One of the primary challenges facing the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market is the high initial cost of implementation. The setup of VNA and PACS solutions often requires significant investment in both software and hardware infrastructure. Healthcare organizations must account for the costs associated with system integration, data migration, training, and ongoing maintenance. Smaller healthcare facilities or those with limited budgets may struggle to justify the upfront costs of adopting these technologies, even though they offer long-term operational benefits. This financial barrier can delay or hinder the adoption of VNA and PACS solutions, particularly among smaller providers and rural healthcare systems. Consequently, high implementation costs remain a significant challenge for the widespread adoption of these systems across North America.
Data Security and Privacy Concerns
Another challenge for the VNA and PACS market is ensuring the security and privacy of sensitive patient data. As healthcare providers increasingly rely on digital solutions for managing imaging data, the risk of cyberattacks, data breaches, and unauthorized access to medical records grows. For instance, the U.S. Government Accountability Office (GAO) has identified cybersecurity risks in healthcare IT systems, emphasizing the need for stronger data protection measures. VNA and PACS systems store vast amounts of sensitive health information, making them prime targets for malicious activity. Healthcare organizations must comply with strict regulatory requirements, such as the Health Insurance Portability and Accountability Act (HIPAA), to ensure that patient data is protected. The complexity of securing these systems, especially when cloud-based solutions are involved, adds to the challenge. Additionally, concerns about data interoperability between different systems and vendors can further complicate the secure sharing of imaging data across platforms. Ensuring robust security measures while maintaining data privacy and regulatory compliance remains a key challenge for the VNA and PACS market.
Market Opportunities
The North America VNA and PACS market presents several key opportunities driven by ongoing healthcare digitalization and advancements in technology. One significant opportunity lies in the growing demand for cloud-based solutions, as healthcare providers increasingly seek scalable, cost-effective alternatives to traditional on-premise systems. Cloud-based VNA and PACS offer enhanced data storage, easier access to medical images, and the ability to seamlessly share imaging data across multiple healthcare facilities, improving care coordination. This shift to the cloud provides market players with the chance to develop more flexible and secure cloud-based systems that can cater to the evolving needs of healthcare organizations. Additionally, as the volume of medical imaging data continues to grow, there is a strong demand for solutions that offer efficient data management and streamlined workflows, providing opportunities for vendors to innovate and address these needs.
Another key market opportunity exists in the integration of Artificial Intelligence (AI) and Machine Learning (ML) technologies within VNA and PACS solutions. AI and ML can automate image analysis, improve diagnostic accuracy, and reduce the workload of healthcare professionals. Vendors that integrate these advanced technologies into their VNA and PACS offerings have the potential to enhance their value propositions, providing healthcare organizations with tools that not only manage images but also assist in diagnostic decision-making. Additionally, as healthcare providers focus on interoperability to ensure seamless data exchange between systems, there is an opportunity for VNA solutions to facilitate this integration by offering vendor-neutral and standardized formats for image storage. These opportunities highlight the potential for growth and innovation in the VNA and PACS market, as healthcare organizations continue to seek solutions that improve efficiency, accuracy, and patient care.
Market Segmentation Analysis:
By Type:
The North America VNA and PACS market is primarily segmented into two key types: Vendor Neutral Archive (VNA) and Picture Archiving and Communication System (PACS). VNA solutions are increasingly favored for their ability to store medical imaging data in a standardized, vendor-neutral format, enabling healthcare organizations to access and manage images regardless of the system or vendor that produced them. On the other hand, PACS is a more established solution that focuses on the storage, retrieval, and distribution of medical images for diagnostic purposes. PACS solutions enable radiologists and healthcare professionals to access images quickly and efficiently, enhancing diagnostic workflows. The PACS market continues to grow, particularly as healthcare providers upgrade their imaging infrastructure and integrate more advanced technologies such as AI for image analysis. While both VNA and PACS serve similar purposes, the key distinction lies in the flexibility offered by VNA and the specific functionality of PACS tailored to diagnostic imaging. Both segments are essential in modern healthcare facilities, with each meeting different but complementary needs.
By Mode of Delivery:
The VNA and PACS market is further segmented based on the mode of delivery, including on-premise, cloud-based, and hybrid solutions. On-premise solutions have traditionally been the dominant delivery method, where healthcare organizations host their VNA or PACS systems internally on their own servers. These solutions offer control over data management and security, but they come with higher upfront costs and require dedicated IT infrastructure and personnel for maintenance. Cloud-based VNA and PACS solutions eliminate the need for costly on-premise infrastructure and provide healthcare organizations with flexible storage and computing capabilities. This model also allows for seamless data sharing between institutions, improving collaboration and care coordination. The hybrid model, which combines both on-premise and cloud-based solutions, is also growing in popularity. It offers the best of both worlds, allowing organizations to store critical or sensitive data on-premise while utilizing the cloud for scalability and remote access. This trend reflects the growing need for healthcare providers to balance data security, compliance, and operational efficiency while adapting to evolving technological demands.
Segments:
Based on Type:
- Vendor Neutral Archive (VNA)
- Picture Archiving and Communication System (PACS)
Based on Mode of Delivery:
- On-Premise
- Cloud-Based
- Hybrid
Based on End- User:
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
- Specialty Clinics
Based on Imaging Modality:
- X-ray
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Ultrasound
- Others
Based on the Geography:
- U.S.
- Canada
- Mexico
Regional Analysis
U.S.
The U.S. holds the largest market share in the region, accounting for approximately 75% of the total market. This dominance is driven by the country's advanced healthcare infrastructure, widespread adoption of digital health solutions, and large healthcare expenditure. The increasing need for interoperable systems to manage large volumes of medical imaging data has led U.S. healthcare providers to adopt VNA and PACS solutions extensively. Additionally, the strong focus on healthcare digitization, coupled with significant investments in AI and cloud-based technologies, further propels market growth in the U.S.
Canada
Canada holds a smaller yet significant share of around 15% in the North American market for VNA and PACS. The country's healthcare sector is characterized by a high degree of government involvement and a strong emphasis on public healthcare systems. In Canada, there is growing demand for interoperable healthcare solutions that can improve data sharing across provinces and healthcare facilities. As healthcare providers in Canada continue to adopt digital imaging systems, VNA and PACS are gaining traction to support patient-centered care and enhance diagnostic capabilities. The Canadian market is also benefiting from government initiatives promoting digital health solutions, driving the adoption of these technologies in both public and private sectors.
Mexico
Mexico, with its emerging healthcare infrastructure and expanding healthcare market, holds a smaller market share, approximately 10%, in the North American VNA and PACS market. While Mexico's healthcare sector is still developing compared to its North American counterparts, the increasing adoption of digital health technologies and medical imaging solutions is a significant growth driver. Government investments in healthcare modernization, coupled with a growing private healthcare sector, are encouraging the adoption of VNA and PACS solutions. Mexico’s market is expected to experience robust growth as healthcare organizations seek more cost-effective, interoperable solutions to enhance diagnostic capabilities and improve patient care.
Key Player Analysis
- GE Healthcare
- IBM Watson Health
- Merge Healthcare (an IBM Company)
- Carestream Health
- Change Healthcare
- McKesson Corporation
- Intelerad Medical Systems
- Sectra AB
- Agfa HealthCare
- Ambra Health
Competitive Analysis
The North America VNA and PACS market is highly competitive, with several key players leading the innovation and development of imaging solutions. GE Healthcare, IBM Watson Health, Merge Healthcare (an IBM company), Carestream Health, Change Healthcare, McKesson Corporation, Intelerad Medical Systems, Sectra AB, Agfa HealthCare, and Ambra Health are the major players dominating the market. The competition is driven by technological advancements, including the adoption of cloud storage for more flexible and cost-effective data management. Companies are also working to improve the security and privacy of medical data, addressing growing concerns around cybersecurity and compliance with healthcare regulations like HIPAA. In addition to technological innovations, the competition in the market is influenced by the ability to offer seamless integration with existing healthcare systems and equipment. Key competitive factors include service reliability, system performance, and the ability to scale solutions to meet the demands of healthcare providers of all sizes, from small clinics to large hospitals. The market also sees increasing focus on providing tailored solutions that address specific needs in different healthcare sectors, such as radiology, cardiology, and oncology. Companies are investing in expanding their product offerings to enhance patient care and streamline healthcare workflows.
Recent Developments
- In March 2024, at the European Congress of Radiology in Vienna, Philips unveiled new hardware innovations, focusing on integrating artificial intelligence into their imaging solutions to enhance diagnostic accuracy and workflow efficiency.
- In February 2024, FUJIFILM Healthcare Americas Corporation announced that it’s Synapse VNA and Synapse Radiology PACS solutions (in Asia/Oceania) were ranked #1 in the 2024 Best in KLAS Awards: Software and Services. The recognition, based on insights from KLAS Research, highlights companies excelling in improving patient care through their software and services.
- In January 2024, RamSoft (Canada) launched imaging EMR solution, named OmegaAI. The solution is a cloud-native, serverless imaging EMR software platform that consolidates VNA, Enterprise Imaging, PACS, RIS, simplified image exchange/sharing, routing & storage, a zero-footprint (ZFP) viewer, unified worklist, radiology reporting, document management, peer, patient portal, and a real-time business intelligence and analytics solution.
- In November 2023, InsiteOne (US) announced to acquire BRIT Systems cloud native RIS/PACS/VNA solution to advance imaging workflows. This acquisition will continue to focus on developing cost-effective solutions that improve operational productivity while enhancing patient care.
- In July 2023, Fujifilm Sonosite joined the newly formed Medical Imaging Division under the Advanced Medical Technology Association (AdvaMed), collaborating with industry leaders to advance medical imaging technologies.
Market Concentration & Characteristics
The North America VNA and PACS market is moderately concentrated, with a few key players holding significant market share, while several smaller companies offer niche solutions. The market is characterized by intense competition driven by technological advancements, such as the integration of Artificial Intelligence (AI) and cloud-based storage solutions. Leading companies focus on delivering highly interoperable systems that can seamlessly integrate with existing healthcare infrastructures and enhance diagnostic accuracy. These solutions aim to streamline workflow, improve data accessibility, and support better decision-making across healthcare providers. Additionally, the market is witnessing a shift towards vendor-neutral systems, allowing for greater flexibility and reducing dependency on specific vendors. As healthcare organizations increasingly prioritize cost-effective and scalable solutions, the demand for cloud-based VNA and PACS systems is rising. The market’s characteristics also reflect a trend towards offering tailored solutions that meet the diverse needs of various healthcare sectors, ensuring personalized patient care and improved operational efficiency.
Report Coverage
The research report offers an in-depth analysis based on Type, Mode of Delivery, End-User, Imaging Modality and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of cloud-based VNA and PACS solutions is expected to increase as healthcare providers seek scalable, cost-effective, and flexible data management options.
- The integration of Artificial Intelligence (AI) and Machine Learning (ML) will continue to improve diagnostic accuracy and automate routine tasks in imaging systems.
- Demand for vendor-neutral systems will rise, allowing healthcare organizations to reduce dependency on specific vendors and achieve better data interoperability.
- The shift towards integrated healthcare ecosystems will drive further adoption of VNA and PACS solutions that offer seamless integration across multiple platforms.
- Healthcare organizations will increasingly focus on data security and privacy, prompting innovation in secure storage and compliance with regulations like HIPAA.
- The aging population in North America will contribute to the increased need for medical imaging solutions, driving market growth for VNA and PACS.
- Advancements in telemedicine and remote care will increase the demand for VNA and PACS solutions that support remote access to medical imaging data.
- The market will see continued development of hybrid systems that combine on-premise and cloud-based solutions to meet diverse healthcare needs.
- The growing emphasis on patient-centered care will drive the need for more efficient image-sharing capabilities across healthcare networks.
- As healthcare providers seek to optimize operational efficiency, VNA and PACS solutions will play a critical role in reducing costs and improving workflow productivity.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Focus on Operational Efficiency and Cost Reduction
Healthcare organizations in North America are adopting VNA and PACS systems to streamline image management workflows, reduce reliance on physical storage, and cut operational costs. These solutions help minimize redundant imaging and improve diagnostic accuracy, directly supporting cost containment and efficiency goals.
Growing Adoption of Digital Healthcare Technologies
The shift from paper-based to digital systems, especially the widespread implementation of Electronic Health Records (EHR), is fueling demand for interoperable VNA and PACS solutions. These technologies enable seamless storage, retrieval, and sharing of medical images across platforms, supporting integrated digital healthcare ecosystems.
Rising Prevalence of Chronic Diseases and Aging Population
An increasing burden of chronic diseases and a growing elderly population in North America are driving up the volume of medical imaging required for diagnosis and monitoring. This trend necessitates robust, scalable VNA and PACS systems to efficiently manage and access large quantities of imaging data.
Advancements in Cloud-Based Solutions
Cloud-based VNA and PACS offerings are gaining traction due to their scalability, cost-effectiveness, and ability to provide real-time access to imaging data. These solutions reduce infrastructure costs and support collaboration across multiple healthcare facilities, accelerating market growth.
Integration of Artificial Intelligence (AI) and Machine Learning (ML)
The incorporation of AI and ML into VNA and PACS platforms is enhancing diagnostic accuracy and automating routine imaging tasks. This technological advancement is improving workflow efficiency and supporting healthcare providers in delivering faster, more precise patient care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
What factors are driving the growth of the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
What are the key segments within the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
What are some challenges faced by the North America Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Vendor Neutral Archive (VNA)
- 1.2.2 Picture Archiving and Communication System (PACS)
- 1.3 By End-User
- 1.3.1 Hospitals
- 1.3.2 Diagnostic Imaging Centers
- 1.3.3 Ambulatory Surgical Centers
- 1.3.4 Specialty Clinics
- 1.4 By Imaging Modality
- 1.4.1 X-ray
- 1.4.2 Computed Tomography (CT)
- 1.4.3 Magnetic Resonance Imaging (MRI)
- 1.4.4 Ultrasound
- 1.4.5 Others
- 1.5 By Mode of Delivery
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
- 1.5.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,547.18 million → 2032: USD 2,806.10 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Vendor Neutral Archives (VNA) and PACS Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Vendor Neutral Archives (VNA) and PACS Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Vendor Neutral Archives (VNA) and PACS Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Vendor Neutral Archives (VNA) and PACS Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Vendor Neutral Archives (VNA) and PACS Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Vendor Neutral Archives (VNA) and PACS Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 North America Vendor Neutral Archives (VNA) and PACS Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Vendor Neutral Archives (VNA) and PACS Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,547.18 million → 2032: USD 2,806.10 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Vendor Neutral Archives (VNA) and PACS Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vendor Neutral Archive (VNA)
- 12.3.7.2 Picture Archiving and Communication System (PACS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Diagnostic Imaging Centers
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.7.4 Specialty Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Imaging Modality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 X-ray
- 12.5.7.2 Computed Tomography (CT)
- 12.5.7.3 Magnetic Resonance Imaging (MRI)
- 12.5.7.4 Ultrasound
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Mode of Delivery - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Premise
- 12.6.7.2 Cloud-Based
- 12.6.7.3 Hybrid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 North America Vendor Neutral Archives (VNA) and PACS End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Vendor Neutral Archives (VNA) and PACS Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Vendor Neutral Archives (VNA) and PACS Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Vendor Neutral Archives (VNA) and PACS Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GE Healthcare
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 IBM Watson Health
- 18.4 Merge Healthcare
- 18.5 Carestream Health
- 18.6 Change Healthcare
- 18.7 McKesson Corporation
- 18.8 Intelerad Medical Systems
- 18.9 Sectra AB
- 18.10 Agfa HealthCare
- 18.11 Ambra Health
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

