
Biofuel rules and crush capacity set the demand base
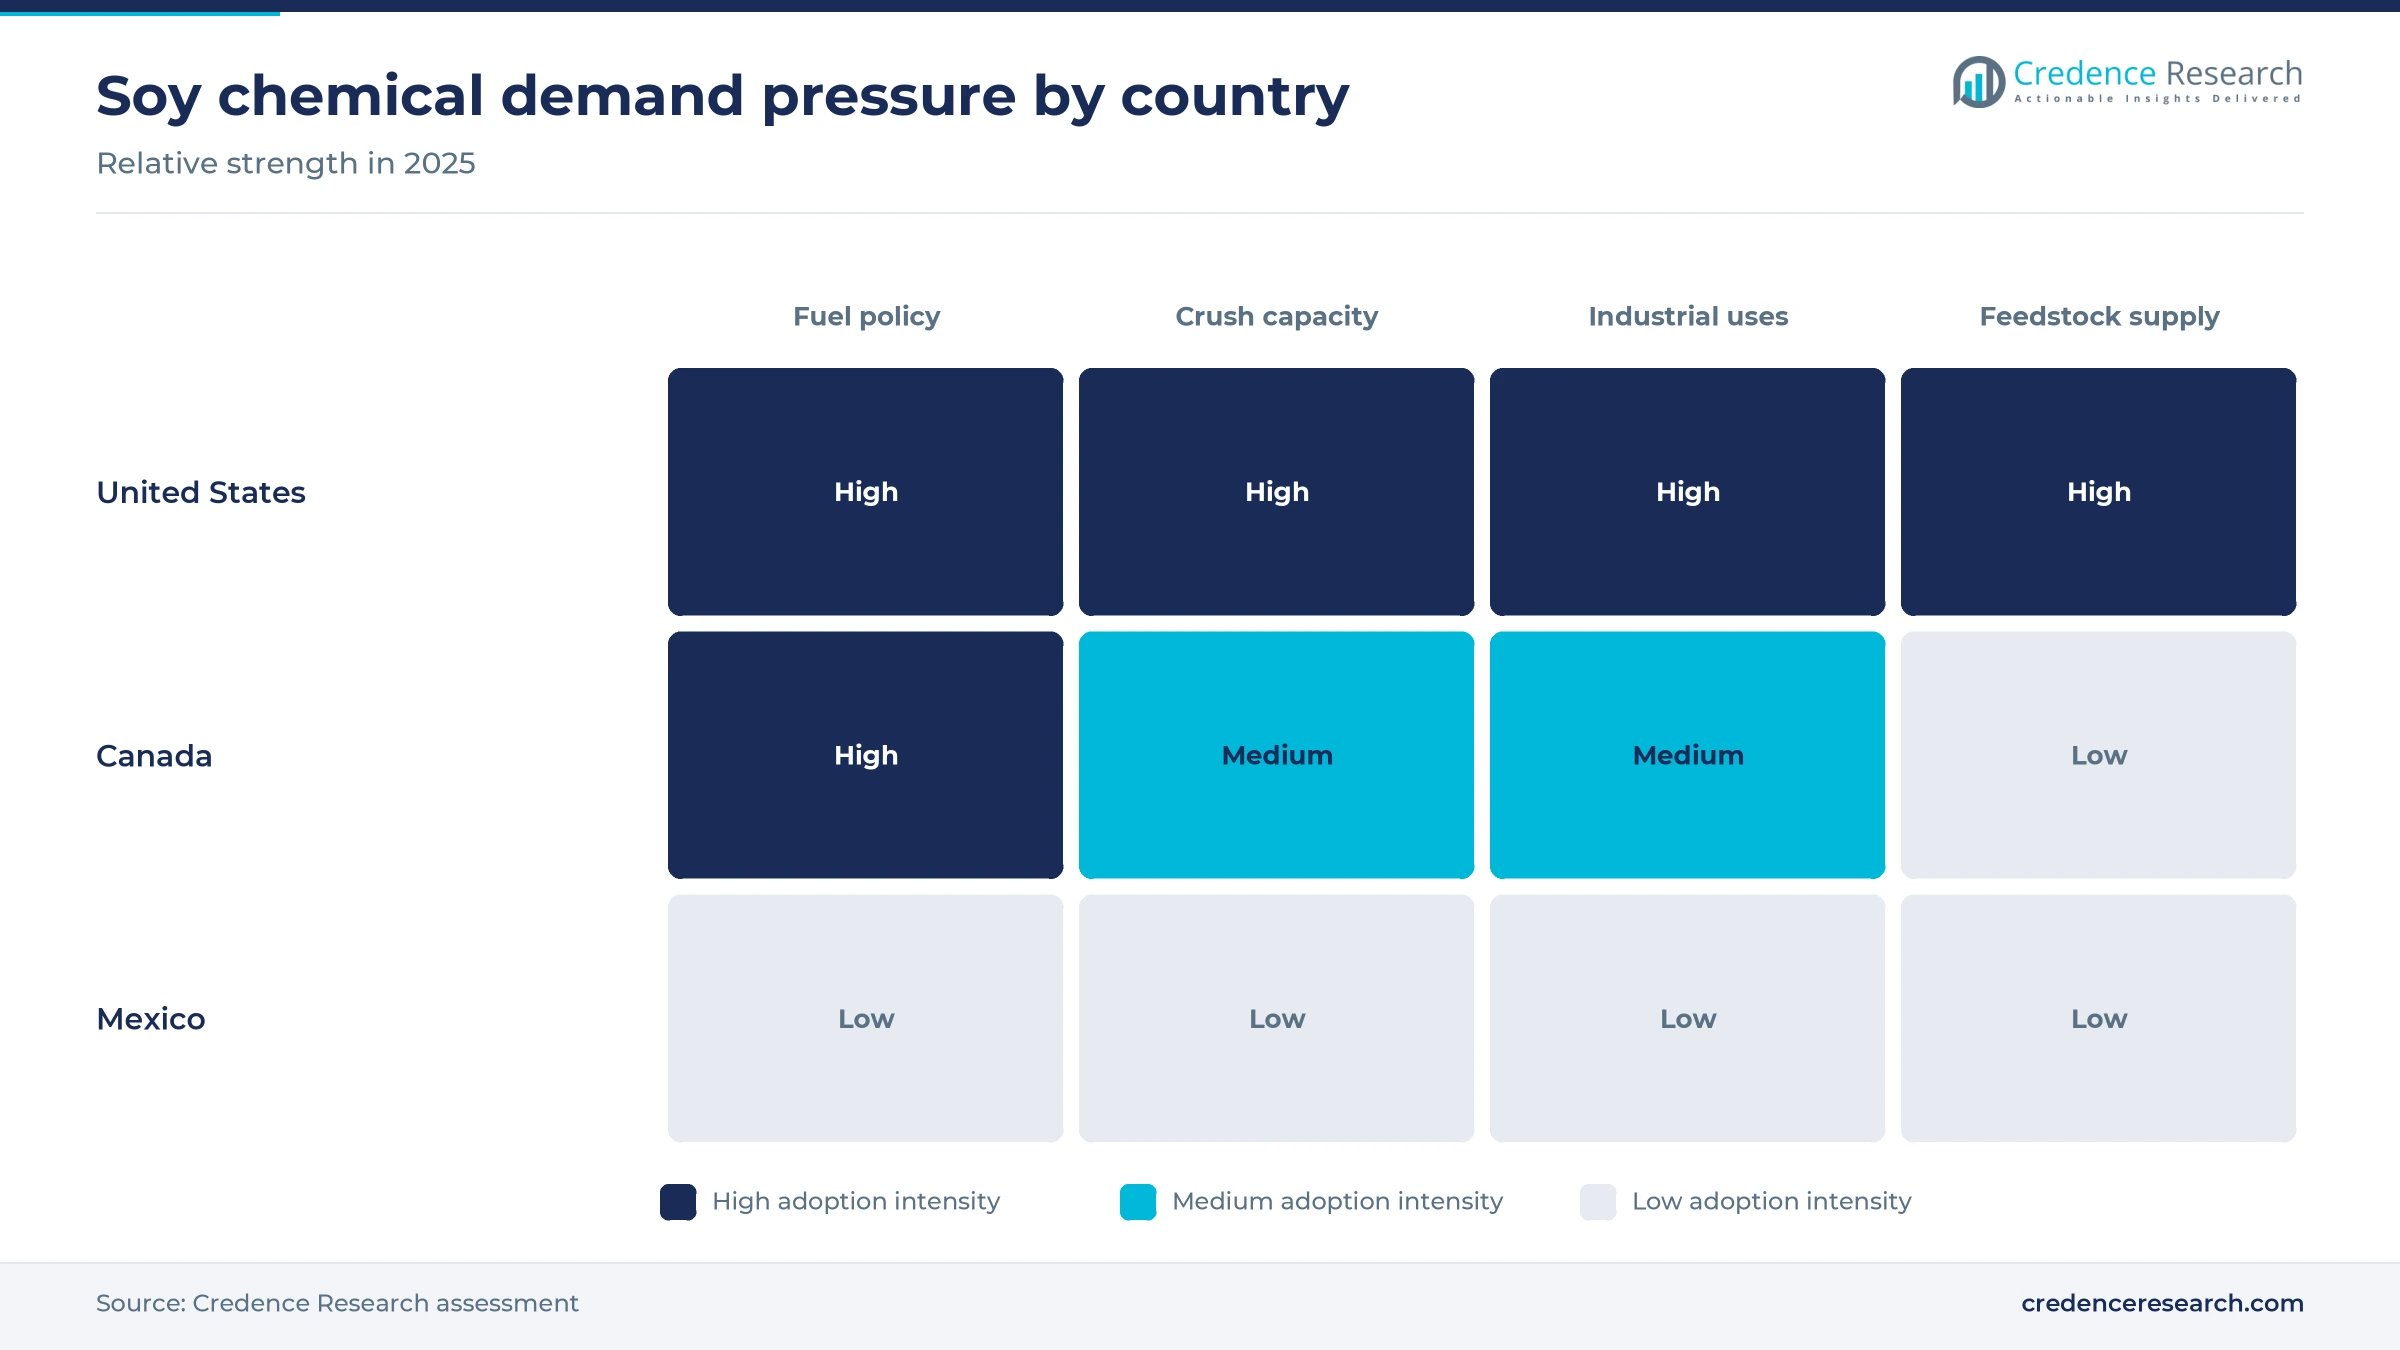
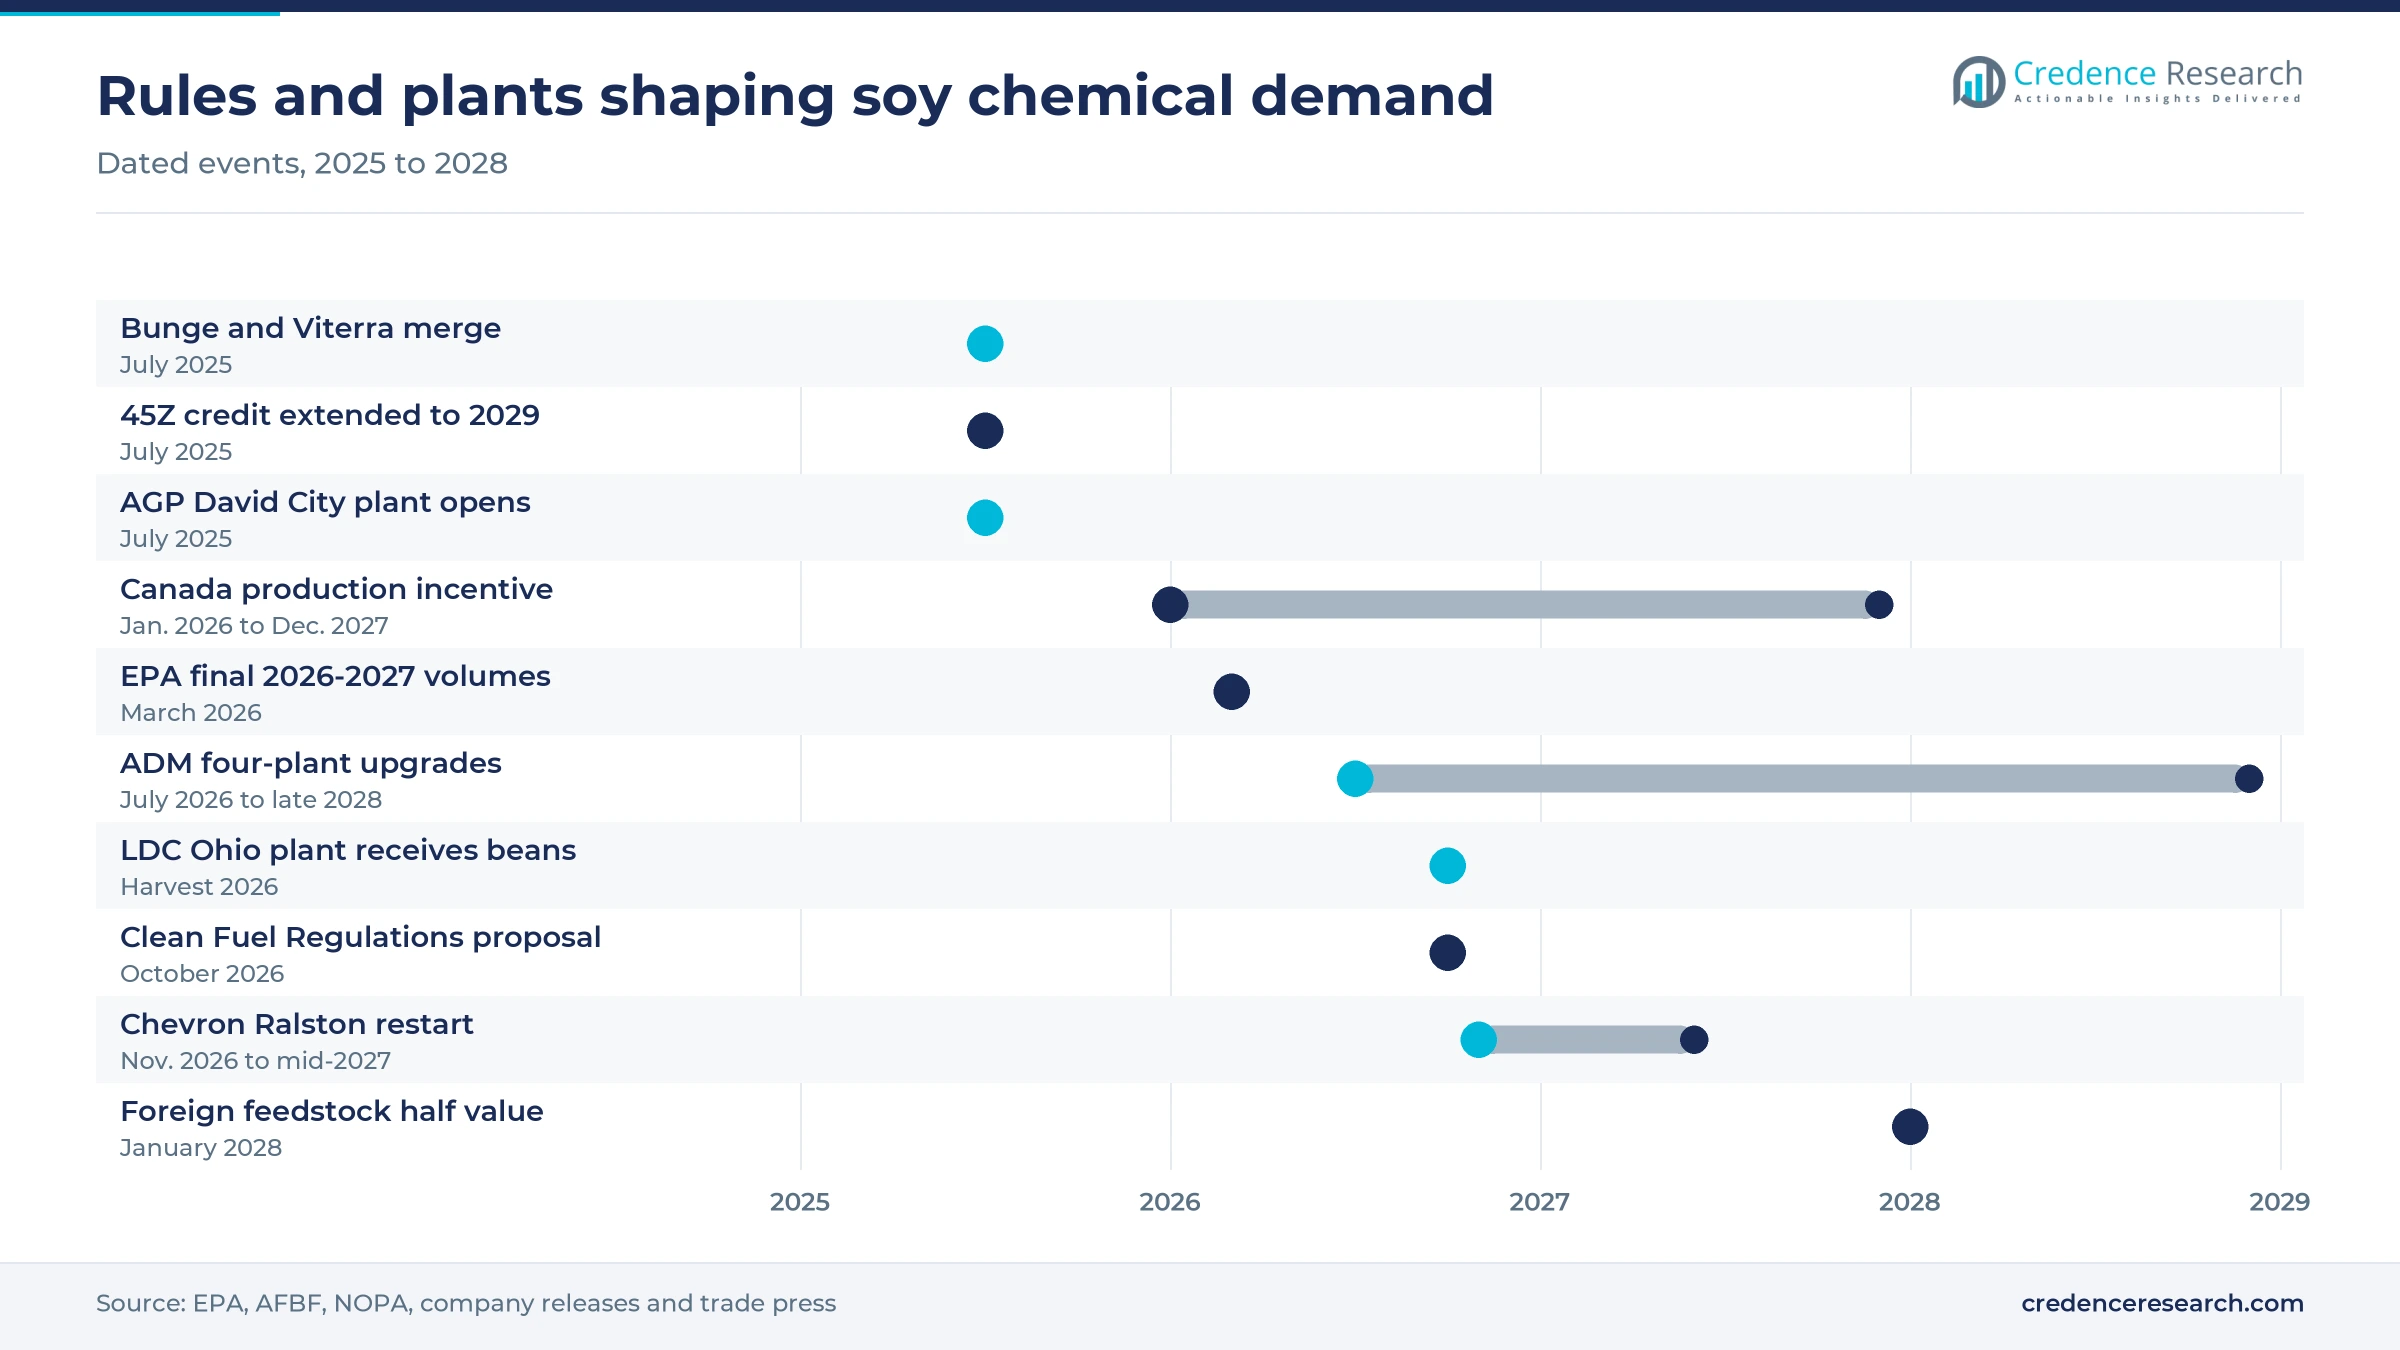
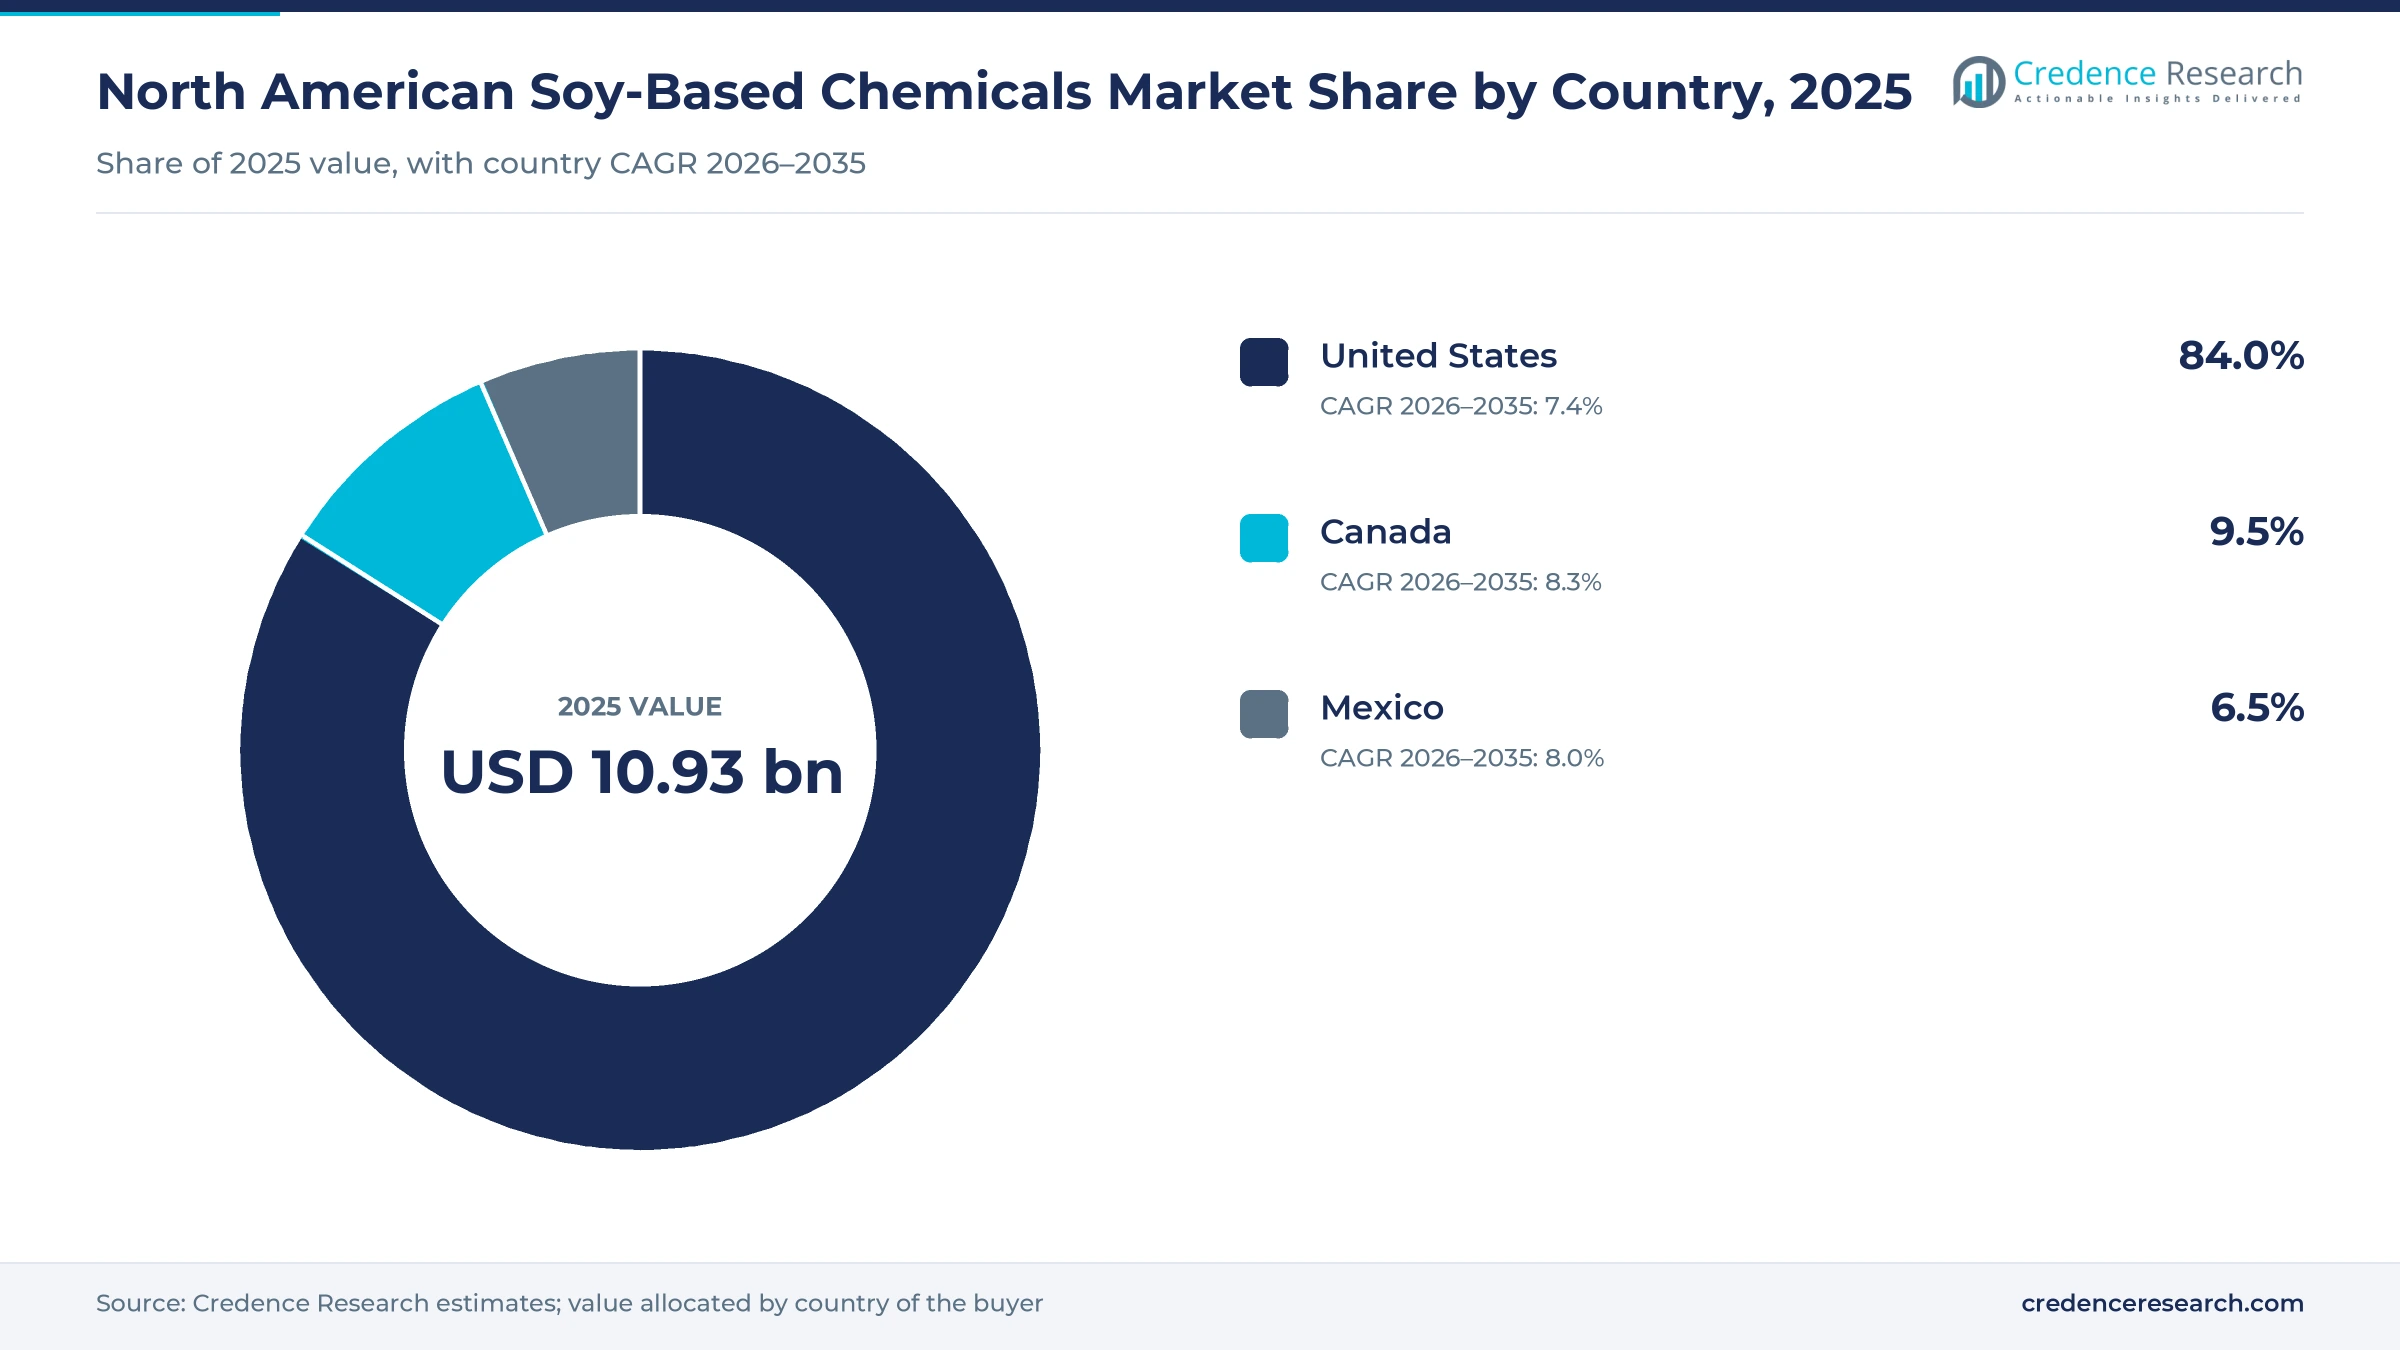
The North American soy-based chemicals market was valued at USD 10.93 billion in 2025 and is projected to increase from USD 11.76 billion in 2026 to USD 22.56 billion by 2035, registering a CAGR of 7.51% during 2026–2035. Demand comes from biodiesel producers, makers of solvents, lubricants, coatings and asphalt additives, polyurethane foam and wood panel manufacturers, and food and personal care formulators that buy lecithin and soy fatty acids. The United States held the largest share, 84.0% in 2025, because it crushes most of the region's soybeans and runs nearly all of its methyl ester capacity. Canada is the fastest-growing country at 8.3% a year, as a federal production incentive supports domestic biodiesel plants through 2027 and Clean Fuel Regulations credits sustain that demand after the incentive ends. Final U.S. renewable fuel volumes for 2026 and 2027 lift the call on soybean oil, while rising oil prices squeeze formulators that compete with petroleum solvents and polyols.
Which soy derivatives and buyers does the estimate count?
The estimate counts soy methyl esters sold as biodiesel or industrial solvent, industrial and chemically modified soybean oils, soy-based polyols, soy-flour adhesives and resins, soy fatty acids and lecithin, and soy wax, valued at the first sale by the producer in the United States, Canada and Mexico.
Hydrotreated renewable diesel, edible bottled oil and soy protein isolates sold as food ingredients sit outside the estimate, although they compete with the same crush output. Large buyers purchase methyl esters and oils on contracts priced off soybean oil futures, while formulated products such as polyols, solvents and lubricants sell on technical data sheets and supply agreements.
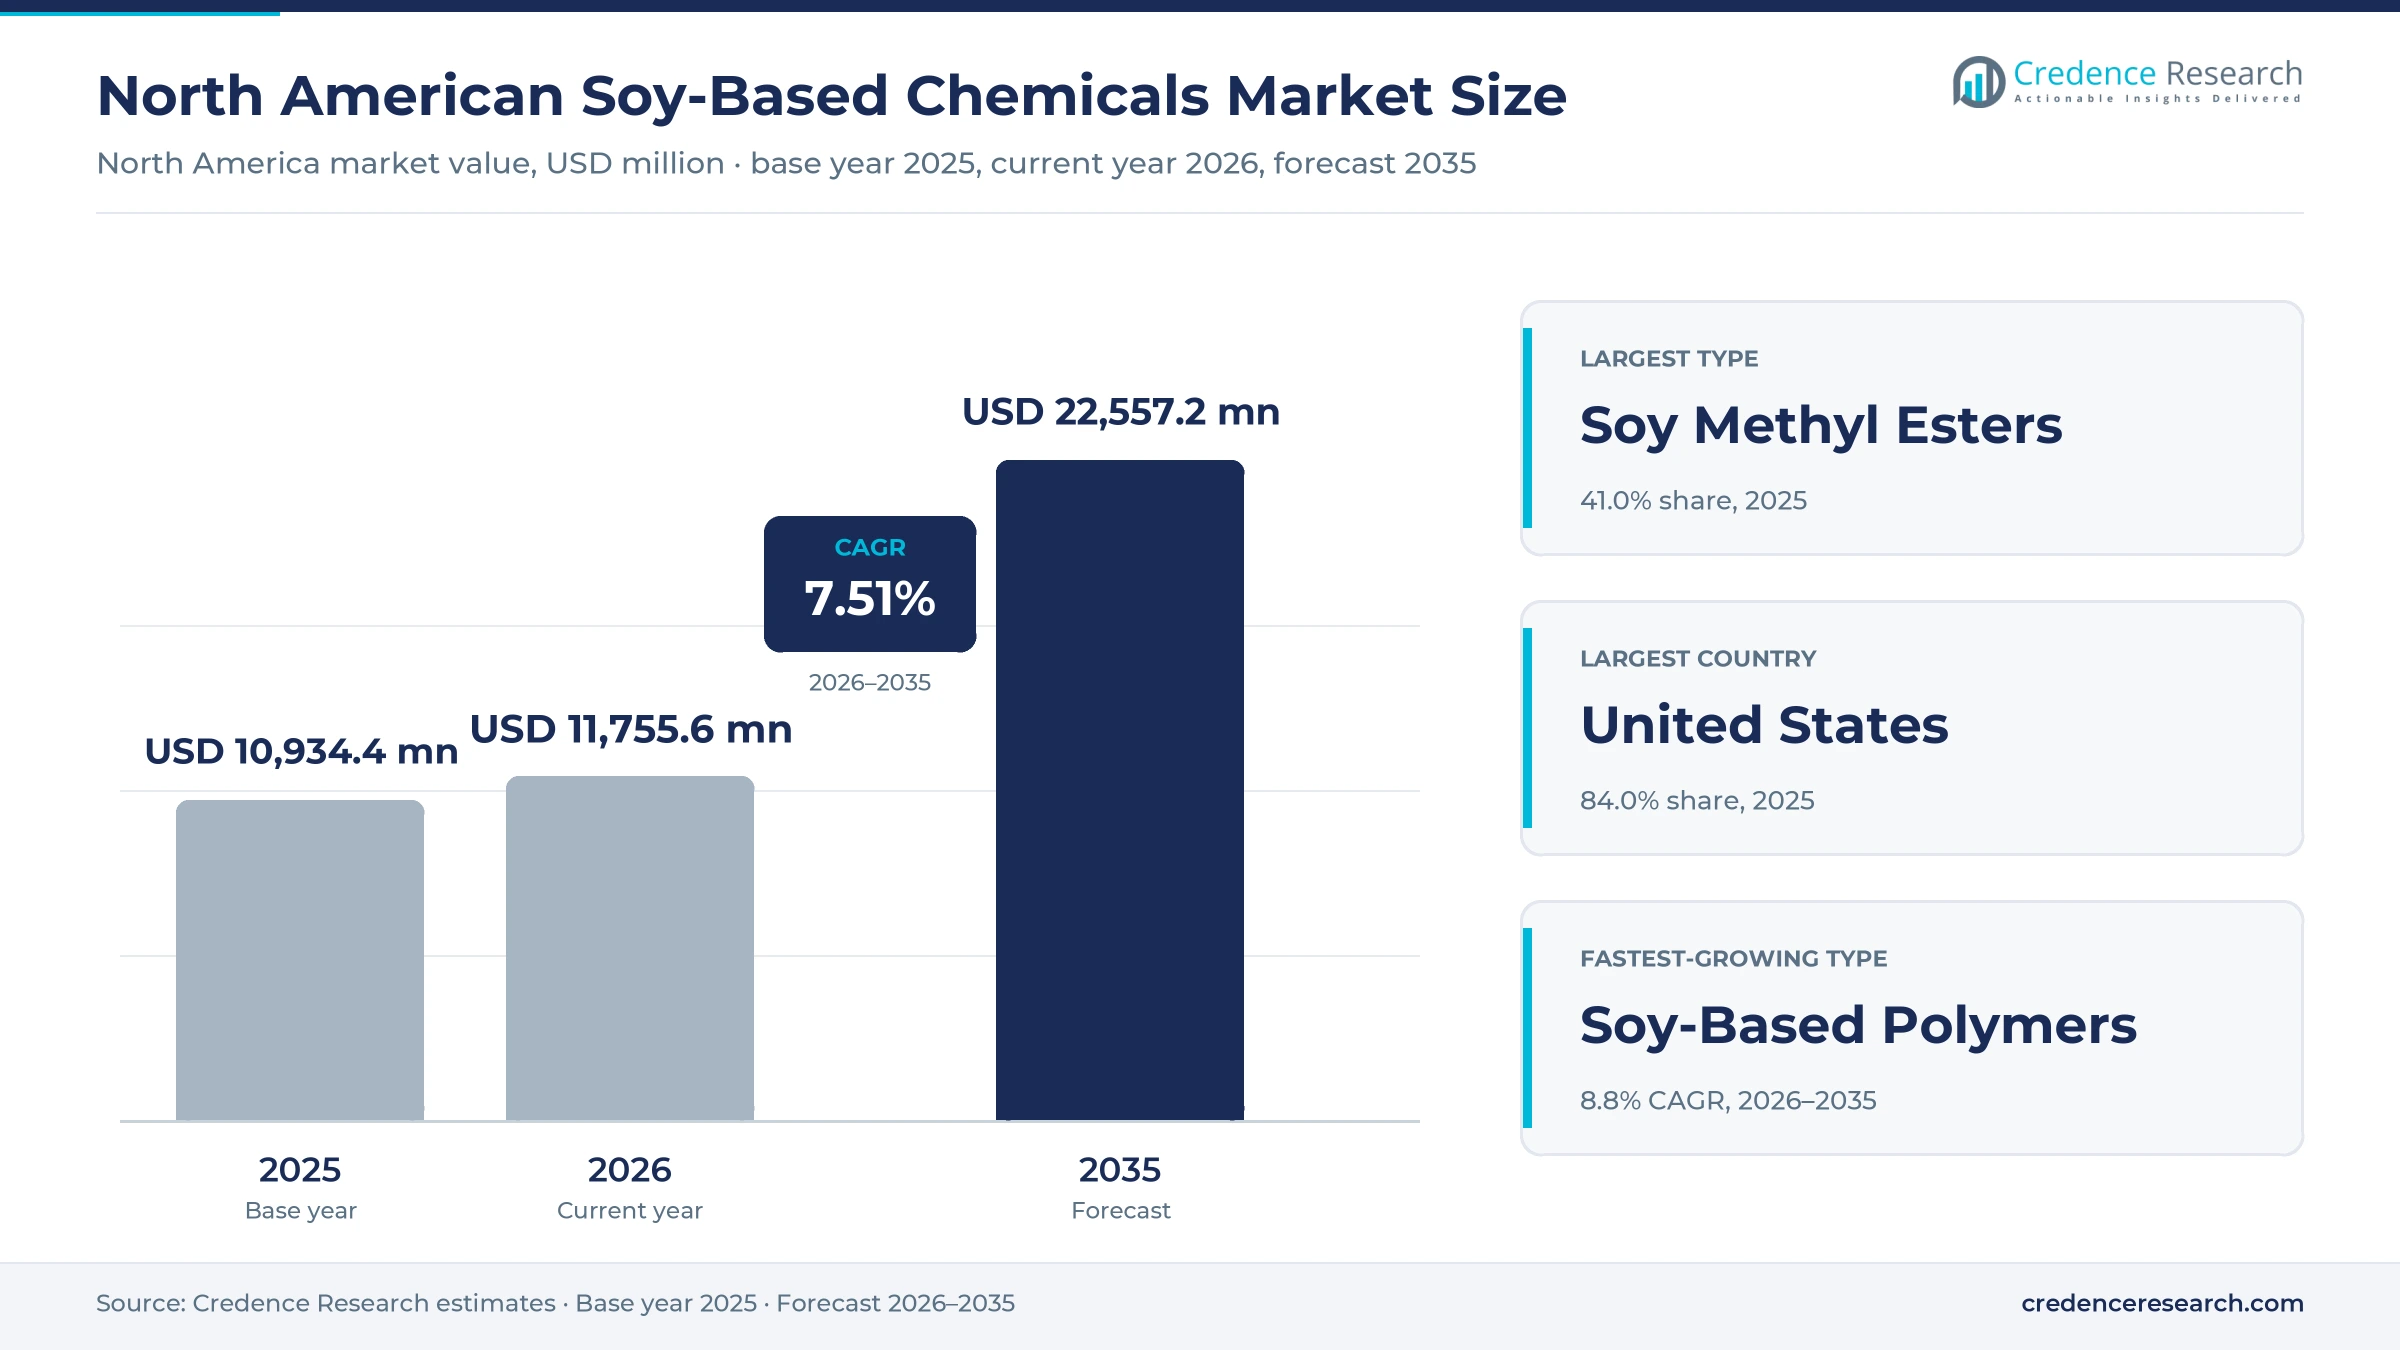
North American Soy-Based Chemicals Market Insights
- The market is valued at USD 10.93 billion in 2025 and is projected to reach USD 22.56 billion by 2035, growing at a 7.51% CAGR as fuel rules and new uses absorb soybean oil.
- The United States led with 84.0% of 2025 value, because it crushes most regional soybeans and holds most methyl ester and polyol capacity.
- Soy Methyl Esters held 41.0% of 2025 value, while Soy-Based Polymers grow fastest at 8.8% a year on foam, adhesive and coating demand.
- EPA finalized biomass-based diesel volumes of 9.07 billion gallons for 2026 and 9.2 billion gallons for 2027 in March 2026.
- ADM announced upgrades at four U.S. soybean plants in July 2026 that add about 700,000 metric tons of annual crush capacity by late 2028.
Methyl esters lead while soy polymers grow fastest
Why do methyl esters lead while soy polymers grow fastest?
Based on type, the market is categorized into soy methyl esters, soy oil, soy-based polymers, soy fatty acids and lecithin, and soy wax. Soy Methyl Esters led with 41.0% of 2025 value because biodiesel plants convert a large part of the soybean oil that USDA expects biofuel makers to use, and AGP also sells SoyGold methyl esters for degreasers and ink removal. Soy-Based Polymers grow fastest at 8.8% a year as foam and panel makers replace petroleum inputs, and Solenis reports more than 150 million hardwood plywood panels made with its formaldehyde-free Soyad soy adhesive.
Why do biofuels lead while industrial uses grow fastest?
Based on application, the market is categorized into biofuels and energy, industrial, food and beverages, cosmetics and personal care, and others, mainly pharmaceuticals and agriculture. Biofuels & Energy led with 44.0% of 2025 value because U.S. biodiesel plants held 1.97 billion gallons a year of capacity on Jan. 1, 2026, according to EIA data. Industrial uses grow fastest at 8.5% a year as solvent, lubricant and asphalt buyers switch, and Stepan sells Steposol SC, a soy and corn ester blend that can replace halogenated cleaning solvents.
Why does transportation lead while construction grows fastest?
Based on end-use industry, the market is categorized into automotive and transportation, construction, packaging, healthcare and others. Automotive & Transportation led with 50.0% of 2025 value because diesel fleets burn blended methyl esters and seat makers use soy polyols, which Cargill says give foam 5% to 20% renewable content. Construction grows fastest at 8.6% a year as road agencies test soy asphalt treatments, and the United Soybean Board named asphalt and concrete among its industrial funding targets, with final decisions in July 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Soy Methyl Esters | 41.0% | Soy-Based Polymers | 8.8% |
| By Application | Biofuels & Energy | 44.0% | Industrial | 8.5% |
| By End-Use Industry | Automotive & Transportation | 50.0% | Construction | 8.6% |
Soybean oil futures set the floor for every derivative
Pricing in this market starts with crude soybean oil, which accounts for most of the cash cost of methyl esters, polyols and wax. Biodiesel buyers pay a spread over soybean oil futures plus credit value under fuel programs, so producer margins swing with credit prices rather than with chemistry. Formulated solvents, polyols and lubricants sell at a premium per pound on technical performance, which lets specialists pass through part of an oil price rise. Suppliers do not publish contract prices for formulated grades, so those ranges are Credence Research estimates.
| Product or reference | Typical price or fee | Basis |
|---|---|---|
| Crude soybean oil, Iowa | 66.93-68.98 cents per pound | USDA Agricultural Marketing Service, Sept. 25, 2026 |
| Soybean oil season-average price, 2025/26 | 55 cents per pound | USDA WASDE, March 2026, reported by the American Soybean Association |
| Soybean oil season-average forecast, 2026/27 | 70 cents per pound | USDA Economic Research Service, October 2026 |
| Soy methyl ester solvent, drum and tote lots | About USD 1.20-2.00 per pound | Credence Research estimate from oil cost, processing and distribution margins |
| Soy polyol for flexible foam, bulk | About USD 1.10-1.70 per pound | Credence Research estimate from oil cost and petroleum polyol parity |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fuel mandates, new crush plants and formaldehyde-free panels
Record fuel mandates raise the call on soybean oil
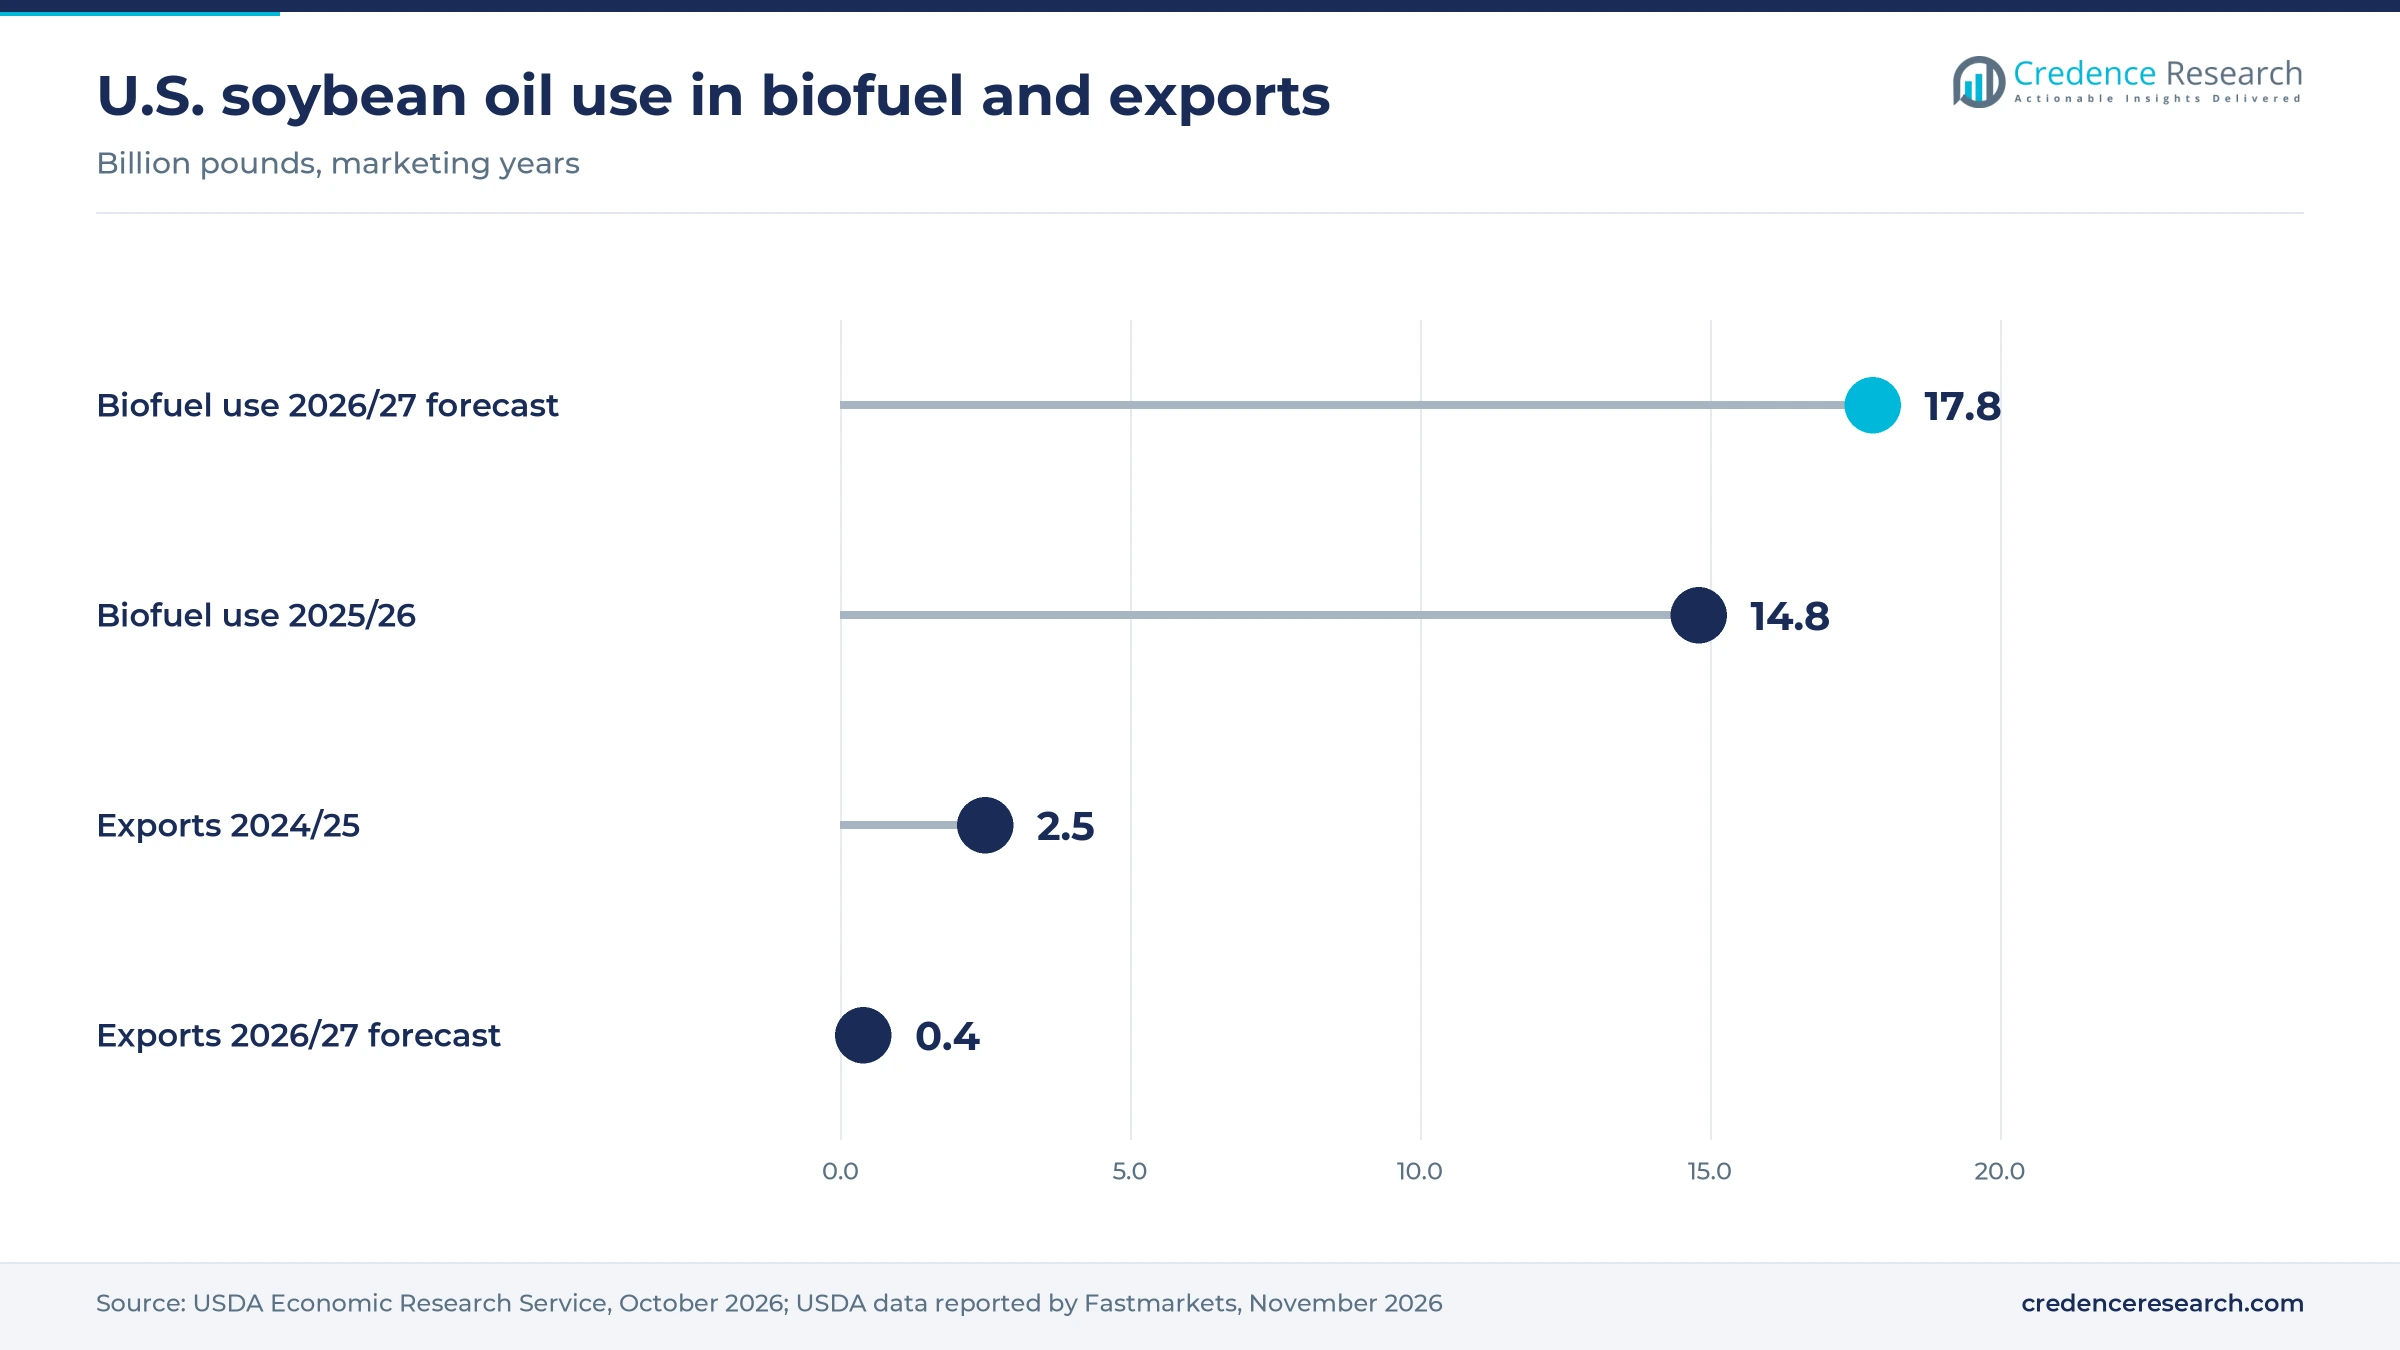
Federal fuel volumes are the largest demand lever, because methyl ester producers need a guaranteed outlet before they contract soybean oil. EPA finalized record renewable fuel standards in March 2026, with biomass-based diesel volumes of 9.07 billion gallons for 2026 and 9.2 billion gallons for 2027, DTN reported. The agency said biodiesel and renewable diesel use must rise more than 60% from 2025 volumes. Soybean oil used for biofuel is forecast at 17.8 billion pounds in 2026/27, up from 14.8 billion pounds in 2025/26, according to the USDA Economic Research Service. Methyl ester plants with secured oil supply gain most, while formulators that buy the same oil face tighter availability as biodiesel output climbs.
New crush plants expand domestic oil supply
New soybean processing capacity widens the feedstock base for every soy derivative, because each plant adds crude oil close to methyl ester, polyol and lecithin producers. Ag Processing Inc. opened a 50 million bushel plant in David City, Nebraska, in July 2025, according to the National Oilseed Processors Association, which cites USD 6 billion of new crushing investment. ADM announced in July 2026 upgrades at four U.S. plants that add about 700,000 metric tons of annual crush capacity by late 2028, citing biofuel policy. The USDA crush forecast for 2026/27 stands at 2.78 billion bushels, which sets the oil supply available for derivative demand. Derivative makers located near these plants gain freight and supply security.
Formaldehyde-free panels and foam pull soy polymers
Wood panel and foam makers adopt soy polymers because buyers and regulators want lower formaldehyde and petroleum content without new equipment. Solenis says its Soyad adhesive combines soy flour with a crosslinking resin, carries 70% to 90% bio-based content and runs at similar press temperatures and times to urea-formaldehyde. Cargill states that every 1 million pounds of its BiOH soy polyols saves more than 2,050 barrels of crude oil in foam for mattresses, furniture, carpet cushion and car seats. Soy feedstock reaches buyers of polyurethane foam through these drop-in grades, which favors suppliers with qualified data sheets.
Federal procurement and checkoff funding support new uses
Public purchasing and farmer checkoff funds lower the cost of moving soy chemistry into industrial products. The USDA BioPreferred program requires federal agencies and their contractors to purchase biobased products within categories identified by USDA, which gives certified soy lubricants and cleaners a federal outlet. Industrial uses still account for only about 5% of soybean demand, a United Soybean Board director said in July 2026, which shows how much room remains outside fuel. Dynamic Green Products makes soy-based lubricants sold under the DeWalt, Craftsman and Mac Tools brands, the Iowa Soybean Association reported. Renewable Lubricants of Hartville, Ohio, said in June 2021 that 80% to 90% of its products use soybean oil. Makers of bio-lubricants and cleaners with BioPreferred labels gain access to federal buyers.
Domestic feedstock rules, solvent swaps and road uses
Fuel buyers shift toward North American feedstock
Fuel producers are shifting toward North American feedstock to keep tax credit value, creating openings for soybean oil and soy methyl esters across Midwest and Canadian plants that also supply renewable diesel refiners. The One Big Beautiful Bill Act extended the 45Z clean fuel credit to fuel sold through Dec. 31, 2029, and limited it to feedstocks from the United States, Mexico or Canada, the American Farm Bureau Federation reported. EPA will give foreign fuels and feedstocks half the compliance value of domestic ones from 2028. Soybean oil supplied only 39.5% of low-carbon feedstock in August 2026, against 50% to 60% in 2020 to 2022, Fastmarkets reported. Crushers integrated with biodiesel plants are best placed to regain share from used cooking oil.
Cleaning formulators shift toward soy ester solvents
Industrial cleaning formulators are shifting toward soy ester solvents to remove hazardous air pollutants and halogenated solvents from degreasers, creating openings for methyl soyate blends across parts washing, graffiti removal and ink cleanup. Vertec BioSolvents of Downers Grove, Illinois, sells Vertec Gold, a patented blend of methyl soyate and corn ethyl lactate, the soy checkoff product directory lists. Stepan lists a 69 C flash point for Steposol SC. The United Soybean Board listed replacement of organic and halogenated solvents among its funding targets in a request for proposals that closed on Jan. 26, 2026, with projects running from Oct. 1, 2026. Formulators that pair soy esters with lactate cosolvents gain, because the blends close the solvency gap with petroleum grades.
Road agencies open a large outlet for soy asphalt agents
Pavement preservation offers a large outlet for soy chemistry, because agencies want longer pavement life and higher recycled asphalt content. About 94% of the 2.8 million miles of U.S. paved roads are surfaced with asphalt, AgriNews reported in July 2026. BioSpan Technologies of Missouri uses soy chemistry to extend asphalt life while incorporating recycled materials, the Iowa Soybean Association reported. A two-lane road uses about 200 bushels of soybeans per treatment, according to the same AgriNews report, so each paving contract moves meaningful volume. Suppliers that win state transportation specifications can lock in multiyear volumes, since agencies rarely change approved products.
Canadian production support opens domestic ester demand
Canada's new production support opens room for domestic methyl ester plants that had lost ground to U.S. and imported fuel. The federal Biofuels Production Incentive took effect on Jan. 1, 2026, with more than CAD 370 million over two years and support on up to 300 million liters per facility, Syngenta Canada reported. Ottawa proposed Clean Fuel Regulations amendments in October 2026 to narrow the competitiveness gap for Canadian low-carbon fuel producers. HOPA Ports and the Mississaugas of the Credit Business Corporation plan to restart a 67 million liter biodiesel plant in Hamilton in late 2026 or early 2027. Soybean growers and crushers in Ontario and Manitoba gain a closer outlet for oil.
Oil price swings, plant closures and import rules weigh
Soybean oil price swings squeeze formulators
Soybean oil prices move with fuel policy, which leaves non-fuel formulators exposed to costs they cannot control. USDA season-average prices in the pricing table show the swing, with the 2026/27 forecast about 27% above the 2025/26 level. Makers of polyols, solvents and wax that sell against petroleum grades are most exposed, because their customers compare prices each quarter. Index-linked contracts and hedging reduce, but do not remove, the margin risk.
Biodiesel plant closures leave idle capacity
Weak biodiesel margins in 2024 and 2025 closed plants and left the industry with idle assets. EIA reported that eight biodiesel plants closed in 2024, removing about 100 million gallons a year, and that three more closed during 2025. Chevron's plant in Ralston, Iowa, has been idled since 2024 and will not return to full output until mid-2027, Farm Progress reported. Small independent producers without crush integration are most exposed when credit prices fall.
Tight oil stocks raise supply risk for buyers
Fuel demand has drawn soybean oil stocks to levels that leave little buffer for industrial buyers. NOPA member stocks fell to 1.05 billion pounds in September 2026, the lowest since 2014, Fastmarkets reported. Soybean oil exports are projected to fall to 400 million pounds in 2026/27 from a record of about 2.5 billion pounds in 2024/25. Lecithin, wax and polyol makers without long-term supply contracts are most exposed during the summer months.
Lower Canadian soybean crops limit local feedstock
Canadian derivative makers rely on a soybean crop that fell sharply in 2025. Statistics Canada estimated 2025 production at about 6.8 million metric tons, down 10.2%, with Ontario down 18.2% to 3.6 million metric tons. Canada now imports about 800,000 metric tons of soybean oil a year, mostly for renewable diesel, The Western Producer reported in March 2026. Eastern Canadian crushers and biodiesel plants are most exposed to crop shortfalls.
United States leads as Canada grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| United States | 9.18 | 84.0% | 7.4% |
| Canada | 1.04 | 9.5% | 8.3% |
| Mexico | 0.71 | 6.5% | 8.0% |
United States leads on crush scale and fuel policy
The United States held 84.0% of 2025 value and grows at 7.4% a year, because it crushes most North American soybeans and holds the methyl ester, polyol and solvent plants. NOPA reports that its 20 members run 73 plants across 20 states and crush more than 2 billion bushels a year. U.S. soybean exports were worth USD 16.46 billion in 2025, the USDA Foreign Agricultural Service reports, so domestic processing still competes with export demand for beans. The fuel volumes and crush expansions noted above keep the country's lead secure.
Canada grows fastest on production incentives
Canada held 9.5% of 2025 value and grows fastest at 8.3% a year, because federal production support and Clean Fuel Regulations credits favor domestic biodiesel and the restart of idle plants. Braya Renewable Fuels has run its 18,000 barrel per day Come by Chance plant since February 2024, which made Canada the world's second-largest soybean oil importer, The Western Producer reported. Manitoba grew its 2025 soybean crop 12.3% to 1.9 million metric tons, which supports western crush supply. Feedstock imports remain the main constraint on Canadian derivative makers.
Mexico grows on food and feed processing
Mexico held 6.5% of 2025 value and grows at 8.0% a year, faster than the regional average from a small base, because food processors that use lecithin and soy oils run largely on imported U.S. beans, while industrial uses are only starting. Mexico bought USD 2.34 billion of U.S. soybeans in 2025, the second-largest market, according to the USDA Foreign Agricultural Service. Mexican soybean consumption is forecast at 8.2 million metric tons on poultry, hog and dairy demand, the Iowa Soybean Association reported in May 2026. Public data on Mexican industrial soy chemical output are thin, so this share carries a wide error range.
Crush plants, fuel rules and restarts mark 2025-2026
| Development | Status and market relevance |
|---|---|
| In July 2025, Ag Processing Inc. opened a soybean processing plant in David City, Nebraska, with 50 million bushels of annual capacity. | Operational launch; the plant adds crude oil supply for methyl ester and oleochemical buyers in the western Corn Belt. |
| In July 2025, Bunge completed its merger with Viterra, combining Bunge's oilseed processing with Viterra's grain origination in Canada and the United States. | Completed transaction; the combined company controls more of the soybean flow from farm to crush plant in North America. |
| In March 2026, EPA finalized Renewable Fuel Standard volumes for 2026 and 2027, with a 70% reallocation of exempted small refinery volumes. | Final rule; the half compliance value for foreign fuels and feedstocks takes effect in 2028, which favors domestic soybean oil. |
| In July 2026, ADM announced capacity upgrades at its Frankfort, Deerfield, Lincoln and Spiritwood soybean plants. | Plan; completion is expected from mid-2028 to early 2029, adding about 25 million bushels of annual soybean demand. |
| In November 2026, Chevron announced a staged restart of its 42 million gallon biodiesel plant in Ralston, Iowa. | Plan; hiring and maintenance come first, with full operation targeted for mid-2027, which adds methyl ester output. |
Esters, polyols and crosslinked soy flour widen uses
- Transesterification of soybean oil with methanol yields methyl esters for biodiesel and for low-odor solvents, with glycerin as a coproduct for other chemical uses.
- Soy polyol synthesis converts soybean oil into hydroxyl-bearing molecules that replace part of the petroleum polyol in flexible foam and carpet backing.
- Crosslinked soy flour adhesives react soy protein with a curing resin to form water-resistant bonds for hardwood plywood and engineered flooring.
- High oleic soybean oil resists oxidation at high temperatures, which suits lubricants, hydraulic fluids and other demanding industrial uses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Crushers own the oil while specialists own formulations
Competition turns on access to crude soybean oil, fuel credit registration and qualification with formulators rather than on branding. ADM, Cargill and Bunge run large crush networks and sell soybean oil, lecithin and industrial derivatives, and Cargill adds BiOH polyols, NatureWax waxes and Anova asphalt products. AGP pairs crushing with SoyGold methyl esters, and Chevron agreed in February 2022 to buy Renewable Energy Group, then the largest U.S. biodiesel producer by volume. Stepan and Vertec BioSolvents compete in soy ester solvents, Solenis leads in soy-flour wood adhesives, and Renewable Lubricants sells more than 250 biobased products, most based on soybean oil. Buyers usually qualify two oil sources but one formulator per product line, which protects specialists. The nine companies profiled below cover crushing, esters, polymers and formulated products.
How is the supply side organized and where do margins sit?
Supply of soy-based chemicals in North America runs in two tiers. Integrated crushers such as ADM, Cargill, Bunge and AGP sell the crude soybean oil that the rest of the chain buys, and they also make methyl esters, lecithin, polyols or wax, which gives them feedstock cost advantages that independents cannot match. A second tier of specialists, including Stepan, Solenis, Vertec BioSolvents and Renewable Lubricants, buys oil or esters and sells formulated products on performance data. Entry barriers sit in crush scale, fuel credit registration and customer qualification. Margins are thin and volatile in biodiesel and highest in formulated adhesives, solvents and lubricants.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Archer Daniels Midland Company | Integrated crusher | Crushes soybeans and sells soybean oil, lecithin, biodiesel and industrial derivatives |
| Cargill, Incorporated | Integrated crusher | Sells soybean oil, BiOH soy polyols, NatureWax plant-based waxes and asphalt agents |
| Bunge Global SA | Integrated crusher | Crushes soybeans and sells soybean oil, lecithin and oil derivatives |
| Ag Processing Inc. (AGP) | Cooperative crusher | Crushes soybeans and sells SoyGold soy methyl ester solvents |
| Chevron Corporation (Chevron Renewable Energy Group) | Methyl ester producer | Produces biodiesel from soybean oil and waste feedstocks at U.S. plants |
| Stepan Company | Specialty chemical maker | Sells Steposol soy and corn ester solvents for industrial cleaners |
| Solenis LLC | Specialty chemical maker | Sells Soyad formaldehyde-free soy-flour adhesives for hardwood plywood |
| Vertec BioSolvents, Inc. | Solvent specialist | Sells Vertec Gold methyl soyate and ethyl lactate solvent blends |
| Renewable Lubricants, Inc. | Lubricant specialist | Sells soybean oil-based hydraulic fluids, gear oils and metalworking lubricants |
Feedstock access, not chemistry, decides margins
Credence Research's view is that feedstock access decides margins in soy-based chemicals more than chemistry does. The crushers that own crude soybean oil capture most of the value from the fuel volumes set for 2026 and 2027, while formulators compete for the same oil at prices set by fuel demand. Specialists can still grow, but they need index-linked supply contracts and products that earn a premium on performance, such as formaldehyde-free adhesives and halogen-free solvents. Buyers should lock in multiyear oil supply before the 2028 feedstock rule tightens the market further.
Earlier estimate rolled forward and tested on soy oil use
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested against soybean oil used for biofuel, typical methyl ester prices and an estimate of non-fuel industrial derivative sales. Country and segment shares are Credence Research estimates based on crush data, biofuel capacity and trade flows. Sources include EPA, USDA, EIA and Statistics Canada data, company product pages and trade press. No interviews or surveys were conducted for this update of the estimate.
Fuel policy and new crush capacity carry growth to 2035
Growth to 2035 depends on how fully fuel volumes are met and on how much new crush capacity comes online. The base case assumes the 2026 and 2027 volumes hold, the new Nebraska plant and ADM's upgrades ramp as planned, and oil prices stabilize after 2027. Within soy-based chemicals, polymers, solvents and asphalt agents should gain share as buyers replace formaldehyde and halogenated chemicals. Canada adds methyl ester output through 2027 under its production incentive, while Mexico stays a food and feed market with modest industrial use.
Fuel credits and oil prices set the range of outcomes
The spread of outcomes depends mainly on how fully refiners meet the 2026 and 2027 fuel volumes and on how much of that demand soybean oil wins back from used cooking oil and tallow. Oil prices also decide whether industrial buyers keep switching from petroleum grades. Weak credit prices or a legal challenge to the fuel volumes would lower growth, while the 2028 feedstock rule and new crush capacity are the main upside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 5.7% | USD 19.38 billion | Fuel credit prices fall and soybean oil stays above 70 cents a pound |
| Base | 7.51% | USD 22.56 billion | Fuel volumes hold, new crush plants ramp as planned and oil prices stabilize |
| Upside | 8.8% | USD 25.13 billion | The 2028 feedstock rule shifts demand to soybean oil and road agencies adopt soy agents widely |
Frequently Asked Questions
How big is the North American soy-based chemicals market?
Which type of soy chemical holds the largest share?
Which country leads the regional soy chemicals market?
Who are the main soy chemical suppliers in North America?
How much soybean oil goes into U.S. biofuel?
What is methyl soyate used for besides fuel?
What restrains the soy-based chemicals market?
How fast do soy-based polymers grow?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Soy Methyl Esters
- 1.2.2 Soy Oil
- 1.2.3 Soy-Based Polymers
- 1.2.4 Soy Fatty Acids & Lecithin
- 1.2.5 Soy Wax
- 1.3 By Application
- 1.3.1 Biofuels & Energy
- 1.3.2 Industrial
- 1.3.3 Food & Beverages
- 1.3.4 Cosmetics & Personal Care
- 1.3.5 Others (Pharmaceuticals, Agriculture)
- 1.4 By End-Use Industry
- 1.4.1 Automotive & Transportation
- 1.4.2 Construction
- 1.4.3 Packaging
- 1.4.4 Healthcare
- 1.4.5 Others
- 1.5 By Country
- 1.5.1 United States
- 1.5.2 Canada
- 1.5.3 Mexico
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 10.93 billion → 2035: USD 22.56 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North American Soy-Based Chemicals Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North American Soy-Based Chemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North American Soy-Based Chemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North American Soy-Based Chemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North American Soy-Based Chemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North American Soy-Based Chemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North American Soy-Based Chemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North American Soy-Based Chemicals Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 10.93 billion → 2035: USD 22.56 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North American Soy-Based Chemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Soy Methyl Esters
- 12.3.7.2 Soy Oil
- 12.3.7.3 Soy-Based Polymers
- 12.3.7.4 Soy Fatty Acids & Lecithin
- 12.3.7.5 Soy Wax
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Biofuels & Energy
- 12.4.7.2 Industrial
- 12.4.7.3 Food & Beverages
- 12.4.7.4 Cosmetics & Personal Care
- 12.4.7.5 Others (Pharmaceuticals, Agriculture)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive & Transportation
- 12.5.7.2 Construction
- 12.5.7.3 Packaging
- 12.5.7.4 Healthcare
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 United States
- 12.6.7.2 Canada
- 12.6.7.3 Mexico
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 North American Soy-Based Chemicals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North American Soy-Based Chemicals Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North American Soy-Based Chemicals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North American Soy-Based Chemicals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cargill, Incorporated
- 18.4 Bunge Global SA
- 18.5 Ag Processing Inc. (AGP)
- 18.6 Chevron Corporation (Chevron Renewable Energy Group)
- 18.7 Stepan Company
- 18.8 Solenis LLC
- 18.9 Vertec BioSolvents, Inc.
- 18.10 Renewable Lubricants, Inc.
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

