
Market Overview
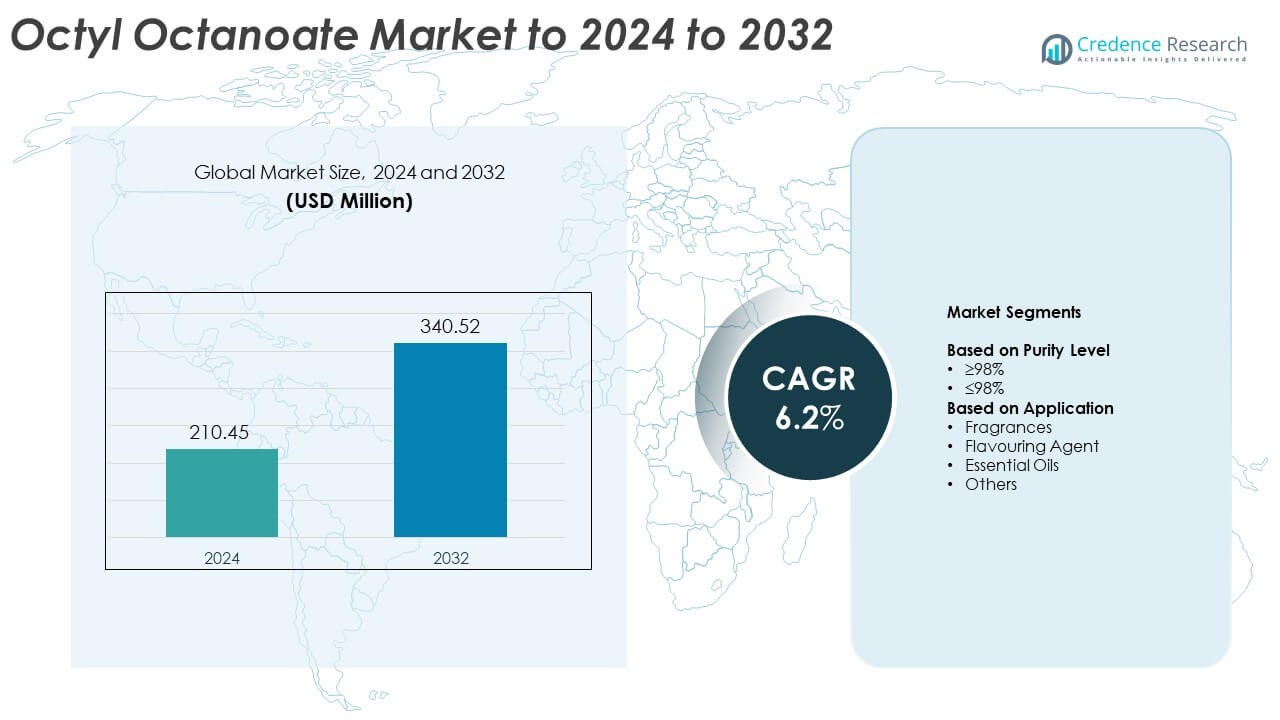
Octyl Octanoate Market size was valued at USD 210.45 Million in 2024 and is anticipated to reach USD 340.52 Million by 2032, at a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Octyl Octanoate Market Size 2024 | USD 210.45 Million |
| Octyl Octanoate Market, CAGR | 6.2% |
| Octyl Octanoate Market Size 2032 | USD 340.52 Million |
The Octyl Octanoate Market is shaped by leading players such as Zschimmer & Schwarz, Stepan Company, Emery Oleochemicals, BASF, Berg + Schmidt GmbH & Co. KG, Croda International Plc, Vantage Specialty Ingredients, and IOI Oleochemical Industries Berhad, all of which compete through high-purity ester production and strong supply capabilities. These companies support key applications in fragrances, flavouring systems, and essential oil blends. North America leads the global market with about 34% share due to advanced formulation industries, while Europe follows with nearly 29% share driven by its mature fragrance and cosmetics ecosystem. Asia Pacific holds close to 25%, supported by expanding personal care manufacturing and rising consumer demand.
Market Insights
- The Octyl Octanoate Market reached USD 210.45 Million in 2024 and is projected to hit USD 340.52 Million by 2032, growing at a CAGR of 6.2%. • Market growth is driven by strong demand from fragrances, which held about 58% share in 2024 due to rising use in premium perfumes and personal care aromas. • High-purity grades show a clear trend shift, with ≥98% purity capturing nearly 63% share as brands prioritize cleaner scent profiles and stable formulation performance. • Competition remains moderate, with companies expanding production efficiency, focusing on high-purity ester development, and strengthening distribution networks to meet increasing global fragrance and flavour demand. • North America leads with nearly 34% share, followed by Europe at around 29%, while Asia Pacific accounts for close to 25% and grows fastest due to rising personal care manufacturing and expanding consumer spending.
Market Segmentation Analysis:
By Purity Level
The ≥98% purity segment leads the Octyl Octanoate Market with about 63% share in 2024 due to its strong suitability for high-grade fragrance and flavor formulations. Manufacturers prefer this segment because high-purity material offers better stability, cleaner aromatic notes, and consistent performance in premium products. The ≤98% category serves cost-focused applications but grows at a slower pace. Rising demand for luxury perfumes and fine aromatic blends continues to push buyers toward ≥98% purity, strengthening its dominance across global production and formulation activities.
- For instance, Givaudan utilizes a sophisticated supply chain involving nearly 3,000 raw material suppliers to manage over 12,400 raw materials for production.
By Application
Fragrances dominate the application segment with nearly 58% share in 2024, driven by strong demand from fine perfumes, body mists, and personal care products. Octyl octanoate supports long-lasting scent profiles and enhances aromatic depth, making it a preferred material for fragrance houses. The flavouring agent and essential oils segments grow steadily as companies expand natural-inspired formulations. Other applications remain smaller but contribute to niche blends. Expanding personal grooming trends and rising consumption of premium fragrance products secure the leadership of the fragrance segment.
- For instance, Symrise manufactures about 35,000 products from around 10,000 raw materials and operates a global network of 36 production sites.
Key Growth Drivers
Rising Demand in Premium Fragrances
Growing consumption of high-end perfumes and personal care aromas drives strong demand for octyl octanoate because the compound enhances scent longevity and provides smooth, floral notes. Global fragrance makers prefer this ester due to its stable performance in both alcohol-based and oil-based formulations. Expanding personal grooming trends, especially in emerging economies, strengthens downstream consumption. Premiumization across beauty and wellness brands further supports steady adoption, making this segment a major driver of market expansion.
- For instance, dsm-firmenich, a leader in nutrition, health, and beauty, invested over €700 million in science and research in 2023 and operates 15 research & development centers globally.
Expansion of the Flavour and Aroma Chemicals Industry
The rapid growth of flavour and aroma chemicals boosts the need for octyl octanoate as companies develop more natural, mild, and consumer-friendly profiles. Food and beverage producers adopt this ester to improve aroma stability and deliver cleaner sensory experiences. Rising demand for processed foods, ready-to-drink beverages, and confectionery products enhances usage across blended flavour systems. Increasing regulatory acceptance of specific esters in controlled concentrations also helps expand commercial opportunities, making this another core driver of market growth.
- For instance, IFF operates a vast global network with approximately 150 manufacturing facilities, creative centers, and application laboratories across around 40 countries.
Increasing Use in Essential Oils and Aromatherapy Products
The wellness industry expands steadily, raising demand for essential oil blends used in diffusers, massage oils, and therapeutic products. Octyl octanoate supports smooth aromatic transitions and enhances overall formulation stability, making it a valued ingredient. Growing consumer preference for mood-enhancing products and natural lifestyle solutions strengthens product formulation pipelines. The rise of spa therapy chains and home aromatherapy adoption contributes to sustained demand, cementing this category as a key growth driver.
Key Trends and Opportunities
Shift Toward High-Purity Ester Grades
Producers increasingly focus on ≥98% purity because premium aroma and flavour applications require consistent performance and clean olfactory profiles. High-purity grades support better compatibility with complex formulations and align with rising quality standards across cosmetics and food sectors. Companies investing in advanced purification technology gain stronger positions in supply chains. This shift creates opportunities for manufacturers to introduce improved product lines and strengthen relationships with global fragrance houses.
- For instance, BASF operates a global production network for its aroma ingredients business, including a world-scale integrated site in Kuantan, Malaysia. The company has a total global annual production capacity for citral of approximately 118,000 metric tons (following the completion of new plants after 2026).
Growth of Natural and Clean-Label Formulations
The clean-label movement influences product development as brands reduce harsh solvents and synthetic additives. Octyl octanoate benefits from its mild, nature-aligned profile, offering an attractive option for formulators in cosmetics, flavours, and essential oils. Consumer interest in plant-based and minimally processed products accelerates innovation in aroma blends. This trend creates space for suppliers to expand portfolios targeting sustainable and eco-friendly formulations, generating new commercial pathways.
- For instance, the Takasago Group operates a global network of offices, production sites, and R&D centers in 28 countries and regions. As of December 2024, the scope of their environmental certification was expanded to include 21 domestic and overseas production sites and the Corporate R&D Division in Japan.
Rising Adoption in Niche Personal Care Segments
Smaller personal care categories like artisanal fragrances, aromatherapy candles, and botanical skin-care blends increasingly incorporate octyl octanoate for its smoothing aromatic character. These niche markets grow rapidly through online channels and premium boutique brands. The shift toward handcrafted and small-batch products boosts demand for versatile, high-quality esters. Manufacturers that supply flexible product grades and small-volume solutions gain strong entry points into these emerging opportunities.
Key Challenges
Fluctuating Raw Material Availability
Unstable availability of feedstock chemicals used in ester production creates periodic supply tightness. Variability in petrochemical and natural alcohol supply affects production consistency and drives cost pressures for formulators. Manufacturers face challenges in maintaining stable pricing for end users during volatility. This issue also influences long-term planning for fragrance and flavour producers who depend on predictable input quality.
Regulatory Compliance Across Multiple End-Use Sectors
Aroma and flavour ingredients face stringent regional regulations covering safety limits, purity standards, and acceptable usage categories. Meeting these diverse guidelines increases compliance costs for producers and slows product approvals. Differences between cosmetic, food, and aromatherapy regulations require detailed documentation and testing. These constraints pose challenges for companies aiming to expand into new markets while maintaining consistent formulation standards.
Regional Analysis
North America
North America holds around 34% share of the Octyl Octanoate Market in 2024, driven by strong demand from premium fragrance brands, personal care manufacturers, and established flavouring companies. The region benefits from advanced production capabilities and high adoption of high-purity aroma chemicals. Growth remains steady due to rising consumer spending on luxury perfumes and wellness products. Expanding aromatherapy use and clean-label formulation trends also support wider adoption. The presence of major formulators and well-structured distribution networks keeps North America a leading contributor to overall market growth.
Europe
Europe accounts for nearly 29% share of the Octyl Octanoate Market in 2024, supported by its mature fragrance and flavouring industries. The region hosts several global perfume houses and food ingredient manufacturers, which drives sustained consumption of high-purity octyl octanoate. Increasing regulatory focus on quality and safety encourages producers to use stable and compliant aroma esters. Demand also rises due to growth in natural cosmetic formulations and essential oil blends. Ongoing investments in R&D, sustainability programs, and premium product innovation help maintain Europe’s strong market position.
Asia Pacific
Asia Pacific holds about 25% share of the Octyl Octanoate Market in 2024 and remains the fastest-growing region due to its expanding personal care, fragrance, and food processing sectors. Countries such as China, India, Japan, and South Korea experience rising demand for fine fragrances, aromatherapy products, and flavored beverages. Increasing urbanization and rising disposable income strengthen consumption across mass and premium categories. Regional manufacturers also scale production of aroma chemicals, improving supply availability. Growing investments in cosmetic ingredient manufacturing support continued growth in the octyl octanoate segment.
Latin America
Latin America represents around 7% share of the Octyl Octanoate Market in 2024, with demand largely driven by expanding personal care and fragrance industries in Brazil, Mexico, and Colombia. The region shows growing interest in aromatherapy products and natural-styled cosmetic formulations. Local brands increasingly adopt octyl octanoate to enhance fragrance stability and improve product sensory appeal. Market growth is supported by rising middle-class spending on grooming and wellness. However, slower industrial development compared to major regions moderates long-term expansion, keeping Latin America a mid-tier contributor.
Middle East and Africa
Middle East and Africa hold close to 5% share of the Octyl Octanoate Market in 2024, supported by rising demand for fine fragrances, particularly in Gulf countries with strong perfume cultures. Growth is also influenced by expanding cosmetic manufacturing and increasing acceptance of aromatherapy products across urban areas. Regional import dependence remains high, but new investments in personal care and wellness sectors create opportunities for higher consumption. Market expansion continues at a moderate pace due to limited local production capacity and varying regulatory frameworks across countries.
Market Segmentations:
By Purity Level
- ≥98%
- ≤98%
By Application
- Fragrances
- Flavouring Agent
- Essential Oils
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Octyl Octanoate Market includes Zschimmer & Schwarz, Stepan Company, Emery Oleochemicals, BASF, Berg + Schmidt GmbH & Co. KG, Croda International Plc, Vantage Specialty Ingredients, and IOI Oleochemical Industries Berhad. The market features a mix of global oleochemical producers and specialized aroma-chemical suppliers that focus on consistent purity levels, reliable raw material sourcing, and scalable production capabilities. Competitors enhance their positions by investing in efficient esterification processes, strengthening distribution partnerships, and expanding portfolios aligned with fragrance, flavour, and essential oil applications. Many companies emphasize high-purity grades to meet the rising demand for premium formulations across cosmetics and personal care products. Strategic activities include upgrading manufacturing technologies, improving sustainability practices, and intensifying research efforts to support clean-label and natural product development. Growing regional demand, especially in Asia Pacific, encourages players to expand supply chains and increase capacity to secure long-term competitiveness in the global market.
Key Player Analysis
- Zschimmer & Schwarz
- Stepan Company
- Emery Oleochemicals
- BASF
- Berg + Schmidt GmbH & Co. KG
- Croda International Plc
- Vantage Specialty Ingredients
- IOI Oleochemical Industries Berhad
Recent Developments
- In 2025, Emery Oleochemicals announced a technical presentation and exhibition at the STLE 2025 Annual Meeting, focusing on sustainable innovations in ester base stocks and additives.
- In 2025, Vantage announced the launch of four new personal care ingredients at the in-cosmetics global tradeshow, illustrating their ongoing innovation in personal care chemicals, likely including Octyl Octanoate-related formulations or derivatives as part of their specialty ingredients portfolio.
- In 2023, BASF introduced a proprietary process for producing 2-octyl acrylate (2-OA), a related C8-based monomer, as part of its expansion of bio-based monomers portfolio.
Report Coverage
The research report offers an in-depth analysis based on Purity Level, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily as fragrance and personal care demand increases.
- High-purity grades will gain wider adoption across premium formulations.
- Flavouring applications will expand with rising processed food consumption.
- Aromatherapy and essential oil blends will drive stronger usage in wellness products.
- Manufacturers will invest in advanced purification technology to improve consistency.
- Clean-label and natural formulation trends will open new commercial opportunities.
- Asia Pacific will continue to grow fastest due to expanding cosmetic industries.
- Regulatory clarity will improve product approvals and streamline global trade.
- Supply chain optimization will reduce volatility in raw material availability.
- Niche personal care brands will boost demand through small-batch and artisanal products.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Octyl Octanoate Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Octyl Octanoate Market projected to grow between 2025 and 2032?
Which Octyl Octanoate Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Octyl Octanoate Market?
Who are the leading companies in the Octyl Octanoate Market?
Which region commanded the largest share of the Octyl Octanoate Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Octyl Octanoate Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Octyl Octanoate Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 210.45 Million → 2032: USD 340.52 Million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Octyl Octanoate Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Octyl Octanoate Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Octyl Octanoate Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Octyl Octanoate Market Drivers
- 3.3 Octyl Octanoate Market Restraints & Challenges
- 3.4 Octyl Octanoate Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Octyl Octanoate Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Octyl Octanoate Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Octyl Octanoate category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Octyl Octanoate Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Octyl Octanoate Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Octyl Octanoate. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Octyl Octanoate Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Octyl Octanoate Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Octyl Octanoate Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Octyl Octanoate (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Octyl Octanoate
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Octyl Octanoate Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Octyl Octanoate Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Octyl Octanoate Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Octyl Octanoate Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Octyl Octanoate Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Octyl Octanoate Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Octyl Octanoate Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Octyl Octanoate Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
