
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Optical Sensor Market Size 2024 | USD 25,553.07 million |
| Optical Sensor Market, CAGR | 11.38% |
| Optical Sensor Market Size 2032 | USD 60,238.46 million |
Market Overview
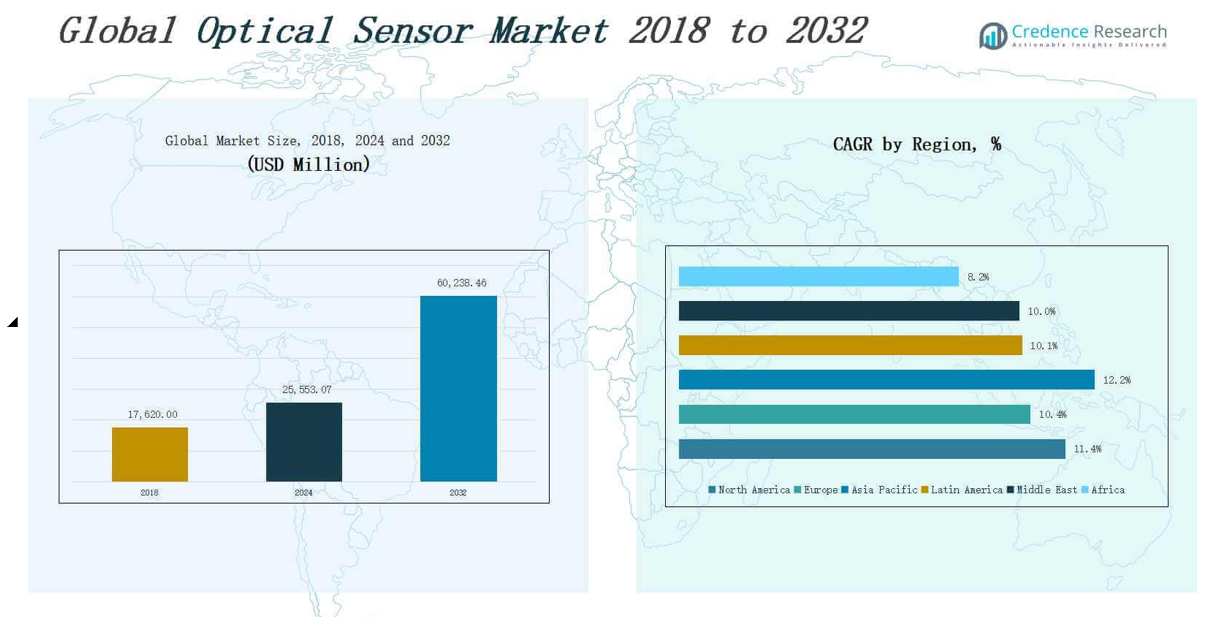
The Optical Sensor Market size was valued at USD 17,620.00 million in 2018 to USD 25,553.07 million in 2024 and is anticipated to reach USD 60,238.46 million by 2032, at a CAGR of 11.38 % during the forecast period.
The Optical Sensor Market is experiencing strong growth driven by increasing demand for high-precision sensing technologies across diverse applications such as industrial automation, consumer electronics, automotive safety systems, and healthcare diagnostics. Rising adoption of smart devices and IoT infrastructure has fueled the need for compact, energy-efficient, and accurate sensors capable of detecting light, distance, motion, and environmental changes. In the automotive sector, the integration of optical sensors into advanced driver-assistance systems (ADAS) and autonomous vehicles supports enhanced situational awareness and safety. Meanwhile, the growing use of wearable health monitors and non-invasive diagnostic tools is expanding the role of optical sensors in the medical field. Technological advancements such as miniaturization, improved sensitivity, and hybrid integration with AI and machine learning are further boosting market adoption. The shift toward Industry 4.0 and the proliferation of machine vision and robotics also contribute to sustained demand. These trends position optical sensors as essential components in next-generation digital and automation ecosystems.
The Optical Sensor Market demonstrates strong geographical presence across North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. Asia Pacific leads the market due to rapid industrialization, consumer electronics demand, and high-volume sensor manufacturing, followed by North America, driven by technological innovation and strong adoption in healthcare and defense. Europe shows steady growth with applications in automotive, energy, and smart infrastructure. Latin America and the Middle East are emerging markets supported by digital transformation and infrastructure investments, while Africa shows gradual expansion in healthcare and environmental monitoring. Key players in the Optical Sensor Market include ams-OSRAM AG, Texas Instruments, STMicroelectronics, Honeywell International Inc., TOSHIBA Corporation, ROHM Co., Ltd., Renesas Electronics Corporation, KEYENCE Corporation, ifm electronic gmbh, Rockwell Automation, Cisco Systems, SICK AG, Vishay Intertechnology, and Amphenol Corporation, all contributing to innovation and global competitiveness across segments.
Market Insights
- The Optical Sensor Market was valued at USD 25,553.07 million in 2024 and is projected to reach USD 60,238.46 million by 2032, growing at a CAGR of 11.38% due to increasing adoption across automation, healthcare, automotive, and consumer electronics.
- Rapid integration of optical sensors into IoT and smart devices is fueling demand for compact, power-efficient sensors that enhance gesture recognition, motion detection, and ambient light sensing.
- In the automotive sector, optical sensors are being used in ADAS and LiDAR systems to improve vehicle safety, driver assistance features, and autonomous driving capabilities.
- Healthcare and biomedical applications are witnessing significant growth, with optical sensors used in wearable monitors, imaging devices, and non-invasive diagnostic tools.
- Industrial automation and robotics are major drivers, with optical sensors supporting high-speed, accurate measurements for quality control, process monitoring, and predictive maintenance.
- High costs of advanced sensor technologies and environmental calibration challenges continue to limit widespread adoption in cost-sensitive markets and harsh operational conditions.
- Regionally, Asia Pacific dominates the Optical Sensor Market, followed by North America and Europe, while Latin America, the Middle East, and Africa are showing increasing adoption through infrastructure, energy, and healthcare initiatives.
Market Drivers
Growing Adoption of IoT and Smart Devices
The Optical Sensor Market is gaining momentum due to rising integration of sensors in Internet of Things (IoT) devices and smart consumer electronics. These sensors offer precise detection of motion, proximity, ambient light, and gestures, making them essential for smart homes, wearable devices, and mobile phones. It supports efficient communication between devices and their environment. Manufacturers are embedding optical sensors to improve automation, energy efficiency, and user experience. This shift is accelerating sensor deployment across connected ecosystems.
- For instance, Apple’s iPhone models use ambient light sensors to automatically adjust screen brightness, enhancing battery life and user comfort by responding precisely to environmental lighting conditions.
Expansion of Automotive Applications
The Optical Sensor Market is expanding in the automotive sector with increasing demand for safety, comfort, and automation. Optical sensors play a critical role in advanced driver-assistance systems (ADAS), enabling collision detection, lane departure warnings, and adaptive lighting. Automakers are integrating these sensors into LiDAR systems for autonomous navigation and enhanced situational awareness. It is enabling real-time detection of environmental variables. Strict vehicle safety regulations also encourage widespread adoption of optical sensor technologies in modern vehicles.
- For instance, Amkor, a leader in sensor packaging, has advanced optical sensor technologies that enable 3D gesture recognition and interior lighting control in passenger vehicles, contributing to the evolution of in-vehicle infotainment and automation systems.
Rising Demand in Industrial Automation and Robotics
Industrial automation is significantly contributing to the growth of the Optical Sensor Market. These sensors support high-speed, non-contact measurement and monitoring, essential in manufacturing, logistics, and robotics. It helps in object detection, position sensing, and quality assurance tasks on production lines. Industries are investing in smart factories and Industry 4.0 initiatives, requiring reliable sensing solutions. The demand for precision and operational efficiency is prompting manufacturers to rely on optical sensing systems in automation environments.
Advancements in Healthcare and Biomedical Devices
Healthcare innovation is reinforcing the demand for optical sensors in diagnostics and monitoring applications. The Optical Sensor Market benefits from the growing need for non-invasive, real-time measurements in patient care. It plays a vital role in pulse oximeters, glucose monitors, imaging systems, and biosensors. Technological advancements are improving sensor miniaturization, accuracy, and response time. The trend toward remote and wearable health monitoring is further expanding sensor usage in medical devices and healthcare facilities.
Market Trends
Miniaturization and Integration into Compact Devices
The Optical Sensor Market is witnessing a strong trend toward miniaturization to meet the requirements of compact and portable electronic devices. Manufacturers are designing ultra-small sensors without compromising performance, allowing seamless integration into smartphones, wearables, and medical instruments. It enables real-time monitoring, gesture recognition, and environmental sensing with greater efficiency. This trend supports multi-functionality within space-constrained systems. Advances in microelectromechanical systems (MEMS) and semiconductor technologies continue to enable smaller form factors with higher sensitivity.
- For instance, Texas Instruments’ Digital Micromirror Device (DMD), a MEMS-based optical chip with millions of microscopic mirrors, is widely used in portable projectors and medical imaging devices, demonstrating high performance in a miniaturized package.
Rising Use in Advanced Driver-Assistance Systems (ADAS)
The automotive industry continues to drive new trends in the Optical Sensor Market through its use in ADAS and autonomous vehicle development. Optical sensors are increasingly incorporated into LiDAR, cameras, and infrared systems to support object detection, obstacle avoidance, and night vision. It enhances driver safety, supports compliance with safety regulations, and enables semi-autonomous and fully autonomous capabilities. Automakers are actively expanding sensor use across vehicle classes, pushing demand for precision and durability.
- For instance, Novelic introduced its Automotive In-cabin Monitoring (ACAM) 60GHz millimeter-wave smart contactless sensor, capable of detecting and monitoring living beings inside vehicles, enhancing occupant safety and supporting next-generation ADAS features.
Shift Toward Industry 4.0 and Smart Manufacturing
The Optical Sensor Market is aligning with Industry 4.0 objectives, emphasizing automation, real-time data analytics, and interconnected machinery. These sensors are widely used in robotics, quality inspection systems, and process monitoring across industrial environments. It ensures accurate measurements in dynamic conditions and supports predictive maintenance strategies. The demand for smart factories is fueling the adoption of robust, high-speed optical sensors capable of operating in challenging settings. Integration with AI and edge computing is becoming standard.
Growth of Optical Sensors in Environmental and Biomedical Monitoring
Environmental monitoring and biomedical diagnostics are driving important trends within the Optical Sensor Market. The need for real-time data on pollutants, temperature, humidity, and bio-signals is increasing the deployment of optical sensing platforms. It supports applications in public health, lab-on-chip devices, and wearable biosensors. Companies are focusing on improving spectral sensitivity and multi-parameter detection capabilities. These advancements support emerging needs in climate studies, personalized medicine, and sustainable urban development initiatives.
Market Challenges Analysis
High Cost of Advanced Sensor Technologies
The Optical Sensor Market faces significant cost-related challenges, particularly with advanced and high-performance sensor systems. Research, development, and production of miniaturized, high-precision sensors require substantial capital investment and technical expertise. It makes these solutions expensive for small- and mid-sized enterprises, limiting widespread adoption. High material and fabrication costs further constrain pricing flexibility. In cost-sensitive markets, this becomes a major barrier to integration into consumer electronics and industrial applications. Manufacturers must balance innovation with affordability to sustain long-term market penetration.
Complex Calibration and Environmental Limitations
Another challenge for the Optical Sensor Market lies in the complexity of sensor calibration and environmental sensitivity. Optical sensors often require precise alignment and tuning to maintain accuracy across varying conditions such as light interference, dust, humidity, and temperature fluctuations. It can affect performance in harsh or unpredictable environments, reducing reliability. Maintenance and recalibration needs increase operational costs and hinder scalability. Industries dependent on consistent performance may hesitate to deploy optical sensors without guaranteed robustness or environmental protection.
Market Opportunities
Emergence of Smart Healthcare and Wearable Technologies
The Optical Sensor Market holds strong opportunities in the growing field of smart healthcare and wearable medical devices. Rising demand for continuous, non-invasive health monitoring has accelerated the use of optical sensors in applications such as heart rate tracking, blood oxygen measurement, and glucose monitoring. It enables real-time diagnostics and remote patient care, which are critical in aging populations and telemedicine frameworks. Wearable device manufacturers are investing in compact, energy-efficient optical sensors to enhance functionality. This segment presents long-term potential driven by consumer health awareness and technology convergence.
Expansion into Environmental Monitoring and Smart Cities
Environmental sensing and smart city infrastructure offer expanding opportunities for the Optical Sensor Market. Governments and urban planners are deploying optical sensors to monitor air quality, water quality, light intensity, and pollution levels. It supports real-time environmental data collection critical to sustainability initiatives and disaster response systems. Integration into traffic control, waste management, and public safety systems further enhances value. The push for intelligent urban ecosystems provides a scalable platform for sensor deployment across diverse geographies. Optical sensors are positioned to become essential components in the next generation of urban infrastructure.
Market Segmentation Analysis:
By Type
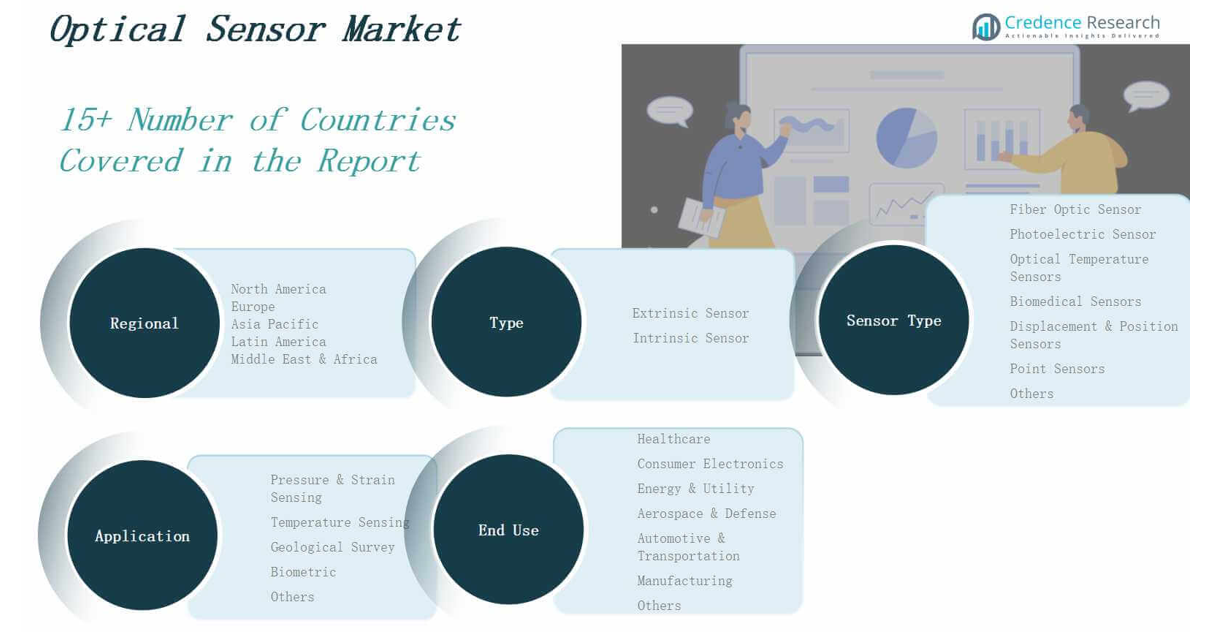
The Optical Sensor Market is segmented into extrinsic and intrinsic sensors. Extrinsic sensors detect light transmitted through or reflected from an external environment, offering flexibility and high sensitivity. Intrinsic sensors use the optical fiber itself as the sensing element, providing better protection against electromagnetic interference and harsh conditions. It supports high-precision measurement in remote and sensitive environments. Both types are widely used in industrial and defense applications where reliability and accuracy are essential.
- For instance, Hamamatsu Photonics has developed high-speed CMOS sensors used in scientific and industrial imaging systems, supporting real-time analysis in demanding environments.
By Application
The Optical Sensor Market serves diverse applications, including pressure and strain sensing, temperature sensing, geological surveys, biometrics, and others. Pressure and strain sensors are critical in structural health monitoring and aerospace systems. Temperature sensing is prevalent in industrial automation and power systems. Geological surveys rely on optical sensors for seismic and environmental monitoring. Biometric applications, such as fingerprint and facial recognition, are increasing in demand across mobile and security devices. These varied applications demonstrate strong growth potential.
- For instance, Vishay Intertechnology launched the VEML6031X00 ambient light sensor in October 2021, featuring a highly sensitive photodiode and a 16-bit ADC, specifically designed for automotive and consumer electronics to enhance adaptive lighting and safety systems.
By End-Use The Optical Sensor Market caters to several end-use sectors, including healthcare, consumer electronics, energy and utility, aerospace and defense, automotive and transportation, manufacturing, and others. Healthcare relies on optical sensors for non-invasive monitoring and diagnostics. Consumer electronics use them in smartphones, wearables, and smart home devices. Energy, aerospace, and automotive sectors adopt these sensors for efficiency, safety, and automation. Manufacturing integrates optical sensors for precision control and quality assurance in industrial processes.
Segments:
Based on Type
- Extrinsic Sensor
- Intrinsic Sensor
Based on Application
- Pressure & Strain Sensing
- Temperature Sensing
- Geological Survey
- Biometric
- Others
Based on End-Use
- Healthcare
- Consumer Electronics
- Energy & Utility
- Aerospace & Defense
- Automotive & Transportation
- Manufacturing
- Others
Based on Sensor Type
- Fiber Optic Sensor
- Photoelectric Sensor
- Optical Temperature Sensors
- Biomedical Sensors
- Displacement & Position Sensors
- Point Sensor
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Optical Sensor Market size was valued at USD 5,056.94 million in 2018 to USD 7,221.14 million in 2024 and is anticipated to reach USD 16,993.38 million by 2032, at a CAGR of 11.4% during the forecast period. North America holds a significant share of the Optical Sensor Market, driven by the presence of leading technology companies and a strong demand for automation across industries. It benefits from high adoption rates in healthcare, aerospace, and consumer electronics sectors. The U.S. leads regional growth with investments in autonomous vehicles, smart devices, and defense modernization. Research institutions and government funding encourage innovation in optical sensing technologies. The region’s focus on early adoption of Industry 4.0 and IoT-based infrastructure continues to support sustained market expansion.
Europe
The Europe Optical Sensor Market size was valued at USD 3,599.77 million in 2018 to USD 4,959.15 million in 2024 and is anticipated to reach USD 10,846.10 million by 2032, at a CAGR of 10.4% during the forecast period. Europe maintains a robust position in the Optical Sensor Market due to stringent safety regulations, strong automotive manufacturing, and growing smart infrastructure initiatives. It shows widespread application across industrial automation, energy systems, and biomedical devices. Germany, the UK, and France dominate demand through investments in research, renewable energy, and mobility innovation. Regulatory mandates supporting sustainable solutions further enhance optical sensor integration. European industries prioritize accuracy and environmental adaptability, fueling continued sensor adoption across sectors.
Asia Pacific
The Asia Pacific Optical Sensor Market size was valued at USD 7,088.53 million in 2018 to USD 10,557.14 million in 2024 and is anticipated to reach USD 26,480.88 million by 2032, at a CAGR of 12.2% during the forecast period. Asia Pacific commands the largest share of the Optical Sensor Market, driven by rapid industrialization, urban development, and expanding electronics production. It shows high demand across China, Japan, South Korea, and India in automotive, consumer electronics, and manufacturing applications. Government-backed smart city programs and increasing adoption of robotics are contributing to growth. Asia’s strong semiconductor ecosystem supports large-scale sensor production and export. The presence of major OEMs further accelerates integration of optical sensors across commercial and industrial platforms.
Latin America
The Latin America Optical Sensor Market size was valued at USD 898.62 million in 2018 to USD 1,287.62 million in 2024 and is anticipated to reach USD 2,763.14 million by 2032, at a CAGR of 10.1% during the forecast period. Latin America shows growing potential in the Optical Sensor Market due to improving infrastructure, healthcare investments, and digital transformation. It is witnessing gradual adoption in automation, utility monitoring, and public safety technologies. Brazil and Mexico lead regional deployment in automotive and industrial sectors. Rising awareness of smart technologies is pushing demand for reliable sensing solutions. Government initiatives in healthcare and energy efficiency create favorable conditions for market development.
Middle East
The Middle East Optical Sensor Market size was valued at USD 690.70 million in 2018 to USD 940.19 million in 2024 and is anticipated to reach USD 2,006.27 million by 2032, at a CAGR of 10.0% during the forecast period. The Middle East is emerging as a promising region in the Optical Sensor Market with its emphasis on smart city projects and security infrastructure. It leverages optical sensors in transportation systems, energy monitoring, and surveillance. The UAE and Saudi Arabia are actively investing in digital transformation and renewable energy projects. It also sees rising interest in integrating sensors into healthcare and oil & gas operations. Regional focus on innovation and sustainability is expanding the adoption of optical sensing technologies.
Africa
The Africa Optical Sensor Market size was valued at USD 285.44 million in 2018 to USD 587.82 million in 2024 and is anticipated to reach USD 1,148.70 million by 2032, at a CAGR of 8.2% during the forecast period. Africa holds a smaller but steadily growing share in the Optical Sensor Market, supported by technological development and expanding telecommunications infrastructure. It is gradually deploying optical sensors in agriculture, healthcare, and environmental monitoring. Countries like South Africa and Egypt are leading adoption efforts through public sector investments. Demand for affordable, durable, and scalable technologies shapes the regional market. Increasing urbanization and the need for reliable sensor networks support future growth across the continent.
Key Player Analysis
- ams-OSRAM AG
- TOSHIBA CORPORATION
- Texas Instruments Incorporated
- Renesas Electronics Corporation
- ROHM CO., LTD
- STMicroelectronics
- Rockwell Automation
- SICK AG
- Vishay Intertechnology, Inc.
- Honeywell International Inc.
- ifm electronic gmbh
- KEYENCE CORPORATION
- Cisco Systems, Inc.
- Amphenol Corporation
Competitive Analysis
The Optical Sensor Market is highly competitive, with established players focusing on innovation, strategic partnerships, and vertical integration to maintain market leadership. Companies such as ams-OSRAM AG, Texas Instruments, STMicroelectronics, and Honeywell International dominate through advanced product offerings, strong R&D capabilities, and global distribution networks. It features continuous investment in miniaturization, sensitivity enhancement, and integration with AI and IoT platforms. Emerging players are targeting niche applications like biomedical sensing and environmental monitoring to gain market share. Pricing pressure and the demand for customized solutions are prompting firms to optimize manufacturing processes and shorten product development cycles. The market sees frequent technological upgrades, compelling vendors to maintain agility and speed in deployment. Collaborations with OEMs, end-user industries, and academic institutions are helping manufacturers expand their application base and meet evolving customer demands. Competitive intensity remains high, especially across Asia-Pacific and North America, where demand for industrial automation and consumer electronics drives rapid innovation.
Recent Developments
- In June 2025, TransDigm Group acquired Simmonds Precision Products for approximately USD 765 million to strengthen its portfolio in advanced proximity and structural health monitoring sensors.
- In June 2025, Sensoric Solutions launched its U.S. branch to expand the deployment of high-precision optical sensors for automotive testing, partnering with OEMs such as GM and Honda.
- In June 2025, Airbus and CNES prepared to launch the next-generation CO3D optical satellite constellation, equipped with advanced optical laser sensing and stereo imaging capabilities.
- In April 2025, SCIVAX and TSLC unveiled the world’s smallest PPG optical sensor head for wearable health monitoring devices, highlighting advancements in sensor miniaturization.
Market Concentration & Characteristics
The Optical Sensor Market exhibits moderate to high market concentration, with a mix of global technology leaders and specialized niche players dominating the competitive landscape. It is characterized by strong innovation cycles, rapid technological evolution, and continuous product differentiation. Key players focus on developing compact, high-performance, and cost-effective sensors tailored to application-specific needs in industries such as automotive, healthcare, and industrial automation. The market benefits from vertically integrated supply chains and close collaborations between manufacturers and system integrators. Entry barriers are relatively high due to significant R&D investment requirements and complex manufacturing capabilities. Product quality, reliability, and customization play a central role in vendor selection, while regulatory compliance and integration capabilities further influence market dynamics. The Optical Sensor Market also demonstrates regional specialization, with Asia Pacific leading in production volume and North America driving high-end innovation. Growth is fueled by rising demand for intelligent sensing in connected devices, smart infrastructure, and precision technologies.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Sensor Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for optical sensors will rise with increased adoption of smart devices and connected technologies.
- Automotive applications will continue expanding, driven by autonomous vehicles and ADAS integration.
- Healthcare will see broader use of optical sensors in non-invasive diagnostics and wearable monitoring.
- Industrial automation and robotics will increasingly rely on optical sensing for precision and safety.
- Miniaturization and energy efficiency improvements will support wider deployment across compact devices.
- Integration of optical sensors with AI and machine learning will enhance real-time data processing.
- Environmental monitoring and smart city projects will create new opportunities for optical sensing technologies.
- Manufacturers will invest in developing cost-effective solutions to address pricing barriers in emerging markets.
- Collaborative partnerships between OEMs and sensor developers will accelerate product innovation.
- Region-specific advancements will shape market leadership, with Asia Pacific maintaining strong manufacturing capacity.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Adoption of IoT and Smart Devices
The proliferation of IoT and smart consumer electronics is driving demand for compact, energy-efficient optical sensors that enable precise detection of motion, proximity, ambient light, and gestures, supporting automation and enhanced user experiences in connected ecosystems.
Expansion of Automotive Applications
Automotive manufacturers are increasingly integrating optical sensors into advanced driver-assistance systems (ADAS) and LiDAR for autonomous vehicles, improving safety, situational awareness, and compliance with stringent vehicle safety regulations.
Rising Demand in Industrial Automation and Robotics
Industrial automation and robotics rely on optical sensors for high-speed, non-contact measurement, object detection, and quality assurance, supporting the shift toward smart factories and Industry 4.0 initiatives that require reliable, precise sensing solutions.
Advancements in Healthcare and Biomedical Devices
Healthcare innovation is boosting the use of optical sensors in non-invasive diagnostics, wearable monitors, and imaging devices, enabling real-time patient monitoring and supporting the trend toward remote and personalized healthcare.
Miniaturization and Integration with AI/ML
Technological advancements in miniaturization and the integration of optical sensors with AI and machine learning are enabling smarter, more sensitive, and multifunctional sensors, expanding their applicability in compact devices and real-time data processing environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Optical Sensors market?
What factors are driving the growth of the Optical Sensors market?
What are the key segments within the Optical Sensors market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Extrinsic Sensor
- 1.2.2 Intrinsic Sensor
- 1.3 By End-Use
- 1.3.1 Healthcare
- 1.3.2 Consumer Electronics
- 1.3.3 Energy & Utility
- 1.3.4 Aerospace & Defense
- 1.3.5 Automotive & Transportation
- 1.3.6 Manufacturing
- 1.3.7 Others
- 1.4 By Application
- 1.4.1 Pressure & Strain Sensing
- 1.4.2 Temperature Sensing
- 1.4.3 Geological Survey
- 1.4.4 Biometric
- 1.4.5 Others
- 1.5 By Sensor Type
- 1.5.1 Fiber Optic Sensor
- 1.5.2 Photoelectric Sensor
- 1.5.3 Optical Temperature Sensors
- 1.5.4 Biomedical Sensors
- 1.5.5 Displacement & Position Sensors
- 1.5.6 Point Sensor
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,553.07 million → 2032: USD 60,238.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Optical Sensor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Optical Sensor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Optical Sensor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Optical Sensor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Optical Sensor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Optical Sensor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Optical Sensor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Optical Sensor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,553.07 million → 2032: USD 60,238.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Optical Sensor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Extrinsic Sensor
- 12.3.7.2 Intrinsic Sensor
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Healthcare
- 12.4.7.2 Consumer Electronics
- 12.4.7.3 Energy & Utility
- 12.4.7.4 Aerospace & Defense
- 12.4.7.5 Automotive & Transportation
- 12.4.7.6 Manufacturing
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pressure & Strain Sensing
- 12.5.7.2 Temperature Sensing
- 12.5.7.3 Geological Survey
- 12.5.7.4 Biometric
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sensor Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Fiber Optic Sensor
- 12.6.7.2 Photoelectric Sensor
- 12.6.7.3 Optical Temperature Sensors
- 12.6.7.4 Biomedical Sensors
- 12.6.7.5 Displacement & Position Sensors
- 12.6.7.6 Point Sensor
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Optical Sensor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Optical Sensor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Optical Sensor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Optical Sensor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ams-OSRAM AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Texas Instruments Incorporated
- 18.4 STMicroelectronics
- 18.5 Honeywell International Inc.
- 18.6 TOSHIBA Corporation
- 18.7 ROHM Co., Ltd.
- 18.8 Renesas Electronics Corporation
- 18.9 KEYENCE Corporation
- 18.10 SICK AG
- 18.11 Vishay Intertechnology, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

