
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Orthopedic Regenerative Medicine Market Size 2024 | USD 9505 million |
| Orthopedic Regenerative Medicine Market, CAGR | 9.95% |
| Orthopedic Regenerative Medicine Market Size 2032 | USD 20300.8 million |
Market Overview:
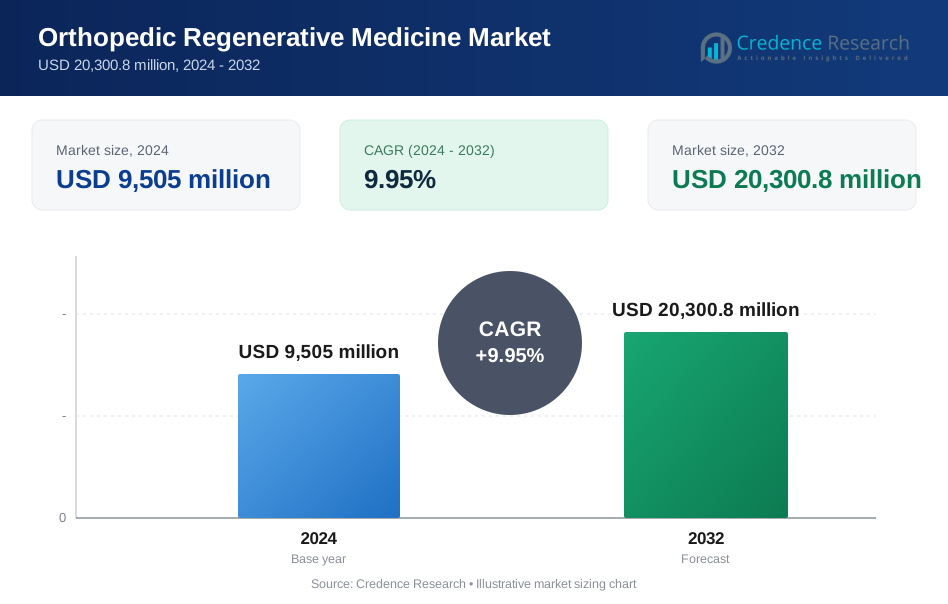
The Orthopedic Regenerative Medicine Market is projected to grow from USD 9505 million in 2024 to an estimated USD 20300.8 million by 2032, with a compound annual growth rate (CAGR) of 9.95% from 2024 to 2032.
Several key factors are driving the growth of the orthopedic regenerative medicine market. The aging global population is a primary driver, as older adults are more susceptible to orthopedic conditions requiring regenerative treatments. Additionally, the rising prevalence of musculoskeletal disorders, often linked to sedentary lifestyles, sports injuries, and obesity, is fueling demand for effective and minimally invasive therapies. Technological advancements, such as the development of stem cell therapies, gene therapies, and tissue engineering, are enhancing the efficacy and availability of regenerative treatments, attracting both patients and healthcare providers. Furthermore, increasing awareness about the benefits of regenerative medicine, such as reduced recovery times and lower risks of complications, is encouraging more patients to opt for these advanced therapies over traditional surgical methods.
Regionally, North America dominates the orthopedic regenerative medicine market, accounting for the largest share due to its advanced healthcare infrastructure, high prevalence of orthopedic conditions, and strong investment in research and development. The United States, in particular, is a key contributor, driven by a large number of ongoing clinical trials and a favorable regulatory environment. Europe follows closely, with countries like Germany, the United Kingdom, and France leading the market, supported by robust healthcare systems and increasing adoption of regenerative therapies. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, driven by rising healthcare expenditure, increasing awareness of regenerative treatments, and a growing elderly population in countries like China, Japan, and India. Emerging markets in Latin America and the Middle East & Africa are also showing potential, with improving healthcare infrastructure and increasing demand for advanced orthopedic treatments contributing to market expansion.
Market Drivers:
Aging Population and Rising Prevalence of Orthopedic Disorders:
One of the primary drivers of the orthopedic regenerative medicine market is the aging global population. As life expectancy increases, so does the prevalence of age-related orthopedic conditions such as osteoarthritis, degenerative disc disease, and osteoporosis. Older adults are more prone to musculoskeletal issues that require effective and long-term treatment solutions. Regenerative medicine offers promising alternatives to traditional orthopedic surgeries, providing treatments that can restore damaged tissues, reduce pain, and improve mobility. For example, the Mayo Clinic has developed a unique regenerative medicine procedure called recycled cartilage auto/allo implantation (RECLAIM), which has shown promising results in knee and hip joint restoration. In a study conducted by Mayo Clinic, patients who underwent the RECLAIM procedure experienced a 70% improvement in knee function and a 60% reduction in pain within one year. The increasing incidence of these conditions among the elderly population is fueling demand for advanced regenerative therapies, positioning the market for substantial growth.
Advancements in Regenerative Technologies:
Technological advancements in regenerative medicine are significantly propelling the orthopedic market forward. Innovations in stem cell therapy, gene therapy, and tissue engineering have opened new avenues for treating complex orthopedic conditions. Stem cell therapies, for instance, have shown great potential in repairing cartilage, bone, and tendon tissues, offering a minimally invasive solution with fewer complications compared to traditional surgical methods. Gene therapy and tissue engineering are also advancing rapidly, enabling the development of personalized and targeted treatments that enhance the body’s natural healing processes. These technological breakthroughs are driving the adoption of regenerative medicine in orthopedics, as they offer patients more effective and tailored treatment options.
Increasing Demand for Minimally Invasive Treatments:
The growing preference for minimally invasive treatments is another key driver in the orthopedic regenerative medicine market. Patients and healthcare providers alike are increasingly opting for treatments that offer shorter recovery times, reduced pain, and lower risks of complications. Regenerative medicine aligns with these preferences by providing therapies that promote tissue regeneration and repair without the need for extensive surgical procedures. For instance, the use of platelet-rich plasma (PRP) injections and autologous stem cell transplants in treating joint and tendon injuries has gained popularity due to their minimally invasive nature and positive outcomes. A study published in the American Academy of Orthopaedic Surgeons (AAOS) found that PRP injections improved pain and function scores by 30% to 50% in patients with knee osteoarthritis. As more patients seek alternatives to conventional surgery, the demand for regenerative medicine in orthopedics is expected to rise.
Growing Awareness and Acceptance of Regenerative Medicine:
The increasing awareness and acceptance of regenerative medicine among patients and healthcare professionals are also driving market growth. As more clinical evidence supports the efficacy and safety of regenerative treatments, they are becoming more widely accepted as viable options for managing orthopedic conditions. Public and private initiatives aimed at educating healthcare providers and patients about the benefits of regenerative medicine are helping to expand its adoption. Additionally, the availability of information through digital platforms and social media is making it easier for patients to learn about and consider regenerative treatments. This growing awareness is translating into higher demand for orthopedic regenerative medicine, as patients increasingly seek out these advanced therapies for their musculoskeletal health needs.
Market Trends:
Rising Adoption of Stem Cell Therapies:
One of the most prominent trends in the orthopedic regenerative medicine market is the increasing adoption of stem cell therapies. Stem cells have the unique ability to differentiate into various cell types, making them an ideal solution for repairing damaged tissues in orthopedic applications. As research in stem cell technology advances, there has been a growing focus on using these therapies to treat conditions such as osteoarthritis, cartilage injuries, and bone fractures. For instance, Stanford Health Care has reported that 82.2% of osteoarthritis patients treated with stem cell-based therapies experienced significant improvement in joint function and pain relief. The development of autologous and allogeneic stem cell treatments is gaining momentum, offering patients more effective and personalized treatment options. This trend is further supported by the growing number of clinical trials and positive outcomes reported in the use of stem cells for orthopedic conditions, which are driving wider acceptance among healthcare providers and patients.
Growth of Tissue Engineering and 3D Bioprinting:
The integration of tissue engineering and 3D bioprinting technologies into the orthopedic regenerative medicine market is another significant trend. Tissue engineering involves creating biological substitutes that can restore, maintain, or improve tissue function, while 3D bioprinting enables the fabrication of complex tissue structures using biomaterials and living cells. These technologies are revolutionizing the treatment of orthopedic conditions by enabling the creation of customized implants and tissue grafts that closely mimic natural tissues. For example, 3D bioprinted scaffolds are being developed to support bone regeneration, providing a more effective and tailored approach to treating bone defects and fractures. As these technologies continue to evolve, they are expected to play a crucial role in advancing regenerative medicine in orthopedics.
Increasing Focus on Personalized Medicine:
The orthopedic regenerative medicine market is witnessing a growing emphasis on personalized medicine, where treatments are tailored to the individual needs of each patient. This trend is driven by advancements in genetic research, biomarker identification, and patient-specific data analysis. Personalized regenerative therapies, such as custom-made stem cell treatments and targeted gene therapies, are being developed to address the unique characteristics of a patient's condition, leading to better outcomes and fewer side effects. The increasing availability of personalized treatment options is transforming the orthopedic field, allowing for more precise and effective interventions. As healthcare providers continue to adopt this patient-centric approach, the demand for personalized regenerative medicine solutions is expected to rise.
Expansion of Regulatory Approvals and Reimbursement Policies:
The expansion of regulatory approvals and the development of favorable reimbursement policies are also shaping the orthopedic regenerative medicine market. Regulatory bodies, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), are increasingly recognizing the potential of regenerative therapies, leading to more streamlined approval processes for innovative treatments. Additionally, as regenerative medicine gains wider acceptance, there is a growing push for the inclusion of these therapies in reimbursement plans, making them more accessible to a broader patient population. For instance, The Alliance for Regenerative Medicine reported that sector financing reached $19.9 billion in 2020, doubling from the previous year, which has fueled the broader biotech sector and driven a rapidly advancing pipeline of potentially transformative therapies. The expansion of regulatory approvals and reimbursement policies is expected to drive the adoption of regenerative medicine in orthopedics, as more patients and healthcare providers gain access to these cutting-edge treatments.
Market Restraints and Challenges:
High Cost of Treatments:
One of the primary restraints in the orthopedic regenerative medicine market is the high cost associated with regenerative therapies. The development and application of advanced technologies such as stem cell therapies and tissue engineering often require significant investment in research, manufacturing, and clinical implementation. This can lead to expensive treatment options that may not be covered by insurance, making them less accessible to many patients. High costs can deter healthcare providers from adopting these innovative treatments, particularly in regions with limited healthcare budgets. As a result, the financial barrier poses a significant challenge to the widespread adoption of regenerative medicine in orthopedics.
Regulatory Hurdles:
Regulatory challenges represent another major restraint in the orthopedic regenerative medicine market. The approval process for new regenerative therapies can be lengthy and complex, requiring extensive clinical trials to demonstrate safety and efficacy. This can delay the introduction of innovative treatments into the market, limiting patient access and hindering potential growth for companies involved in regenerative medicine. Regulatory bodies, while increasingly supportive of regenerative therapies, still impose strict guidelines that can complicate the development and commercialization of new products. Navigating these regulatory landscapes requires significant resources and expertise, which can be a barrier for smaller companies and startups.
Limited Awareness and Acceptance:
Limited awareness and acceptance of regenerative medicine among healthcare providers and patients can also hinder market growth. While interest in regenerative therapies is increasing, many healthcare professionals remain unfamiliar with the latest advancements and their potential benefits. This lack of knowledge can lead to reluctance in recommending these treatments to patients. Additionally, patients may be skeptical about the effectiveness and safety of regenerative therapies, preferring traditional treatment options. Increasing educational initiatives and outreach efforts are necessary to overcome this barrier, but until awareness improves, the market may struggle to achieve its full potential.
Ethical and Legal Concerns:
Ethical and legal concerns surrounding the use of stem cells and other regenerative technologies also pose challenges in the market. The sourcing of stem cells, particularly embryonic stem cells, raises ethical questions that can lead to public resistance and regulatory scrutiny. Legal disputes related to intellectual property and the commercialization of regenerative therapies can further complicate market dynamics. Addressing these ethical and legal concerns is essential for fostering trust and acceptance within the medical community and among patients, ultimately impacting the growth of the orthopedic regenerative medicine market.
Market Segmentation Analysis:
By Product, the market includes allografts, synthetic materials, cell-based therapies, and viscosupplements. Allografts, particularly amniotic products, are gaining popularity due to their natural healing properties and effectiveness in tissue repair. Synthetic products are also in demand for their versatility and customization options. Cell-based therapies, including stem cell treatments, are increasingly recognized for their potential to regenerate damaged tissues, while viscosupplements are widely used for osteoarthritis management, providing lubrication and pain relief in joints.
By Application, the market encompasses orthopedic pain management, trauma repair, cartilage and tendon repair, joint reconstruction, and others. The orthopedic pain management segment is significant as more patients seek effective alternatives to traditional pain relief methods. Joint reconstruction and cartilage repair applications are expanding due to the rising prevalence of orthopedic injuries and degenerative diseases.
By End-use, the market is divided into hospitals, ambulatory surgical centers, and others. Hospitals remain the largest end-user segment, driven by their comprehensive treatment capabilities and advanced surgical facilities. Ambulatory surgical centers are also gaining traction as they offer efficient and cost-effective solutions for outpatient procedures, facilitating the adoption of regenerative therapies in a growing number of clinical settings.
Segmentation:
By Product
- Allografts
- Amniotic Products
- Others
- Synthetic
- Cell-based
- Viscosupplements
By Application
- Orthopedic Pain Management
- Trauma Repair
- Cartilage & Tendon Repair
- Joint Reconstruction
- Others
By End-use
- Hospitals
- Ambulatory Surgical Centers
- Others
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America dominates the orthopedic regenerative medicine market, accounting for approximately 45% of the global market share. This dominance is primarily due to the presence of advanced healthcare infrastructure, high levels of research and development investment, and a strong concentration of pharmaceutical and biotechnology companies. The United States is a key contributor, where ongoing clinical trials and favorable regulatory frameworks facilitate the development and commercialization of innovative regenerative therapies. Additionally, the aging population and the rising prevalence of orthopedic conditions, such as osteoarthritis and sports injuries, drive demand for advanced treatment options in the region. The increasing acceptance of minimally invasive procedures and regenerative therapies further supports market growth.
Europe
Europe holds the second-largest share of the orthopedic regenerative medicine market, accounting for around 30% of the global market. The region benefits from a well-established healthcare system and significant investment in medical research. Countries like Germany, the United Kingdom, and France lead in adopting regenerative therapies due to their robust healthcare infrastructure and high clinical trial activity. The European Medicines Agency (EMA) plays a crucial role in regulating and approving regenerative treatments, contributing to market growth. Moreover, the increasing focus on personalized medicine and patient-centric approaches is driving demand for innovative therapies in orthopedic applications, further enhancing the market landscape in Europe.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the orthopedic regenerative medicine market, with a projected CAGR significantly higher than other regions. Currently, it accounts for approximately 15% of the global market share. The rapid growth can be attributed to rising healthcare expenditure, an increasing elderly population, and the outsourcing of clinical trials to countries like China, India, and South Korea. These countries offer a large patient pool, lower treatment costs, and favorable government policies that attract global pharmaceutical companies. As awareness of regenerative therapies increases and healthcare infrastructure improves, the Asia-Pacific region is poised for substantial market expansion.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively account for about 10% of the global orthopedic regenerative medicine market. In Latin America, countries like Brazil and Mexico are emerging markets with significant growth potential, driven by improving healthcare infrastructure and increasing clinical research activities. In the Middle East & Africa, there is a growing interest in regenerative therapies as healthcare systems evolve and the demand for advanced orthopedic treatments rises. However, challenges such as limited access to cutting-edge technologies and regulatory hurdles may slow market growth in these regions. Nevertheless, increasing government efforts to promote advanced healthcare solutions provide a positive outlook for the orthopedic regenerative medicine market in Latin America and the Middle East & Africa.
Key Player Analysis:
- AlloSource
- Amniox Medical, Inc.
- Anika Therapeutics, Inc.
- Aptissen S.A.
- Arthrex, Inc.
- Baxter
- MiMedx
- Smith & Nephew
- Stryker
- Vericel Corporation
- VSY Biotechnology
- Zimmer Biomet
Competitive Analysis:
The orthopedic regenerative medicine market is highly competitive, featuring a mix of established players and emerging companies. Major corporations such as Medtronic, Stryker Corporation, and Zimmer Biomet dominate the landscape, leveraging their extensive research and development capabilities and strong distribution networks. These companies are continuously innovating, focusing on advanced therapies such as stem cell treatments, tissue engineering, and platelet-rich plasma therapies to enhance patient outcomes. Emerging players like Athersys, Inc. and Regenative Labs are gaining traction by offering novel solutions tailored to specific orthopedic conditions. The market is characterized by strategic collaborations, mergers, and acquisitions, as companies seek to expand their product portfolios and geographic reach. Regulatory approvals and clinical trial successes play critical roles in shaping the competitive dynamics, with firms investing heavily in R&D to bring innovative therapies to market. As awareness and acceptance of regenerative medicine grow, competition is expected to intensify, driving further advancements in the field.
Recent Developments:
- In January 2024, Bioventus Inc. (NASDAQ: BVS), a global leader in innovations for active healing, completed the acquisition of CartiHeal Ltd., an Israeli medical device company. This strategic move strengthens Bioventus' position in the orthopedic regenerative medicine market, particularly in the area of cartilage repair and joint preservation. The acquisition brings CartiHeal's innovative Agili-C implant, designed for treating cartilage and osteochondral defects in knee joints, into Bioventus' portfolio of orthopedic solutions.
Market Concentration & Characteristics:
The orthopedic regenerative medicine market exhibits moderate concentration, with several key players dominating the landscape while allowing for the presence of emerging companies. Major firms such as Medtronic, Stryker Corporation, and Zimmer Biomet lead the market, leveraging their established brand recognition, extensive research and development capabilities, and comprehensive distribution networks. These companies focus on innovation, frequently launching new products that enhance treatment efficacy and patient outcomes. The market is characterized by significant investment in research, particularly in areas such as stem cell therapies and tissue engineering, which are pivotal for advancing regenerative solutions. Additionally, collaborations and partnerships between established firms and startups are common, fostering innovation and expanding product offerings. Regulatory approvals play a critical role in shaping market dynamics, as companies strive to meet stringent safety and efficacy standards. As awareness and acceptance of regenerative therapies increase, the competitive landscape is expected to evolve, driving further growth in the market.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Application and By End-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Continued advancements in stem cell technologies will enhance treatment options for various orthopedic conditions.
- The increasing prevalence of osteoarthritis and sports injuries will drive demand for regenerative therapies.
- Growth in healthcare spending will facilitate the adoption of innovative orthopedic solutions across regions.
- Expanding clinical research and successful trial outcomes will lead to more approved regenerative products.
- The shift toward personalized medicine will encourage the development of tailored regenerative therapies.
- Rising awareness of minimally invasive treatments will boost the adoption of regenerative options among patients and providers.
- Integration of advanced technologies, such as 3D bioprinting, will create new possibilities for tissue engineering.
- Collaborations between academic institutions and industry players will foster innovation in regenerative medicine.
- Enhanced reimbursement policies will improve access to orthopedic regenerative therapies for a broader patient population.
- Emerging markets in Asia-Pacific and Latin America will experience significant growth due to improving healthcare infrastructure
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Orthopedic Disease Prevalence
The global increase in the elderly population is leading to a higher incidence of orthopedic conditions such as osteoarthritis and degenerative disc disease, which require regenerative treatments for effective management and improved mobility.
Technological Advancements in Regenerative Therapies
Innovations in stem cell therapy, gene therapy, and tissue engineering are enhancing the efficacy and availability of orthopedic regenerative medicine, making advanced treatments more accessible and attractive to both patients and healthcare providers.
Preference for Minimally Invasive Treatments
Patients and clinicians are increasingly seeking minimally invasive options that offer shorter recovery times and lower complication risks, driving the adoption of regenerative medicine solutions like PRP injections and stem cell therapies over traditional surgeries.
Expanding Clinical Evidence and Awareness
Growing clinical evidence supporting the safety and effectiveness of regenerative therapies, combined with educational initiatives and digital information dissemination, is increasing acceptance and demand among both healthcare professionals and patients.
Supportive Regulatory and Reimbursement Environment
Streamlined regulatory approvals and the expansion of reimbursement policies for regenerative therapies are making these treatments more accessible, encouraging investment and accelerating market growth, especially in developed regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Orthopedic Regenerative Medicine Market?
What factors are driving the growth of the orthopedic regenerative medicine market?
Which region dominates the orthopedic regenerative medicine market?
What are the challenges facing the orthopedic regenerative medicine market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Others
- 1.3 By Product
- 1.3.1 Allografts
- 1.3.2 Amniotic Products
- 1.3.3 Synthetic
- 1.3.4 Cell-based
- 1.3.5 Viscosupplements
- 1.3.6 Others
- 1.4 By Application
- 1.4.1 Orthopedic Pain Management
- 1.4.2 Trauma Repair
- 1.4.3 Cartilage & Tendon Repair
- 1.4.4 Joint Reconstruction
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,505 million → 2032: USD 20,300.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthopedic Regenerative Medicine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthopedic Regenerative Medicine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthopedic Regenerative Medicine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthopedic Regenerative Medicine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthopedic Regenerative Medicine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthopedic Regenerative Medicine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthopedic Regenerative Medicine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthopedic Regenerative Medicine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,505 million → 2032: USD 20,300.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthopedic Regenerative Medicine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Allografts
- 12.4.7.2 Amniotic Products
- 12.4.7.3 Synthetic
- 12.4.7.4 Cell-based
- 12.4.7.5 Viscosupplements
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Orthopedic Pain Management
- 12.5.7.2 Trauma Repair
- 12.5.7.3 Cartilage & Tendon Repair
- 12.5.7.4 Joint Reconstruction
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthopedic Regenerative Medicine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Orthopedic Regenerative Medicine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Orthopedic Regenerative Medicine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Orthopedic Regenerative Medicine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stryker
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Zimmer Biomet
- 18.4 Smith & Nephew
- 18.5 MiMedx
- 18.6 AlloSource
- 18.7 Anika Therapeutics
- 18.8 Baxter
- 18.9 Vericel Corporation
- 18.10 Arthrex
- 18.11 Amniox Medical
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

