
Market Overview:
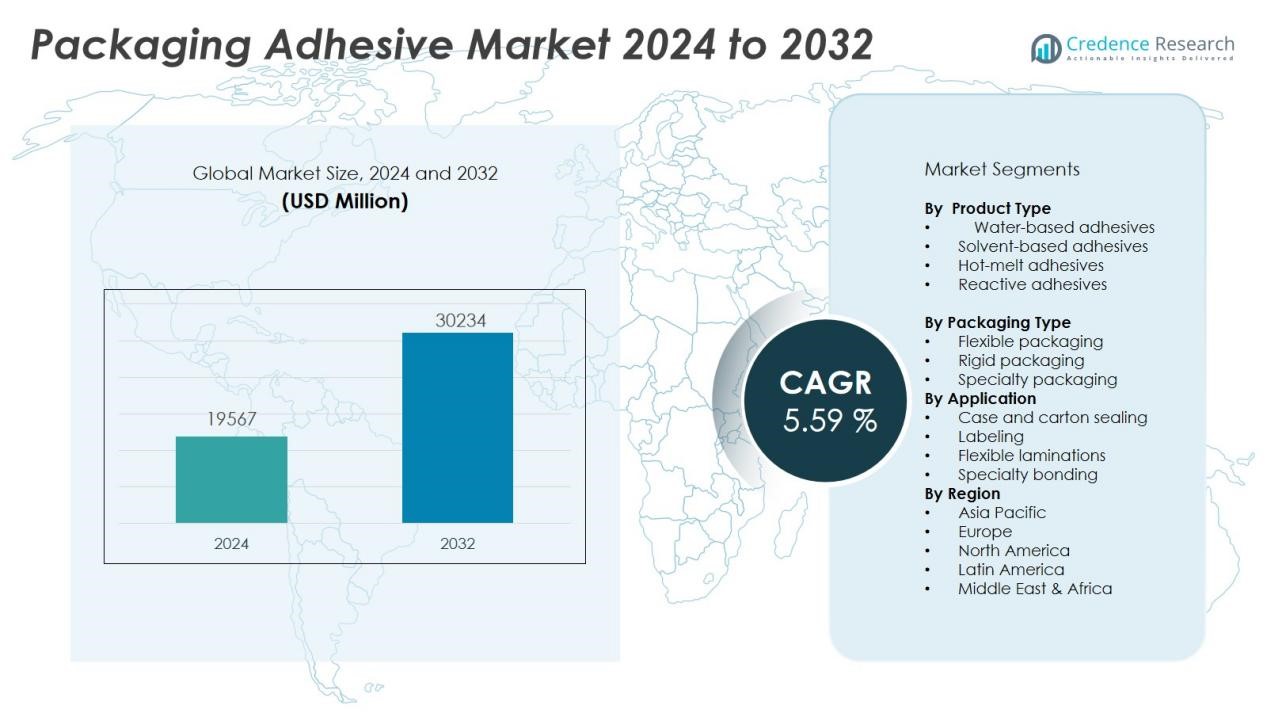
The Packaging Adhesives Market size was valued at USD 19567 million in 2024 and is anticipated to reach USD 30234 million by 2032, at a CAGR of 5.59 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Packaging Adhesives Market Size 2024 | USD 19567 Million |
| Packaging Adhesives Market, CAGR | 5.59 % |
| Packaging Adhesives Market Size 2032 | USD 30234 Million |
Key drivers shaping the Packaging Adhesive Market include the growing emphasis on lightweight, recyclable, and sustainable packaging materials to meet regulatory and consumer expectations. Rising e-commerce volumes, stringent food safety standards, and the shift toward eco-friendly substrates accelerate the demand for solvent-free, water-based, and hot-melt adhesive technologies. Technological advancements in polymer chemistry and formulation enable manufacturers to deliver products with improved bonding strength, faster curing times, and enhanced resistance to temperature, moisture, and chemicals.
Regionally, Asia Pacific dominates the Packaging Adhesive Market, supported by large-scale manufacturing hubs in China and India, rising urbanization, and expanding consumer goods industries. Europe and North America follow, driven by strict sustainability mandates, advanced packaging infrastructure, and the presence of leading adhesive suppliers. Emerging markets in Latin America and the Middle East & Africa are experiencing rapid growth due to increased investment in packaging production and rising demand for processed and packaged goods.
Market Insights:
- The Packaging Adhesive Market reached USD 19,567 million in 2024 and will climb to USD 30,234 million by 2032.
- Growth is driven by demand for lightweight, recyclable, and sustainable packaging materials in line with global regulations.
- E-commerce expansion and food safety standards boost adoption of solvent-free, water-based, and hot-melt adhesives.
- Technological advances deliver stronger, faster-curing adhesives with greater resistance to temperature and moisture.
- Asia Pacific holds 45% share, led by China and India, with rapid urbanization and manufacturing investment.
- Europe captures 23% share, focusing on bio-based adhesives, strict safety, and sustainability standards.
- North America holds 20% share, leveraging automation, logistics, and growing demand for smart, convenient packaging.
Market Drivers:
Shift Toward Lightweight and Sustainable Packaging Materials Fuels Adhesive Demand:
Brands and manufacturers in the Packaging Adhesive Market are prioritizing lightweight and eco-friendly packaging solutions to reduce transportation costs and environmental impact. This trend supports rising use of recyclable substrates, bio-based films, and compostable materials. The demand for specialized adhesives that bond effectively with these modern substrates is accelerating. Companies invest in research to develop solvent-free, water-based, and hot-melt adhesives with low VOC emissions, supporting sustainability goals.
- For instance, Henkel launched TECHNOMELT Supra 079 Eco Cool hot-melt adhesive, in which 49 percent of the raw materials are bio-based, achieving 32 percent lower CO₂ emissions and application temperatures 40°C lower than conventional products.
Rising E-Commerce Volumes and Product Safety Standards Drive Innovation:
Rapid expansion of e-commerce channels boosts demand for secure and tamper-evident packaging adhesives. It must ensure strong seals and protection throughout increasingly complex supply chains. Food and pharmaceutical companies rely on adhesives that meet stringent safety and regulatory standards for direct and indirect food contact. The growing need for reliable and compliant adhesive solutions pushes manufacturers to innovate and improve product formulations.
- For instance, 3M’s Scotch Recycled Corrugate Tape 3072 is specifically formulated to seal boxes with high recycled content and meets FDA requirements for indirect food contact, ensuring durable and regulatory-compliant closures for sensitive shipments.
Technological Advancements Enable Performance Improvements:
Developments in polymer chemistry and adhesive formulation lead to products with higher bonding strength, rapid curing, and greater resistance to temperature, moisture, and chemicals. The Packaging Adhesive Market benefits from technology that allows for quick changeovers and efficient production, which increases flexibility for packaging converters. Automation and advanced application equipment further support consistent adhesive performance and reduce operational downtime. These factors make adhesives an integral part of high-speed packaging lines.
Evolving Consumer Preferences Shape Packaging Design:
Consumer demand for attractive, resealable, and personalized packaging prompts brands to adopt advanced adhesive solutions that enable creative formats and user convenience. The Packaging Adhesive Market must support packaging innovations such as easy-open, peel-and-reseal, and multi-layer laminates. Adhesive suppliers collaborate closely with packaging designers to deliver products that enhance shelf appeal and improve end-user experience. This dynamic relationship fosters ongoing development in both packaging design and adhesive technology.
Market Trends:
Adoption of Bio-Based and Solvent-Free Adhesives Gains Momentum:
Sustainability initiatives are driving the widespread adoption of bio-based, solvent-free, and water-based adhesives in the Packaging Adhesive Market. Brands and packaging manufacturers seek to lower their carbon footprint by choosing adhesives that eliminate hazardous chemicals and volatile organic compounds (VOCs). Research and development efforts focus on formulating adhesives from renewable sources, such as plant-based polymers and naturally derived resins. This shift aligns with stringent global regulations and brand commitments to circular economy principles. The Packaging Adhesive Market witnesses rapid integration of these sustainable solutions, supported by growing consumer demand for eco-friendly packaging. Suppliers are responding by expanding product portfolios with green alternatives, enabling brands to meet evolving regulatory and consumer expectations.
- For instance, Bostik Born2Bond Ultra K85, rolled out in July 2025, is made from 60% bio-based raw materials and has demonstrated durability by withstanding 1,000 hours at 85°C and 85% humidity in the double 85 test, showcasing high-performance under rigorous industrial conditions.
Smart and Functional Packaging Drives Technological Advancements:
The rise of smart and functional packaging is prompting the Packaging Adhesive Market to innovate products that enhance package integrity, security, and user engagement. Adhesives must now support value-added features such as tamper-evidence, resealability, and compatibility with printed electronics. Increasing popularity of interactive packaging-featuring QR codes, RFID tags, and sensors-demands adhesives with high electrical resistance and stable bonding on multi-material substrates. Manufacturers invest in advanced chemistries to deliver adhesives suitable for diverse applications, from flexible pouches to rigid containers. The market also sees a growing emphasis on adhesives that withstand extreme temperatures and moisture, supporting product safety and shelf life. These technological advancements enable converters and brand owners to unlock new opportunities for differentiation and supply chain efficiency.
- For instance, Master Bond FL901S is a silver-filled epoxy film adhesive specially designed for electronic applications requiring high electrical conductivity, achieving a volume resistivity of less than 2 milliohms and performing reliably over a temperature range from -100°F to 400°F, supporting EMI/RFI shielding and advanced sensor packaging.
Market Challenges Analysis:
Stringent Regulatory Standards and Complex Compliance Requirements:
The Packaging Adhesive Market faces significant challenges from stringent regulatory standards governing chemical composition, migration, and safety. Governments across key regions enforce strict rules on volatile organic compounds (VOCs), heavy metals, and food-contact materials. Companies must continuously update product formulations to comply with evolving regulations in both established and emerging markets. This constant adaptation increases research and development costs, disrupts supply chains, and limits the introduction of new products. Navigating complex certification processes also creates barriers for smaller players seeking market entry.
Raw Material Price Volatility and Supply Chain Disruptions Impact Growth:
Volatility in the prices of raw materials such as resins, polymers, and specialty chemicals creates persistent cost pressures in the Packaging Adhesive Market. It must also address ongoing disruptions in global supply chains due to geopolitical tensions, transportation bottlenecks, and shifting trade policies. These issues impact production schedules, increase lead times, and make inventory planning difficult. Unpredictable cost structures and limited material availability constrain manufacturers’ ability to offer stable pricing and timely delivery. Sustained uncertainty across supply networks challenges both established brands and new entrants in maintaining competitiveness.
Market Opportunities:
Expansion of Eco-Friendly and Specialty Adhesive Solutions:
The Packaging Adhesive Market has significant opportunities in the development and commercialization of eco-friendly, bio-based, and specialty adhesive products. Increasing global focus on sustainability and circular economy principles drives demand for adhesives with low VOC content, renewable ingredients, and enhanced recyclability. Companies that innovate and offer adhesives compatible with biodegradable films, compostable substrates, and recycled packaging materials can gain a competitive edge. Investments in advanced research enable suppliers to address complex bonding challenges posed by new materials. This shift toward green adhesives supports both regulatory compliance and brand reputation, opening new growth avenues across industries.
Growth in High-Performance Applications and Emerging Markets:
The ongoing evolution of packaging formats, especially for e-commerce, pharmaceuticals, and food, presents expanding opportunities for high-performance adhesive solutions. The Packaging Adhesive Market benefits from the adoption of adhesives tailored for flexible, multilayer, and active packaging, where durability and reliability are critical. Emerging markets in Asia Pacific, Latin America, and Africa are experiencing rising demand for packaged goods, driving investments in modern packaging infrastructure. Manufacturers that establish local production capabilities and strategic partnerships can capitalize on this regional growth. Custom adhesive solutions for smart packaging and value-added applications further enhance market potential.
Market Segmentation Analysis:
By Product Type:
The Packaging Adhesive Market includes product segments such as water-based, solvent-based, hot-melt, and reactive adhesives. Water-based adhesives lead the segment due to their low VOC content and compatibility with paper, board, and flexible packaging. Hot-melt adhesives gain traction for their fast setting time and versatility across diverse substrates, supporting automation and high-speed production. Solvent-based adhesives remain important for specialty applications requiring strong bonds and chemical resistance. Reactive adhesives serve high-performance needs in advanced and multilayer packaging formats.
By Packaging Type:
The market serves flexible packaging, rigid packaging, and specialty formats. Flexible packaging commands the largest share, driven by demand in food, beverage, and personal care sectors. It enables lightweight designs and cost-effective solutions for both manufacturers and brands. Rigid packaging uses adhesives for carton sealing, labelling, and protective formats, catering to pharmaceutical and electronics industries. Specialty packaging-such as multi-layer laminates and eco-friendly solutions-requires advanced adhesive technologies to ensure integrity and sustainability.
- For instance, 3M™ Scotch-Weld™ Epoxy Adhesive 2216 offers a bonded shear strength of up to 3,200psi at room temperature, making it a go-to solution for appliance and electronics manufacturers who require robust, high-performance joints.
By Application:
The Packaging Adhesive Market addresses applications including case and carton sealing, labeling, flexible laminations, and specialty bonding. Case and carton sealing dominates due to widespread use in logistics and retail. Labeling applications require adhesives with excellent clarity and resistance properties. Flexible lamination adhesives support barrier packaging for snacks, dairy, and pharmaceutical products. Specialty bonding meets unique requirements for tamper-evident, peel-and-reseal, and smart packaging solutions.
- For instance, H.B. Fuller’s Advantra® Earthic™ 9500 adhesive enabled a major U.S. food manufacturer to reduce adhesive consumption by 37%, allowing 100kg of adhesive to seal 89,000 cartons compared to 66,667 with previous products
Segmentations:
By Product Type:
- Water-based adhesives
- Solvent-based adhesives
- Hot-melt adhesives
- Reactive adhesives
By Packaging Type:
- Flexible packaging
- Rigid packaging
- Specialty packaging
By Application:
- Case and carton sealing
- Labeling
- Flexible laminations
- Specialty bonding
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Regional Analysis:
Asia Pacific :
Asia Pacific holds 45% share of the Packaging Adhesive Market, supported by strong manufacturing bases in China, India, Japan, and South Korea. The region benefits from a robust consumer goods industry, rapid urbanization, and expanding e-commerce activity. Local and multinational manufacturers invest in advanced packaging technologies and sustainable adhesives to serve high-volume end-use sectors. Rising demand for packaged foods, pharmaceuticals, and personal care products further propels adhesive consumption. Regional governments enforce stricter safety and environmental regulations, accelerating the shift toward solvent-free and water-based adhesives. Investments in infrastructure and a skilled workforce support Asia Pacific’s leading position.
Europe:
Europe accounts for 23% share of the Packaging Adhesive Market, anchored by strong regulatory frameworks and advanced packaging infrastructure. The region’s focus on sustainability and circular economy principles drives adoption of bio-based and recyclable adhesive solutions. Leading suppliers collaborate with packaging converters and consumer brands to deliver compliant, high-performance products for food, beverage, and pharmaceutical applications. The market reflects high standards for product safety, low VOC emissions, and traceability across the supply chain. Growing investment in R&D supports continuous innovation, enabling Europe to maintain its status as a hub for green adhesive technology. Stringent legislation ensures market players prioritize both quality and environmental impact.
North America :
North America holds 20% share of the Packaging Adhesive Market, benefiting from strong logistics networks, advanced automation, and a mature packaging sector. Growth in e-commerce and demand for convenience products drive the need for innovative adhesive solutions. Manufacturers in the United States and Canada adopt high-speed production lines and invest in smart packaging capabilities. Strict regulatory oversight governs chemical safety and food contact materials, prompting suppliers to enhance formulation transparency. Consumer preferences for resealable, tamper-evident, and visually appealing packaging formats influence product development. Ongoing digitalization and supply chain optimization reinforce North America’s strategic market position.
Key Player Analysis:
- Jowat Corp
- Paramelt
- Sika
- Avery Dennison
- HB Fuller
- Wacker Chemie
- Bostik
- 3M
- Henkel
- Dymax
Competitive Analysis:
The Packaging Adhesive Market features intense competition among leading global and regional players, including Jowat Corp, Paramelt, Sika, Avery Dennison, HB Fuller, Wacker Chemie, and Bostik. It reflects strong innovation in sustainable adhesive formulations, smart packaging applications, and product customization to meet evolving regulatory and customer requirements. Companies leverage advanced R&D, extensive distribution networks, and technical service capabilities to differentiate offerings. Strategic collaborations, mergers, and acquisitions help market leaders expand their geographic reach and technology portfolios. The market rewards suppliers that deliver high-performance, compliant, and environmentally responsible adhesive solutions. Sustained investment in new product development and process optimization supports ongoing competitiveness across key end-use sectors.
Recent Developments:
- In Feb 2025, Wacker Chemie announced the start of two new production facilities for specialty silicones in Japan and South Korea to support the growing automotive and construction industries.
- In July, 2025, Bostik partnered with Axil to implement sustainable waste management at UK sites.
Market Concentration & Characteristics:
The Packaging Adhesive Market exhibits moderate to high concentration, with a mix of multinational giants and regional specialists shaping the competitive landscape. It features leading companies such as Henkel, H.B. Fuller, 3M, and Sika, which leverage robust R&D, global distribution, and diverse product portfolios. Intense competition drives continuous innovation in sustainable, high-performance, and regulatory-compliant adhesive solutions. The market favors suppliers with advanced technical support, strong customer relationships, and the ability to customize products for specialized applications. High entry barriers exist due to stringent regulatory requirements and the need for significant investment in technology and certification. Strategic partnerships, mergers, and acquisitions play a key role in expanding market reach and capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Packaging Type, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Fuse adhesive chemistry with sustainability to support biodegradable substrates and circular economy goals.
- Deploy solution platforms that integrate smart features like tamper-evident and resealable functionality.
- Expand regional production capacity in high-growth areas such as Asia Pacific and Latin America.
- Leverage automation and digital application systems for precise adhesive placement and reduced waste.
- Strengthen collaborations between adhesive suppliers, packaging converters, and consumer brands to drive product customization.
- Prioritize low‑VOC, solvent-free, and bio-based adhesive formulations to meet tightening environmental regulations.
- Integrate real‑time quality monitoring in adhesive production lines to ensure consistency and regulatory compliance.
- Pursue mergers, joint ventures, and acquisitions to enter new markets and build technical expertise.
- Develop adhesives tailored to emerging packaging materials, such as multi-layer laminates and recycled plastics.
- Support circular packaging models through adhesives that facilitate easy separability and recyclability of packaging layers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Lightweight and Sustainable Packaging
Brands and manufacturers are increasingly adopting lightweight, recyclable, and eco-friendly packaging materials to reduce transportation costs and environmental impact, driving demand for specialized adhesives compatible with these substrates.
E-Commerce Expansion and Food Safety Standards
The rapid growth of e-commerce and stricter food safety regulations are boosting the need for secure, tamper-evident, and compliant adhesive solutions that ensure product integrity and regulatory compliance throughout complex supply chains.
Technological Advancements in Adhesive Formulation
Innovations in polymer chemistry and adhesive technology are enabling the development of products with higher bonding strength, faster curing times, and improved resistance to temperature, moisture, and chemicals, supporting high-speed and automated packaging lines.
Adoption of Bio-Based and Solvent-Free Adhesives
Sustainability initiatives and regulatory pressures are accelerating the shift toward bio-based, water-based, and solvent-free adhesives, as brands seek to lower VOC emissions and align with circular economy principles.
Growth in Smart and Functional Packaging
The rise of smart packaging formats requiring features like resealability, tamper-evidence, and compatibility with printed electronics is driving demand for advanced adhesives that support innovative packaging designs and enhanced consumer engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Packaging Adhesives Market?
What factors are driving the growth of the Packaging Adhesives Market?
What are the key segments within the Packaging Adhesives Market?
What are some challenges faced by the Packaging Adhesives Market?
Who are the major players in the Packaging Adhesives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Case and carton sealing
- 1.2.2 Labeling
- 1.2.3 Flexible laminations
- 1.2.4 Specialty bonding
- 1.3 By Product Type
- 1.3.1 Water-based adhesives
- 1.3.2 Solvent-based adhesives
- 1.3.3 Hot-melt adhesives
- 1.3.4 Reactive adhesives
- 1.4 By Packaging Type
- 1.4.1 Flexible packaging
- 1.4.2 Rigid packaging
- 1.4.3 Specialty packaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 19,567 million → 2032: USD 30,234 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Packaging Adhesives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Packaging Adhesives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Packaging Adhesives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Packaging Adhesives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Packaging Adhesives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Packaging Adhesives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Packaging Adhesives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Packaging Adhesives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 19,567 million → 2032: USD 30,234 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Packaging Adhesives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Case and carton sealing
- 12.3.7.2 Labeling
- 12.3.7.3 Flexible laminations
- 12.3.7.4 Specialty bonding
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Water-based adhesives
- 12.4.7.2 Solvent-based adhesives
- 12.4.7.3 Hot-melt adhesives
- 12.4.7.4 Reactive adhesives
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flexible packaging
- 12.5.7.2 Rigid packaging
- 12.5.7.3 Specialty packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Packaging Adhesives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Packaging Adhesives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Packaging Adhesives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Packaging Adhesives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Henkel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 H.B. Fuller
- 18.4 3M
- 18.5 Bostik
- 18.6 Sika
- 18.7 Avery Dennison
- 18.8 Jowat Corp
- 18.9 Paramelt
- 18.10 Wacker Chemie
- 18.11 Dymax
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

