
Market Overview
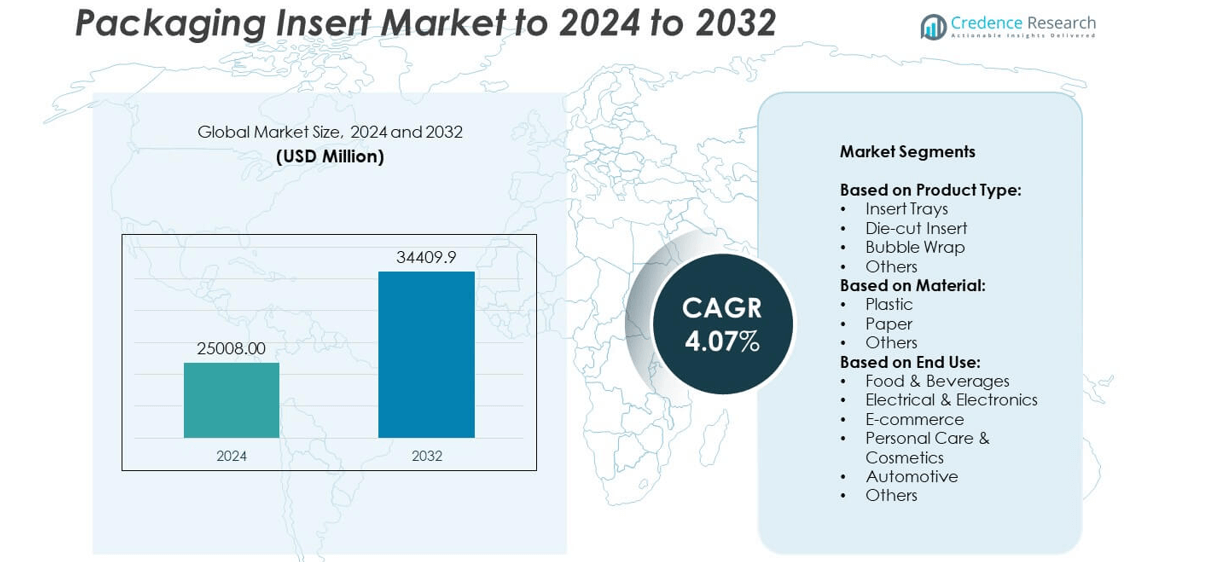
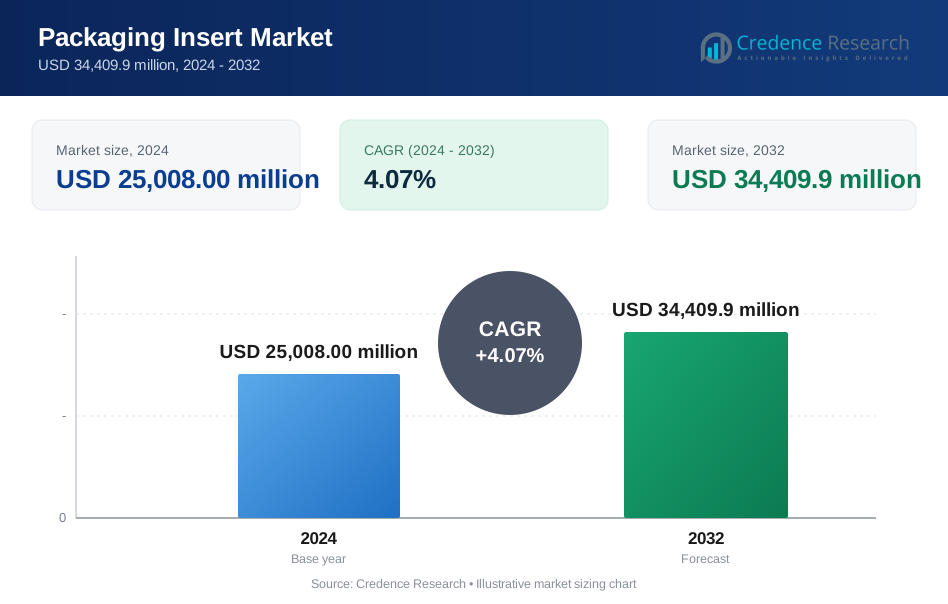
Packaging Insert Market size was valued at USD 25,008.00 million in 2024 and is anticipated to reach USD 34,409.9 million by 2032, at a CAGR of 4.07% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Packaging Insert Market Size 2024 | USD 25,008.00 million |
| Packaging Insert Market, CAGR | 4.07% |
| Packaging Insert Market Size 2032 | USD 34,409.9 million |
The packaging insert market is driven by key players such as Ranpak, Smurfit Kappa, Reflex Packaging Inc., DS Smith, EcoEnclose, Sonoco, Salazar Packaging, Index Packaging, Inc., Huhtamaki, Visipak, and Pregis. These companies focus on developing innovative, sustainable, and cost-efficient insert solutions to serve industries such as e-commerce, food and beverages, and electronics. Strategic investments in recyclable and biodegradable materials are gaining momentum as sustainability becomes a priority. Regionally, North America leads the market with about 35% share, supported by strong e-commerce growth and advanced packaging infrastructure, followed by Europe with 28% and Asia Pacific with 25% share.
Market Insights
- The packaging insert market was valued at USD 25,008.00 million in 2024 and is projected to reach USD 34,409.9 million by 2032, growing at a CAGR of 4.07%.
- Growth is fueled by e-commerce expansion, rising demand for product protection, and a shift toward sustainable packaging solutions across industries.
- Key trends include increasing use of customized inserts for branding, adoption of recyclable and bio-based materials, and growing demand for smart inserts with tracking features.
- The market is competitive with players focusing on innovation, automation, and strategic collaborations to expand global presence and meet sustainability goals.
- North America leads with 35% share, followed by Europe at 28% and Asia Pacific at 25%, while insert trays dominate the product segment with over 40% market share in 2024.
Market Segmentation Analysis:
By Product Type
Insert trays dominated the packaging insert market with over 40% share in 2024. Their high adoption is driven by their ability to securely hold products and reduce movement during transit. Insert trays are widely used in food, electronics, and personal care packaging due to their precise fit and protection. Die-cut inserts follow closely, supporting custom-shaped products and enhancing brand presentation. Bubble wrap continues to serve as a cost-effective protective solution, particularly in e-commerce shipping. Demand for sustainable and biodegradable insert trays is rising, pushing manufacturers to innovate with eco-friendly materials and designs.
- For instance, In 2024, Huhtamaki expanded its manufacturing of smooth molded fiber (SMF) lids to its Lurgan, Northern Ireland facility. This added to its existing molded fiber sites in Germany, the Netherlands, and the USA. Huhtamaki's 2024 annual report detailed net sales of EUR 4.126 billion, a slight drop from 2023's EUR 4.169 billion, while adjusted EBIT rose 6% to EUR 417 million and overall volumes saw a slight increase. By the end of 2024, the company operated 101 locations in 36 countries, employing approximately 18,000 professionals.
By Material
Plastic accounted for the largest share, holding around 55% of the packaging insert market in 2024. Its dominance stems from durability, flexibility, and superior cushioning properties that safeguard fragile goods. Plastic inserts are preferred in electronics, automotive, and food packaging due to moisture resistance and extended shelf life. Paper-based inserts are gaining momentum as sustainability concerns drive the shift toward recyclable and biodegradable materials. The “others” category includes foam and bio-based materials, which cater to niche segments. Increasing environmental regulations and consumer preference for green packaging are boosting investments in paper and compostable plastic alternatives.
- For instance, in May 2024, Smurfit Kappa inaugurated a new corrugated cardboard packaging plant in Guarne, Colombia, with an investment of over $50 million, to meet growing demand for sustainable packaging.
By End Use
Food & beverages led the market with nearly 30% share in 2024, fueled by the rising demand for protective packaging that maintains product integrity during transport. Insert trays and die-cut solutions are widely used for confectionery, ready-to-eat meals, and beverage bottles. E-commerce is the fastest-growing segment, supported by booming online shopping and the need for protective, lightweight inserts. Electronics and personal care industries also contribute significantly, using inserts for premium product presentation and damage prevention. Automotive end use continues to expand with custom inserts for spare parts, while sustainability initiatives are driving the adoption of recyclable solutions.
Market Overview
Rising E-commerce and Online Retail
The surge in e-commerce is the key growth driver for the packaging insert market. Growing demand for secure, attractive, and cost-effective packaging solutions is pushing companies to use insert trays, die-cut inserts, and bubble wraps. These solutions ensure product safety during long-distance shipping and enhance customer unboxing experience. Brands are investing in customized inserts to boost brand visibility and reduce return rates. The rapid growth of online retail platforms and increasing consumer preference for home delivery services continue to strengthen this driver across multiple regions.
- For instance, in 2024, Mondi launched and showcased numerous fiber-based packaging innovations at events like Fachpack, including its broad FunctionalBarrier Paper range, designed for various applications such as food and non-food contact packaging, that can be recycled in existing paper waste streams across Europe. The company also highlighted its TrayWrap solution, a secondary paper packaging that replaces plastic shrink film for bundling food and beverage products and is made from 100% kraft paper.
Focus on Product Protection and Damage Reduction
Product protection is a major growth driver as companies prioritize minimizing product damage and logistics losses. Packaging inserts offer cushioning, secure placement, and separation of items, which is essential for fragile goods in food, electronics, and personal care sectors. Industries are adopting specialized inserts to meet strict quality and safety standards while improving supply chain efficiency. Rising logistics costs are encouraging companies to invest in protective solutions to reduce returns and wastage. This trend supports the steady adoption of innovative insert materials and designs globally.
- For instance, in 2024, Sealed Air reported sales of $5.39 billion, a decrease of 1.8% compared to the previous year. The company's global operations served customers in 117 countries and territories and employed approximately 16,400 individuals.
Shift Toward Sustainable Packaging
Sustainability is a key growth driver as consumers and regulators push for eco-friendly solutions. Brands are replacing single-use plastic inserts with recyclable paper, bio-based, and compostable materials. This shift is driven by regulations on plastic waste reduction and corporate sustainability targets. Companies are focusing on lightweight, recyclable inserts to minimize environmental impact and appeal to eco-conscious customers. This transition is also creating opportunities for material innovation and strengthening the market presence of sustainable packaging suppliers worldwide.
Key Trends & Opportunities
Customization and Branding Demand
A key trend is the rising demand for customized inserts that enhance product presentation and create brand identity. Personalized packaging inserts are being used to improve customer experience and increase brand recall. Companies are offering printed inserts with promotional messages, QR codes, or brand stories to engage customers. This trend is opening opportunities for packaging manufacturers to offer value-added services, including digital printing and design customization, catering to e-commerce brands and premium product manufacturers.
- For instance, in September 2022, WestRock announced the acquisition of an HP PageWide T1190 Press to expand its corrugated printing capabilities. The press was scheduled to be installed in 2023 to enable high-quality digital printing, including features like serialization to support brand engagement programs and traceability. In March 2024, WestRock was ranked among the top 200 U.S. companies on Fortune's list of America's Most Innovative Companies.
Growth of Smart and Innovative Inserts
Another major opportunity lies in the adoption of smart packaging inserts equipped with QR codes, RFID tags, or sensors. These features help track shipments, share product information, and improve transparency in the supply chain. Brands are exploring interactive packaging to engage tech-savvy customers and provide post-purchase support. Innovative inserts also include foldable or modular designs to reduce storage costs. The combination of technology and packaging functionality is expected to boost growth, particularly in electronics, healthcare, and luxury product segments.
- For instance, in January 2024, Sonoco announced the divestiture of its Protective Solutions business to Black Diamond Capital Management, LLC, for an estimated $80 million in cash. The transaction was completed in April 2024, within the originally projected first half of the year.
Key Challenges
High Raw Material and Production Costs
One of the key challenges is the rising cost of raw materials such as plastic resins and specialty paper. Price fluctuations increase production costs, impacting the profit margins of packaging manufacturers. Small and medium enterprises struggle to balance cost and quality while meeting customer expectations. Additionally, investments in eco-friendly materials and compliance with sustainability regulations add to overall expenses. Companies are exploring cost optimization strategies and bulk procurement to offset these challenges without compromising performance and design.
Environmental Regulations and Compliance
Stringent environmental regulations present a key challenge for market players, especially those dependent on plastic-based inserts. Governments worldwide are imposing bans and restrictions on single-use plastics, forcing manufacturers to switch to sustainable alternatives. Compliance with recycling, labeling, and waste management laws adds operational complexity and cost. Companies that fail to adopt eco-friendly solutions risk losing contracts from large retailers and e-commerce firms that have strict sustainability requirements. This challenge is driving a gradual industry shift toward greener materials and processes.
Regional Analysis
North America
North America held the largest share of around 35% of the packaging insert market in 2024. The region benefits from strong e-commerce growth, advanced retail infrastructure, and a high focus on product protection standards. Demand is supported by leading packaging manufacturers investing in sustainable and customized inserts to meet consumer preferences. The U.S. dominates the regional market, driven by high online shopping penetration and strict quality regulations. Growth in food and beverage packaging, along with innovation in protective solutions for electronics and personal care sectors, continues to strengthen market presence across North America during the forecast period.
Europe
Europe accounted for nearly 28% of the packaging insert market in 2024, supported by strong emphasis on sustainability and strict packaging regulations. Countries like Germany, France, and the U.K. are leading adopters of paper-based and recyclable insert solutions. Demand is rising from food, cosmetics, and premium product manufacturers focusing on eco-friendly packaging to meet EU directives. Technological advancements in lightweight inserts and growing e-commerce adoption are fueling market expansion. The region’s focus on circular economy practices and high investment in design innovation further drives adoption, making Europe a major contributor to global packaging insert market growth.
Asia Pacific
Asia Pacific captured around 25% market share in 2024, making it the fastest-growing region in the packaging insert market. Rapid industrialization, booming e-commerce, and expanding middle-class populations in China, India, and Southeast Asia drive demand. The region is witnessing rising investments in protective and low-cost packaging solutions to cater to growing consumption. Local manufacturers are increasingly adopting paper-based and bio-based inserts to meet sustainability goals. Strong demand from electronics, automotive, and food sectors further boosts growth. Government initiatives to promote domestic manufacturing and exports are creating significant opportunities for packaging insert producers in the region.
Latin America
Latin America represented about 7% of the packaging insert market in 2024, driven by growing adoption of protective packaging in food, personal care, and e-commerce sectors. Brazil and Mexico are the key contributors, supported by rising consumer spending and digital retail expansion. Manufacturers are increasingly offering cost-effective and customizable solutions to meet diverse industry needs. However, limited adoption of advanced packaging technology compared to developed markets slightly restricts growth. Sustainability initiatives and the shift toward recyclable packaging materials are gaining momentum, creating opportunities for innovation and partnerships with global packaging companies in the region.
Middle East & Africa
Middle East & Africa accounted for nearly 5% of the packaging insert market in 2024, with demand supported by growing retail infrastructure and increasing consumption of packaged goods. The UAE and Saudi Arabia lead the regional market due to rising e-commerce and premium product demand. The region is gradually adopting sustainable packaging practices as awareness of environmental impact grows. Growth is further driven by the expansion of the food, cosmetics, and pharmaceutical industries. Challenges include limited local manufacturing capacity and reliance on imports, but ongoing investments in production facilities are expected to improve supply chain efficiency.
Market Segmentations:
By Product Type:
- Insert Trays
- Die-cut Insert
- Bubble Wrap
- Others
By Material:
- Plastic
- Paper
- Others
By End Use:
- Food & Beverages
- Electrical & Electronics
- E-commerce
- Personal Care & Cosmetics
- Automotive
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The packaging insert market is characterized by strong competition, with key players including Ranpak, Smurfit Kappa, Reflex Packaging Inc., DS Smith, EcoEnclose, Sonoco, Salazar Packaging, Index Packaging, Inc., Huhtamaki, Visipak, and Pregis. These companies focus on delivering innovative, sustainable, and cost-effective insert solutions to cater to growing demand from e-commerce, food, and electronics sectors. The market is witnessing high investment in recyclable and biodegradable materials as regulatory pressure and consumer demand for eco-friendly packaging rise. Players are also emphasizing design customization, lightweight solutions, and automation to improve efficiency and reduce logistics costs. Strategic collaborations, capacity expansions, and technological innovations are common approaches used to strengthen market share. Additionally, increasing adoption of smart packaging solutions with digital printing and branding features is reshaping competitive dynamics, encouraging continuous product development and differentiation among manufacturers to gain a competitive edge across global and regional markets.
Key Player Analysis
- Ranpak
- Smurfit Kappa
- Reflex Packaging Inc.
- DS Smith
- EcoEnclose
- Sonoco
- Salazar Packaging
- Index Packaging, Inc.
- Huhtamaki
- Visipak
- Pregis
Recent Developments
- In 2025, Ranpak company expanded its automated product line, including the introduction of Pad’it!™, a system that automatically inserts paper pads into boxes to protect goods.
- In 2025, DS Smith At PharmaPack Europe, unveiled TailorTemp, a fully fiber-based, temperature-controlled packaging line for pharmaceuticals.
- In 2022, Pregis introduced Renew Zero, their first carbon-neutral protective packaging film, in Europe, which uses a 50/50 blend of post-consumer recycled content and certified renewable plant waste to reduce its environmental footprint.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see steady growth driven by e-commerce expansion and online retail demand.
- Sustainable and recyclable inserts will gain wider adoption due to strict environmental regulations.
- Customization and branding on inserts will become a major differentiator for manufacturers.
- Smart inserts with QR codes and tracking features will grow in adoption for transparency.
- Demand from food and beverage and electronics sectors will remain strong during the forecast period.
- Asia Pacific will emerge as the fastest-growing region due to rising manufacturing and exports.
- Lightweight and cost-efficient designs will be prioritized to reduce shipping and logistics costs.
- Strategic partnerships and mergers will rise as players focus on expanding global presence.
- Technological innovations in materials and automation will improve production efficiency and output.
- Consumer preference for eco-friendly packaging will push innovation toward bio-based and compostable inserts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
E-commerce Expansion
The rapid growth of online retail and e-commerce platforms is driving demand for packaging inserts that protect products during shipping, enhance unboxing experiences, and reduce return rates, especially for fragile and high-value goods.
Focus on Product Protection
Manufacturers and retailers are prioritizing product protection to minimize damage and logistics losses, leading to increased adoption of insert trays, die-cut inserts, and bubble wrap that provide secure placement and cushioning for a wide range of products.
Shift Toward Sustainable Packaging
Rising consumer awareness and regulatory pressure around environmental sustainability are pushing companies to adopt recyclable, biodegradable, and compostable insert materials, fueling innovation and investment in eco-friendly packaging solutions.
Customization and Branding
Brands are increasingly using customized packaging inserts for enhanced product presentation, brand identity, and customer engagement, leveraging digital printing and design personalization to differentiate their offerings in competitive markets.
Adoption of Smart and Innovative Inserts
The integration of smart features such as QR codes, RFID tags, and modular designs in packaging inserts is enabling better tracking, supply chain transparency, and interactive customer experiences, particularly in electronics, healthcare, and premium product segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Packaging Insert Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Packaging Insert Market projected to grow between 2025 and 2032?
Which Packaging Insert Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Packaging Insert Market?
Who are the leading companies in the Packaging Insert Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Food & Beverages
- 1.2.2 Electrical & Electronics
- 1.2.3 E-commerce
- 1.2.4 Personal Care & Cosmetics
- 1.2.5 Automotive
- 1.2.6 Others
- 1.3 By Material
- 1.3.1 Plastic
- 1.3.2 Paper
- 1.3.3 Others
- 1.4 By Product Type
- 1.4.1 Insert Trays
- 1.4.2 Die-cut Insert
- 1.4.3 Bubble Wrap
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,008.00 million → 2032: USD 34,409.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Packaging Insert Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Packaging Insert Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Packaging Insert Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Packaging Insert Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Packaging Insert Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Packaging Insert Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Packaging Insert Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Packaging Insert Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,008.00 million → 2032: USD 34,409.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Packaging Insert Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food & Beverages
- 12.3.7.2 Electrical & Electronics
- 12.3.7.3 E-commerce
- 12.3.7.4 Personal Care & Cosmetics
- 12.3.7.5 Automotive
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plastic
- 12.4.7.2 Paper
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Insert Trays
- 12.5.7.2 Die-cut Insert
- 12.5.7.3 Bubble Wrap
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Packaging Insert End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Packaging Insert Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Packaging Insert Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Packaging Insert Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ranpak
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smurfit Kappa
- 18.4 Reflex Packaging Inc.
- 18.5 DS Smith
- 18.6 EcoEnclose
- 18.7 Sonoco
- 18.8 Salazar Packaging
- 18.9 Index Packaging, Inc.
- 18.10 Huhtamaki
- 18.11 Pregis
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

