
Market Overview
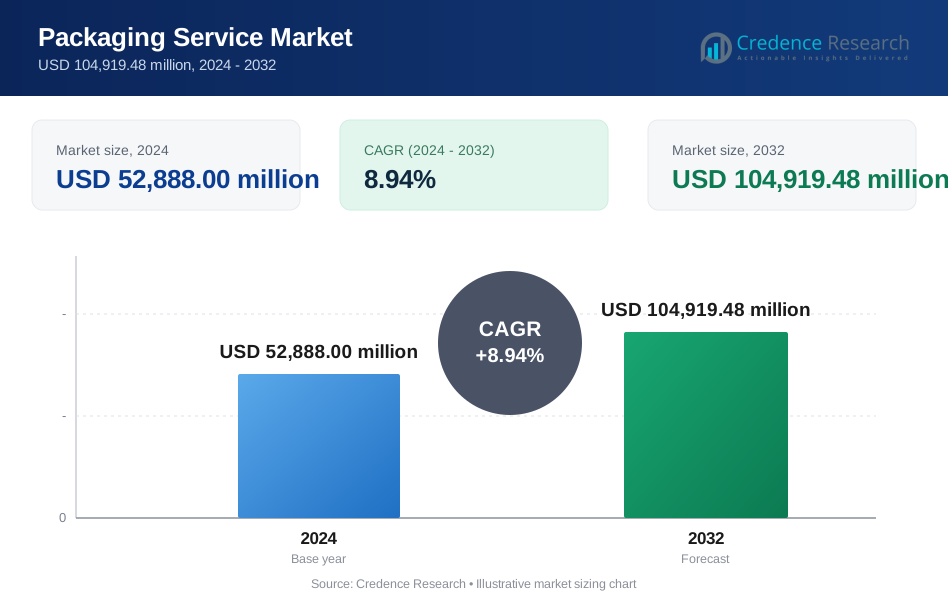
The Packaging Service Market was valued at USD 52,888.00 million in 2024 and is projected to reach USD 104,919.48 million by 2032, growing at a CAGR of 8.94% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Packaging Service Market Size 2024 | USD 52,888.00 Million |
| Packaging Service Market, CAGR | 8.94% |
| Packaging Service Market Size 2032 | USD 104,919.48 Million |
The packaging service market is led by major players including Mondi Group, Graphic Packaging International Inc, Crown Holdings, Inc, Sonoco Products Company, International Paper, DS Smith Plc, Amcor Ltd., AptarGroup Inc, Nippon Paper Industries Co. Ltd., and Anchor Packaging. These companies focus on sustainable materials, innovative designs, and automation to meet rising demand from food, beverage, and e-commerce sectors. North America holds 34% share, driven by strong adoption of advanced packaging solutions and regulatory compliance. Europe accounts for 30% share, supported by strict sustainability mandates, while Asia Pacific captures 25% share and remains the fastest-growing region due to rapid industrialization, urbanization, and booming e-commerce activity.
 Market Insights
- The packaging service market was valued at USD 52,888.00 million in 2024 and is projected to reach USD 104,919.48 million by 2032, growing at a CAGR of 8.94%.
- Rising demand from the food and beverage sector and rapid growth of e-commerce are driving the need for flexible, secure, and sustainable packaging solutions.
- Key trends include adoption of recyclable materials, digital printing for customization, and smart packaging technologies that enhance supply chain visibility and branding.
- The market is competitive with players such as Mondi Group, Amcor Ltd., International Paper, DS Smith Plc, and Graphic Packaging International Inc focusing on innovation, acquisitions, and capacity expansion to strengthen global presence.
- North America leads with 34% share, Europe follows with 30%, and Asia Pacific holds 25%; bags and pouches dominate with over 35% share by product type, while food and beverages remain the largest end-use segment with more than 40% share.
Market Segmentation Analysis:
By Material
Plastic dominated the packaging service market in 2024, holding over 50% share due to its versatility, cost-effectiveness, and durability. Its widespread use in flexible packaging such as pouches, wraps, and bottles makes it the preferred choice for food, beverages, and consumer goods. Plastic’s lightweight nature reduces transportation costs and supports high-volume production, driving adoption across industries. Paper and paperboard are gaining share as sustainable alternatives, driven by regulations and consumer demand for eco-friendly solutions. The “others” category, including bio-based materials, is growing in niche applications where recyclability and compostability are critical.
- For instance, Amcor’s lightweighting initiatives include developing technology that reduces the weight of PET bottle finishes by over 50%, with one notable example being the introduction of a 1 L carbonated soft drink bottle made entirely from post-consumer recycled (PCR) content in April 2024.
By Product Type
Bags and pouches led the market with over 35% share in 2024, driven by their convenience, resealability, and ability to preserve product freshness. These formats are widely used for snacks, ready-to-eat meals, and personal care items. Boxes and cartons follow closely, supported by strong demand from e-commerce and retail for secure, stackable, and customizable packaging. Trays and clamshells hold a significant share in fresh produce, meat, and bakery packaging, offering visibility and protection. The remaining share is held by wraps, mailers, and specialty formats designed for lightweight and fragile goods.
- For instance, the merger between Smurfit Kappa and WestRock closed on July 5, 2024, to form Smurfit Westrock. Smurfit Kappa also launched its first Design2Market Factory, which includes digital printing, in the Netherlands in 2022.
By End Use
Food and beverages accounted for more than 40% share in 2024, making it the largest end-use segment for packaging services. Rising consumption of packaged food, convenience products, and ready-to-drink beverages is fueling demand for innovative and sustainable packaging. Consumer goods follow, supported by robust e-commerce growth and the need for protective, tamper-proof solutions. Personal care and cosmetics contribute significantly with demand for premium, branded packaging that enhances shelf appeal. The “others” category includes pharmaceuticals and electronics, where precision packaging is essential to ensure product safety during handling and transport.
Key Growth Drivers
Rising Demand from Food and Beverage Industry
The food and beverage sector drives significant demand for packaging services, accounting for over 40% market share in 2024. Growth is fueled by rising consumption of packaged snacks, ready-to-eat meals, and beverages, requiring safe and attractive packaging. Brand owners focus on innovative formats like resealable pouches and portion packs to enhance convenience and reduce waste. Increasing regulatory requirements for food safety and labeling compliance further support service providers offering advanced solutions, such as tamper-evident seals and sustainable materials, boosting adoption across the industry.
- For instance, in 2024, Nestlé's European operations have continued to roll out new paper-based and other sustainable packaging innovations across its product portfolio. In September 2024, Nestlé announced several paper packaging initiatives, including a new high-barrier paper refill pack for Nescafé in the UK and new paper-body packaging for its Nescafé Cappuccino range in Europe, which is fully recyclable.
Expansion of E-commerce and Retail Channels
Rapid e-commerce growth is creating strong demand for secure, protective, and customizable packaging services. Consumers expect damage-free deliveries and premium unboxing experiences, driving demand for mailers, cartons, and branded packaging. Service providers are offering scalable solutions to meet seasonal surges and quick turnaround requirements. Retailers and online platforms are increasingly collaborating with packaging companies to improve supply chain efficiency, reduce returns, and enhance brand visibility through innovative packaging formats, directly contributing to the overall growth of the packaging service market.
- For instance, Amazon announced in May 2025 that it would install hundreds of automated, made-to-fit packaging machines across its European fulfillment network, with deployment continuing through 2027. This was part of its ongoing sustainability efforts, which included removing plastic air pillows from its global delivery packaging by October 2024
Shift Toward Sustainable and Eco-Friendly Solutions
Rising environmental awareness and regulatory pressure are pushing brands toward sustainable packaging. Service providers are adopting paperboard, recyclable plastics, and biodegradable materials to reduce carbon footprint and meet extended producer responsibility (EPR) mandates. The focus is on lightweight packaging that minimizes waste while maintaining product protection. Companies are also investing in circular economy models, enabling reuse and recycling of packaging materials. This sustainability-driven transition not only supports compliance but also strengthens brand image, making it a key driver for growth in the packaging service market.
Key Trends & Opportunities
Adoption of Digital Printing and Smart Packaging
Digital printing technologies are enabling customization and faster turnaround times, allowing brands to launch limited-edition packaging and improve marketing campaigns. Smart packaging with QR codes and NFC tags is gaining traction, offering traceability, anti-counterfeiting features, and consumer engagement through interactive experiences. This trend creates opportunities for service providers to add value beyond protection, turning packaging into a communication and branding tool.
- For instance, HP Indigo's 2024 operations in the digital printing sector continued its focus on expanding its labels and packaging portfolio for industries like food, cosmetics, and pharmaceuticals. At major trade shows such as drupa and Labelexpo India in 2024, HP showcased new and advanced presses like the HP Indigo 200K, which offers a 30% increase in speed over its predecessor, and the high-volume HP Indigo 100K and 120K presses, capable of speeds up to 6,000 sheets per hour.
Growth in Subscription and Direct-to-Consumer Models The rise of subscription boxes and D2C models is boosting demand for visually appealing, durable, and personalized packaging. Companies seek solutions that enhance unboxing experiences and reflect brand identity. This shift presents opportunities for service providers to offer flexible production runs, innovative designs, and cost-efficient solutions that cater to diverse product categories, from food kits to fashion accessories.
- For instance, Packlane provides on-demand, customized packaging solutions for brands using digital print lines. The company caters to businesses of all sizes, and while it allows clients to order custom corrugated boxes starting with a minimum order quantity of one unit, some specialty products like paperboard cartons or certain high-definition finishes have higher minimums.
Key Challenges
Volatility in Raw Material Prices
Fluctuating costs of plastic resins, paperboard, and specialty coatings pose challenges for packaging service providers. Rising input costs impact profitability, especially for businesses operating on thin margins. Service providers are under pressure to optimize procurement strategies and explore alternative materials to maintain cost competitiveness while ensuring consistent quality for clients.
Compliance with Environmental Regulations
Strict global regulations on single-use plastics, packaging waste, and recyclability increase compliance costs for packaging service providers. Companies must continuously adapt designs and materials to meet evolving standards, which can lengthen product development cycles and raise expenses. Smaller players often struggle to meet these requirements, creating barriers to entry and expansion in highly regulated markets.
Regional Analysis
North America
North America held 34% share of the packaging service market in 2024, driven by high demand from food and beverage manufacturers, e-commerce platforms, and consumer goods companies. The United States leads with strong adoption of innovative packaging formats and automation technologies. Growth is further supported by sustainability regulations pushing companies toward recyclable and compostable materials. Canada contributes with rising packaged food consumption and retail sector expansion. Service providers in this region focus on quick turnaround times, customization, and premium branding solutions to meet consumer expectations and enhance supply chain efficiency.
Europe
Europe accounted for 30% share in 2024, supported by strict packaging waste regulations and a strong focus on sustainability. Key markets such as Germany, France, and the UK are driving demand for recyclable, lightweight, and eco-friendly packaging formats. Growth is supported by innovation in paper-based solutions and digital printing technologies for customization. The region also benefits from the thriving fashion and personal care sectors, which demand premium, aesthetically appealing packaging. Increasing investments in automation and adoption of circular economy models continue to shape the competitive landscape for packaging service providers.
Asia Pacific
Asia Pacific captured 25% share of the packaging service market in 2024 and remains the fastest-growing region. China, India, and Japan are leading markets, driven by rapid industrialization, urbanization, and booming e-commerce. Rising consumption of packaged food, cosmetics, and consumer goods fuels demand for flexible and cost-effective packaging solutions. Regional players are investing in expanding production capacity and adopting sustainable materials to meet regulatory and consumer expectations. Government initiatives supporting domestic manufacturing and logistics infrastructure are further boosting demand for packaging services across diverse end-use industries.
Latin America
Latin America held 6% share in 2024, with Brazil and Mexico dominating the regional market. Rising disposable incomes and growing demand for packaged food and beverages are key drivers. E-commerce expansion is further increasing the need for durable, tamper-proof, and visually appealing packaging formats. Service providers are introducing affordable solutions tailored to regional preferences while focusing on sustainability. Investment in local manufacturing capabilities is improving availability and reducing reliance on imports, which supports steady growth across industries such as retail, consumer goods, and pharmaceuticals in the region.
Middle East & Africa
The Middle East & Africa region accounted for 5% share of the packaging service market in 2024, driven by expanding retail networks, tourism, and food processing industries. The UAE and Saudi Arabia are leading markets, focusing on premium packaging for luxury goods and food exports. South Africa supports growth with rising demand for FMCG and personal care products. Service providers are investing in cost-effective, sustainable materials and smart packaging solutions to meet consumer and regulatory demands. Growth is supported by infrastructure development and rising adoption of e-commerce platforms across urban centers.
Market Segmentations:
By Material
- Plastic
- Paper & Paperboard
- Others
By Product Type
- Bags & Pouches
- Boxes & Cartons
- Trays & Clamshells
- Others
By End Use
- Food & Beverages
- Consumer Goods
- Personal Care & Cosmetics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the packaging service market includes major players such as Mondi Group, Graphic Packaging International Inc, Crown Holdings, Inc, Sonoco Products Company, International Paper, DS Smith Plc, Amcor Ltd., AptarGroup Inc, Nippon Paper Industries Co. Ltd., and Anchor Packaging. These companies focus on offering innovative, sustainable, and cost-efficient packaging solutions to cater to diverse industries including food and beverages, consumer goods, and personal care. Strategic initiatives such as mergers, acquisitions, and capacity expansions are common as players aim to strengthen their global footprint. Sustainability remains a key focus, with investments in recyclable materials, biodegradable packaging, and lightweight designs to comply with regulatory standards. Digital printing, smart packaging, and automation technologies are being adopted to enhance product differentiation and improve efficiency. The market remains moderately competitive, with global leaders competing alongside regional players to deliver customized and quick-turnaround services to meet evolving customer needs.
Key Player Analysis
- Mondi Group
- Graphic Packaging International Inc
- Crown Holdings, Inc
- Sonoco Products Company
- International Paper
- DS Smith Plc
- Amcor Ltd.
- AptarGroup Inc
- Nippon Paper Industries Co. Ltd.
- Anchor Packaging
Recent Developments
- In September 2025, Mondi Group introduced white digital printing for corrugated packaging to improve branding and shelf visibility.
- In June 2025, Sonoco Products Company announced expansion of its paper-can lines in four U.S. facilities to meet increasing demand for rigid paper cans with paper bottoms.
- In May 2025, Graphic Packaging International Inc. launched a new paperboard portfolio (clamshells, trays, pagoda-style boxes) to support foodservice operators in Europe with regulatory compliance.
- In April 2025, Mondi Group completed acquisition of Western Europe packaging assets from Schumacher Packaging to expand service capacity.
Report Coverage
The research report offers an in-depth analysis based on Material, Product Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sustainable and recyclable packaging solutions will continue to grow across industries.
- E-commerce expansion will boost the need for secure, lightweight, and tamper-proof packaging formats.
- Digital printing adoption will rise, enabling greater customization and shorter production runs.
- Smart packaging with QR codes and tracking features will enhance consumer engagement and transparency.
- Asia Pacific will remain the fastest-growing region, driven by industrialization and online retail growth.
- Automation in packaging services will improve efficiency and reduce lead times for bulk orders.
- Food and beverage packaging demand will dominate, with focus on freshness and convenience.
- Partnerships and acquisitions will expand the global reach of key packaging service providers.
- Premium packaging demand will rise in personal care, cosmetics, and fashion segments.
- Regulatory pressure will accelerate the shift toward circular economy models and waste reduction initiatives.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of E-commerce and Retail Channels
The rapid growth of e-commerce and retail is driving demand for secure, protective, and customizable packaging services. Consumers expect damage-free deliveries and premium unboxing experiences, prompting service providers to offer scalable and innovative packaging solutions tailored for online and retail distribution.
Shift Toward Sustainable and Eco-Friendly Solutions
Increasing environmental awareness and regulatory mandates are pushing brands to adopt recyclable, biodegradable, and lightweight packaging materials. Service providers are investing in sustainable alternatives to meet compliance requirements and enhance brand reputation, fueling market growth.
Rising Demand from Food and Beverage Industry
The food and beverage sector accounts for the largest share of packaging service demand, driven by the popularity of packaged snacks, ready-to-eat meals, and beverages. Innovations in resealable, tamper-evident, and sustainable packaging formats are supporting this growth.
Adoption of Digital Printing and Smart Packaging
Digital printing technologies enable greater customization, faster turnaround, and limited-edition packaging, while smart packaging with QR codes and NFC tags enhances traceability and consumer engagement. These trends are creating new value propositions for packaging service providers.
Growth in Subscription and Direct-to-Consumer Models
The rise of subscription boxes and direct-to-consumer brands is increasing demand for visually appealing, durable, and personalized packaging. Service providers are responding with flexible production runs and innovative designs that enhance the unboxing experience and reinforce brand identity.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Packaging Service market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Packaging Service market projected to grow between 2025 and 2032?
Which Packaging Service market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Packaging Service market?
Who are the leading companies in the Packaging Service market?
Which region commanded the largest share of the Packaging Service market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Food & Beverages
- 1.2.2 Consumer Goods
- 1.2.3 Personal Care & Cosmetics
- 1.2.4 Others
- 1.3 By Material
- 1.3.1 Plastic
- 1.3.2 Paper & Paperboard
- 1.3.3 Others
- 1.4 By Product Type
- 1.4.1 Bags & Pouches
- 1.4.2 Boxes & Cartons
- 1.4.3 Trays & Clamshells
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 52,888.00 million → 2032: USD 104,919.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Packaging Service Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Packaging Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Packaging Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Packaging Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Packaging Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Packaging Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Packaging Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Packaging Service Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 52,888.00 million → 2032: USD 104,919.48 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Packaging Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Food & Beverages
- 12.3.6.2 Consumer Goods
- 12.3.6.3 Personal Care & Cosmetics
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Plastic
- 12.4.6.2 Paper & Paperboard
- 12.4.6.3 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Bags & Pouches
- 12.5.6.2 Boxes & Cartons
- 12.5.6.3 Trays & Clamshells
- 12.5.6.4 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Packaging Service End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Packaging Service Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Packaging Service Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Packaging Service Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mondi Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Graphic Packaging International Inc
- 18.4 Crown Holdings, Inc
- 18.5 Sonoco Products Company
- 18.6 International Paper
- 18.7 DS Smith Plc
- 18.8 Amcor Ltd.
- 18.9 AptarGroup Inc
- 18.10 Nippon Paper Industries Co. Ltd.
- 18.11 Anchor Packaging
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

