
Market Overview
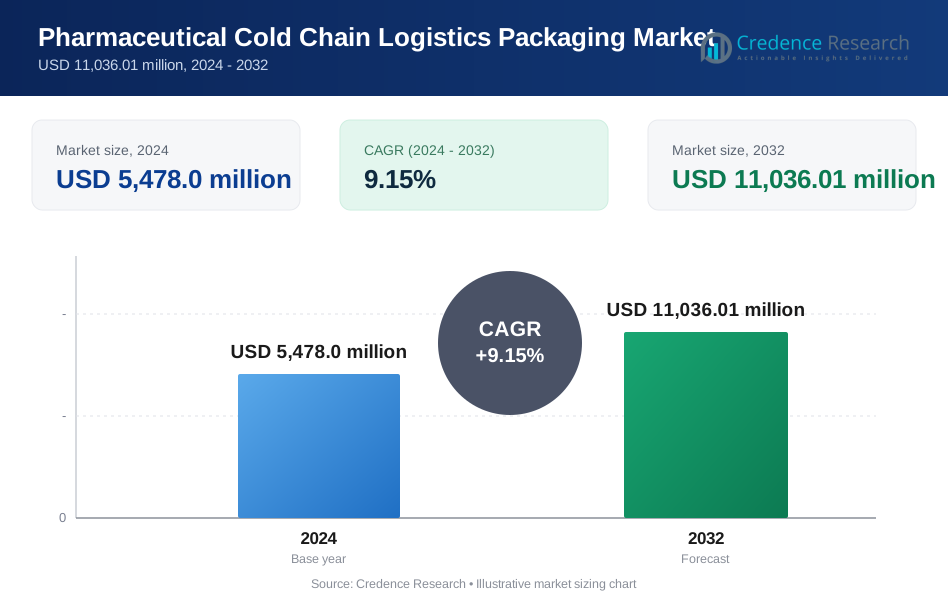
The Pharmaceutical Cold Chain Logistics Packaging Market was valued at USD 5,478.0 million in 2024 and is expected to reach USD 11,036.01 million by 2032, growing at a CAGR of 9.15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pharmaceutical Cold Chain Logistics Packaging Market Size 2024 | USD 5,478.0 Million |
| Pharmaceutical Cold Chain Logistics Packaging Market, CAGR | 9.15% |
| Pharmaceutical Cold Chain Logistics Packaging Market Size 2032 | USD 11,036.01 Million |
The pharmaceutical cold chain logistics packaging market is driven by leading players including Cryoport Systems, LLC, SkyCell AG, Intelsius, Sealed Air, va-Q-tec AG, Peli BioThermal Limited, Envirotainer, Inmark Global Holdings, LLC, CSafe, and Sonoco ThermoSafe. These companies focus on innovative insulated containers, reusable shippers, and smart monitoring technologies to ensure temperature integrity across global supply chains. North America leads the market with 38% share, supported by strong biologics production and advanced cold chain infrastructure. Europe follows with 30% share, driven by strict GDP compliance, while Asia Pacific holds 22% share and is the fastest-growing region due to rising pharmaceutical exports and vaccine distribution needs.
 Market Insights
- The pharmaceutical cold chain logistics packaging market was valued at USD 5,478.0 million in 2024 and is projected to reach USD 11,036.01 million by 2032, growing at a CAGR of 9.15%.
- Growing demand for biologics, vaccines, and cell therapies is driving the adoption of insulated containers and temperature-controlled shippers across the supply chain.
- Key trends include IoT-enabled smart packaging for real-time temperature monitoring and the rising use of reusable, sustainable packaging solutions to meet ESG goals.
- The market is competitive, with players such as Cryoport Systems, LLC, SkyCell AG, Sealed Air, and Envirotainer focusing on innovation, capacity expansion, and partnerships with logistics providers to strengthen their global footprint.
- North America leads with 38% share, followed by Europe at 30% and Asia Pacific at 22%; small boxes dominate the product segment with over 40% share, while biopharmaceutical companies hold more than 50% share by end use.
Market Segmentation Analysis:
By Material
Plastic dominated the pharmaceutical cold chain logistics packaging market in 2024, holding over 45% share due to its durability, lightweight nature, and superior thermal insulation. Plastic materials, such as HDPE and EPS, are widely used in temperature-controlled boxes, pallet shippers, and insulated containers to ensure product stability during transit. Their reusability and cost-effectiveness make them the preferred choice for large-scale pharmaceutical logistics operations. Paper-based solutions are growing as eco-friendly alternatives, while metals and other materials serve niche roles requiring extra strength or extended temperature maintenance for high-value biopharmaceutical shipments.
- For instance, Peli BioThermal manufactures Crēdo Cube™ reusable shippers with HDPE outer shells that are used for global vaccine distribution. Certain Crēdo Cube™ models are validated to maintain temperature control for up to 96 hours, meeting the needs for transporting temperature-sensitive pharmaceuticals.
By Product
Small boxes led the market with over 40% share in 2024, driven by their extensive use in last-mile delivery of vaccines, biologics, and temperature-sensitive drugs. These boxes offer compact design, reliable temperature control, and are ideal for frequent, smaller shipments from distribution hubs to hospitals and pharmacies. Pallets and large-sized pallet containers follow, used for bulk transport in global pharmaceutical supply chains. Their adoption is growing with the rising scale of vaccine distribution and international clinical trial logistics, where efficient space utilization and consistent temperature performance are critical.
- For instance, Envirotainer deployed their temperature-controlled containers, including the RAP e2 model with a payload capacity of 6.38 m³, for multinational vaccine shipments across Europe and Asia.
By End Use
Biopharmaceutical companies accounted for more than 50% share of the market in 2024, as they are the largest users of cold chain packaging for biologics, cell and gene therapies, and specialty drugs. The rising production of temperature-sensitive pharmaceuticals, particularly mRNA-based vaccines and oncology treatments, is driving demand for reliable and validated packaging solutions. Clinical research organizations also represent a significant share, using temperature-controlled packaging to maintain integrity during clinical trial sample transport. Hospitals and other healthcare facilities contribute steadily, focusing on smaller, frequent deliveries requiring secure and tamper-proof packaging.
Key Growth Drivers
Rising Demand for Biologics and Specialty Drugs
The rapid expansion of biologics, vaccines, and cell and gene therapies is significantly driving cold chain packaging demand. These products are highly temperature-sensitive and require precise thermal protection to maintain efficacy during storage and transport. The surge in mRNA vaccine production and personalized medicine further boosts adoption of advanced insulated shippers and temperature-monitoring systems. Pharmaceutical companies are increasing investment in reliable cold chain infrastructure, ensuring regulatory compliance and minimizing product loss, which strengthens the need for validated, high-performance packaging solutions across global distribution networks.
- For instance, Cryoport uses its MVE Vapor Shield shippers to support global cell therapy trials, maintaining cryogenic temperatures or colder with a hold time of up to 26 days. Cryoport's supply chain solutions are designed to ensure safety and reliability for sensitive biomaterials.
Expansion of Global Pharmaceutical Trade
The increasing globalization of pharmaceutical manufacturing and distribution is fueling the need for robust cold chain logistics packaging. Rising exports of temperature-sensitive drugs from Asia Pacific to North America and Europe require standardized, durable packaging to maintain product integrity over long distances. Growth in international clinical trials also contributes to higher shipment volumes, creating demand for scalable solutions. Manufacturers are focusing on reusable and cost-efficient designs to optimize operations and reduce waste, aligning with sustainability goals while maintaining consistent performance in cross-border logistics.
- For instance, The Envirotainer RAP e2 is an active temperature-controlled container used for pharmaceutical products. It has an internal cargo volume of 6.38 m³. The company's fleet size is now over 11,000 pallet-sized units.
Stringent Regulatory Compliance
Strict regulations from authorities like the FDA, EMA, and WHO are pushing pharmaceutical companies to adopt validated cold chain packaging. Compliance with Good Distribution Practices (GDP) and temperature monitoring standards ensures that products remain within specified temperature ranges. This regulatory focus drives innovation in insulated containers, phase-change materials, and data-logging technologies. Companies are increasingly adopting packaging solutions with real-time monitoring capabilities, enabling end-to-end visibility and reducing the risk of spoilage. The pressure to maintain product safety is accelerating adoption of advanced, certified packaging systems.
Key Trends & Opportunities
Adoption of IoT-Enabled Smart Packaging
IoT-enabled packaging with real-time tracking and temperature monitoring is transforming cold chain logistics. These smart solutions allow pharmaceutical companies to monitor temperature excursions, location, and handling conditions remotely. This capability reduces wastage, improves compliance reporting, and strengthens supply chain transparency. As biologics and personalized medicines gain popularity, the demand for such connected packaging solutions is set to rise. This creates opportunities for packaging providers to integrate digital sensors, cloud-based data platforms, and predictive analytics for improved performance and decision-making.
- For instance, SkyCell has equipped its fleet of over 5,000 hybrid containers with Internet of Things (IoT) sensors for real-time tracking during international shipments. The company offers different types of sensors, some of which are capable of data logging every 10 minutes. An external audit confirms that SkyCell's containers have a temperature excursion rate of less than 0.05%.
Shift Toward Sustainable and Reusable Solutions
Growing emphasis on sustainability is encouraging the use of reusable shippers, recyclable materials, and energy-efficient insulation systems. Pharmaceutical companies are adopting closed-loop logistics models to minimize waste and reduce environmental impact. Packaging suppliers are investing in materials that maintain thermal performance while offering reusability for multiple shipment cycles. This trend aligns with corporate ESG targets and cost-saving initiatives, creating opportunities for innovation in lightweight, eco-friendly solutions without compromising product safety or compliance requirements.
- For instance, DHL's Pharmacool Cassette line offers a portfolio of reusable passive insulated containers used for temperature-controlled transport of sensitive pharmaceutical and life sciences products, including biologics.
Key Challenges
High Cost of Advanced Packaging Solutions
The use of validated, insulated containers and IoT-enabled monitoring systems increases overall logistics costs. For small and mid-sized pharmaceutical companies, the investment required for high-performance cold chain packaging can be a significant barrier. Balancing cost efficiency with compliance and performance remains a challenge. Packaging suppliers must innovate to deliver cost-effective solutions while maintaining reliability, especially for high-volume vaccine and biologics distribution.
Infrastructure Limitations in Emerging Markets
Inadequate cold chain infrastructure in developing regions creates a challenge for effective distribution of temperature-sensitive drugs. Limited availability of storage facilities, trained personnel, and reliable transportation systems increases the risk of product spoilage. This gap puts pressure on packaging to provide longer thermal protection and durability under variable conditions. Addressing these challenges requires collaboration between manufacturers, logistics providers, and governments to improve infrastructure and ensure access to life-saving therapies in underserved regions.
Regional Analysis
North America
North America held 38% share of the pharmaceutical cold chain logistics packaging market in 2024, driven by strong demand from biopharmaceutical companies and advanced vaccine distribution networks. The United States leads the region with significant investment in temperature-controlled infrastructure and adoption of IoT-enabled packaging for real-time monitoring. Growth is supported by the increasing production of biologics, mRNA vaccines, and cell therapies that require precise thermal protection. Canada contributes with rising clinical research activities and improved healthcare logistics, further driving demand for validated, reusable shippers and pallet containers to ensure regulatory compliance.
Europe
Europe accounted for 30% share in 2024, supported by a well-established pharmaceutical manufacturing base and strict regulatory standards. The region benefits from strong demand for GDP-compliant packaging solutions for cross-border distribution. Germany, France, and the UK lead adoption due to large-scale biologics production and clinical trial activities. The EU’s focus on reducing carbon footprint drives innovation in reusable and recyclable cold chain packaging. Investment in advanced insulated containers and real-time temperature tracking solutions is rising, ensuring product integrity during long-distance transport across Europe’s diverse climate zones and multiple distribution points.
Asia Pacific
Asia Pacific captured 22% share of the market in 2024 and is the fastest-growing region due to rising pharmaceutical production and export activities. China and India are major contributors, supported by their expanding biologics and vaccine manufacturing capabilities. Japan and South Korea drive adoption of high-quality, validated packaging to support clinical trials and global exports. Growing healthcare infrastructure and investment in cold chain networks are strengthening supply chain reliability. The region’s rising demand for cost-effective yet robust packaging solutions creates opportunities for local and global players to expand capacity and cater to increasing shipment volumes.
Latin America
Latin America held 6% share in 2024, led by Brazil and Mexico, where growing pharmaceutical manufacturing and vaccination programs are driving market demand. Investment in healthcare infrastructure and logistics networks is improving cold chain reliability in the region. Rising imports of temperature-sensitive biologics and clinical trial materials are fueling the need for validated packaging solutions. Manufacturers are introducing cost-efficient small boxes and pallet shippers suitable for long transit times and variable climates. Continued government focus on improving access to specialty medicines is likely to support steady growth in cold chain packaging demand.
Middle East & Africa
The Middle East & Africa region accounted for 4% share of the pharmaceutical cold chain logistics packaging market in 2024, driven by increasing demand for vaccines and specialty medicines. The UAE and Saudi Arabia are leading markets, with significant investment in healthcare logistics and cold storage capacity. South Africa supports growth with expanding clinical trials and imports of temperature-sensitive pharmaceuticals. The region’s hot climate intensifies demand for high-performance insulated containers and extended-duration packaging. Ongoing infrastructure development and partnerships with global logistics providers are improving cold chain efficiency and reducing product losses.
Market Segmentations:
By Material
- Plastic
- Paper
- Metal
- Others
By Product
- Small Boxes
- Pallets
- Large Sized Pallet Containers
- Others
By End Use
- Biopharmaceutical Companies
- Clinical Research Organizations
- Hospitals
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the pharmaceutical cold chain logistics packaging market includes key players such as Cryoport Systems, LLC, SkyCell AG, Intelsius, Sealed Air, va-Q-tec AG, Peli BioThermal Limited, Envirotainer, Inmark Global Holdings, LLC, CSafe, and Sonoco ThermoSafe. These companies focus on developing high-performance insulated containers, phase-change materials, and IoT-enabled packaging to ensure product integrity during global distribution. Strategic initiatives include capacity expansions, partnerships with logistics providers, and investment in reusable and sustainable solutions to align with ESG targets. Market leaders are leveraging technology integration, including real-time temperature monitoring and predictive analytics, to enhance compliance and reduce wastage. The competitive environment is shaped by innovation-driven differentiation, where global players aim to strengthen their presence in emerging markets while maintaining cost efficiency. Collaboration with pharmaceutical manufacturers and regulatory compliance remain central to their strategies, ensuring consistent supply chain performance and reliable delivery of temperature-sensitive drugs.
Key Player Analysis
- Cryoport Systems, LLC
- SkyCell AG
- Intelsius
- Sealed Air
- va-Q-tec AG
- Peli BioThermal Limited
- Envirotainer
- Inmark Global Holdings, LLC
- CSafe
- Sonoco ThermoSafe
Recent Developments
- In July 2025, Cryoport Systems (via its MVE Biological Solutions unit) introduced a new SC vapor shipper series featuring “Vapor Shield Technology” and improved impact absorption. The new shippers deliver extended hold times for shipments at ultra-low temperatures.
- In April 2025, SkyCell AG launched “Net ZERO Reverse,” a service designed to reduce emissions in pharma cold chains by returning empty containers via ocean freight instead of air, thereby cutting CO₂ emissions in the return journey by over 90%.
- In 2025, Cryoport Systems completed divestiture of its specialty courier business (CRYOPDP) to DHL, and concurrently established a strategic partnership with DHL to enhance global life sciences cold chain and healthcare logistics services.
- In November 2023, va-Q-tec AG introduced a new phase-change material (PCM) called -67G that enables transport at −70 °C without using dry ice. The solution is qualified for up to 72 hours under −60 °C conditions.
Report Coverage
The research report offers an in-depth analysis based on Material, Product, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for temperature-controlled packaging will grow with rising production of biologics and vaccines.
- Adoption of IoT-enabled smart packaging will increase to ensure real-time shipment monitoring.
- Reusable and sustainable insulated shippers will gain traction to meet ESG and cost goals.
- Growth of global clinical trials will boost demand for validated cold chain packaging solutions.
- Asia Pacific will see the fastest growth driven by expanding pharmaceutical manufacturing and exports.
- Partnerships between packaging providers and logistics companies will strengthen supply chain reliability.
- Investment in phase-change materials will improve thermal performance for long-distance transport.
- Automation in packaging processes will enhance efficiency and reduce operational costs.
- Regulatory compliance will drive innovation in temperature monitoring and data logging technologies.
- Expansion into emerging markets will create opportunities for cost-efficient and durable packaging solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Pharmaceutical Cold Chain Logistics Packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pharmaceutical Cold Chain Logistics Packaging market projected to grow between 2025 and 2032?
Which Pharmaceutical Cold Chain Logistics Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Pharmaceutical Cold Chain Logistics Packaging market?
Who are the leading companies in the Pharmaceutical Cold Chain Logistics Packaging market?
Which region commanded the largest share of the Pharmaceutical Cold Chain Logistics Packaging market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pharmaceutical Cold Chain Logistics Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pharmaceutical Cold Chain Logistics Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,478.0 million → 2032: USD 11,036.01 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pharmaceutical Cold Chain Logistics Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pharmaceutical Cold Chain Logistics Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pharmaceutical Cold Chain Logistics Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pharmaceutical Cold Chain Logistics Packaging Market Drivers
- 3.3 Pharmaceutical Cold Chain Logistics Packaging Market Restraints & Challenges
- 3.4 Pharmaceutical Cold Chain Logistics Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pharmaceutical Cold Chain Logistics Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pharmaceutical Cold Chain Logistics Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pharmaceutical Cold Chain Logistics Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pharmaceutical Cold Chain Logistics Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pharmaceutical Cold Chain Logistics Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pharmaceutical Cold Chain Logistics Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pharmaceutical Cold Chain Logistics Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pharmaceutical Cold Chain Logistics Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pharmaceutical Cold Chain Logistics Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pharmaceutical Cold Chain Logistics Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pharmaceutical Cold Chain Logistics Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pharmaceutical Cold Chain Logistics Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pharmaceutical Cold Chain Logistics Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pharmaceutical Cold Chain Logistics Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pharmaceutical Cold Chain Logistics Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pharmaceutical Cold Chain Logistics Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pharmaceutical Cold Chain Logistics Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pharmaceutical Cold Chain Logistics Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pharmaceutical Cold Chain Logistics Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
