
Market Overview
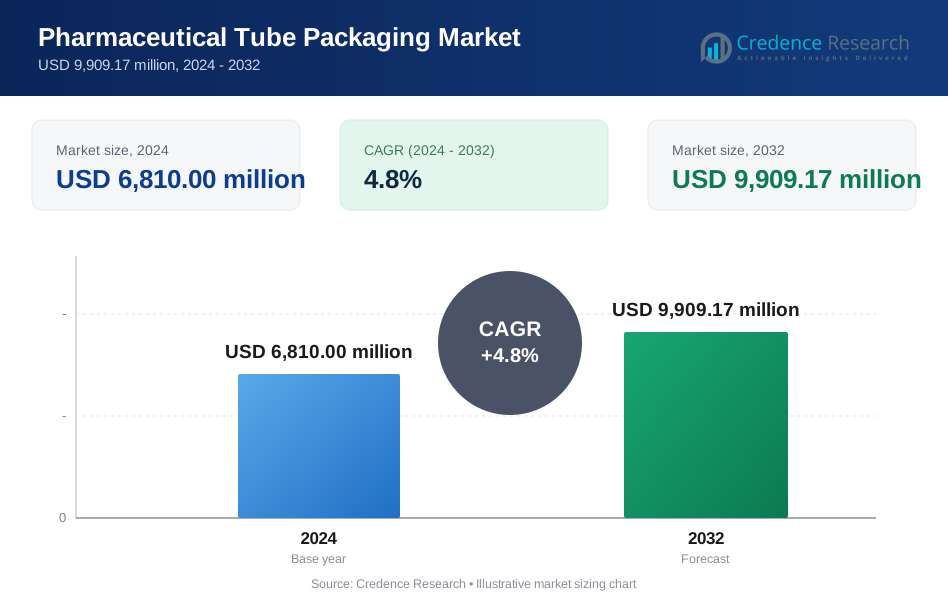
The pharmaceutical tube packaging market was valued at USD 6,810.00 million in 2024 and is projected to reach USD 9,909.17 million by 2032, growing at a CAGR of 4.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pharmaceutical Tube Packaging Market Size 2024 | USD 6,810.00 Million |
| Pharmaceutical Tube Packaging Market, CAGR | 4.8% |
| Pharmaceutical Tube Packaging Market Size 2032 | USD 9,909.17 Million |
The pharmaceutical tube packaging market is driven by key players such as Amcor plc, Hoffmann Neopac AG, Essel Propack Ltd (Huhtamaki Company), Albéa Group, Montebello Packaging, CCL Industries Inc., Tuboplast (Berry Global Inc.), ALLTUB Group, Pirlo Group, and Linhardt GmbH & Co. KG. These companies focus on producing high-barrier laminated, aluminum, and plastic tubes with tamper-evident and patient-friendly designs. North America leads the market with 36% share, supported by strong pharmaceutical manufacturing and OTC product demand. Europe holds 30% share, driven by sustainable packaging initiatives, while Asia-Pacific accounts for 24%, emerging as the fastest-growing region due to expanding generics production and rising healthcare investments.
 Market Insights
- The pharmaceutical tube packaging market was valued at USD 6,810.00 million in 2024 and is projected to reach USD 9,909.17 million by 2032, growing at a CAGR of 4.8% during the forecast period.
- Rising demand for topical medications, oral care products, and OTC drugs is driving adoption of laminated and plastic tubes with high barrier protection and user-friendly dispensing features.
- Key trends include the shift toward recyclable and bio-based tubes, increasing use of digital printing for regulatory compliance, and innovation in child-resistant and tamper-evident closures.
- The market is competitive, with players such as Amcor plc, Hoffmann Neopac AG, Albéa Group, and Essel Propack Ltd focusing on sustainable materials, lightweight designs, and production capacity expansion.
- North America leads with 36% share, Europe holds 30%, and Asia-Pacific accounts for 24%, while laminated tubes dominate the product segment with more than 50% share due to superior barrier properties.
Market Segmentation Analysis:
By Product Type
Laminated tubes dominated the pharmaceutical tube packaging market in 2024, accounting for over 50% share. Their popularity stems from excellent barrier properties against light, moisture, and oxygen, which ensure drug stability and shelf life. They are widely used for topical medications such as creams and ointments, offering flexibility and printability for branding. Aluminum tubes hold a moderate share, favored for products needing complete protection from air exposure. Plastic tubes continue to grow steadily due to cost efficiency and recyclability, making them suitable for mass-market formulations and over-the-counter pharmaceutical products.
- For instance, Hoffmann Neopac produces a variety of Polyfoil® plastic barrier tubes, including a lightweight version with a wall thickness reduced to 0.35 mm for sustainability, which is part of their total annual capacity exceeding 1.3 billion tubes.
By Material
Polyethylene (PE) led the market in 2024 with more than 40% share, driven by its durability, chemical resistance, and compatibility with pharmaceutical formulations. PE tubes are widely used for creams and gels, offering flexibility and lightweight packaging solutions. Polypropylene (PP) follows, benefiting from its high stiffness and recyclability, making it suitable for sterile applications. Aluminum remains critical for moisture-sensitive and oxygen-sensitive medicines, while eco-friendly materials, including bioplastics, are gaining traction due to rising sustainability goals. Their adoption is expected to grow as pharmaceutical firms invest in greener packaging options.
- For instance, Albéa announced that its North American division was expanding its range of recyclable, mono-material HDPE caps for oral care and pharma markets. This included the Fez flip-top cap, designed for the pharma market.
By Cap Type
Flip-top caps dominated the cap type segment in 2024, capturing over 45% share due to their convenience, one-hand usability, and tamper-evident sealing. They are preferred for topical and oral care products as they provide controlled dispensing and reduce product wastage. Stand-up caps are witnessing rising demand, particularly for larger tube formats, enhancing shelf appeal. Nozzle caps are commonly used for precise application in gels and ointments, while screw caps remain a cost-effective option for standard formulations. Increasing focus on patient-friendly packaging designs is supporting innovation across all cap types.
Key Growth Drivers
Growing Demand for Topical Medications
The rising prevalence of dermatological disorders and chronic conditions is driving demand for topical medications, boosting the need for tube packaging. Laminated and plastic tubes offer excellent protection against contamination and allow convenient, precise dosing. Their lightweight and portable nature make them the preferred choice for ointments, gels, and creams used for long-term treatments. Pharmaceutical companies are increasingly adopting innovative tube formats with tamper-evident seals and easy-open features to improve patient compliance, further strengthening market growth for tube-based packaging solutions globally.
- For instance, ALLTUB Group currently produces over 1.4 billion units annually, including pharmaceutical tubes. The company's high-barrier aluminum tubes protect contents from air and light, maintaining product potency.
Shift Toward Sustainable Packaging
Growing environmental concerns and regulations on single-use plastics are pushing pharmaceutical manufacturers to adopt recyclable and eco-friendly tube packaging. Polyethylene and polypropylene tubes with high recyclability rates are gaining market share, while bioplastic tubes are being tested for large-scale production. Brand owners are emphasizing reduced carbon footprints and lightweight designs to meet corporate sustainability targets. This shift is encouraging suppliers to invest in research and development to create greener alternatives without compromising barrier properties or product safety, driving long-term adoption across pharmaceutical applications.
- For instance, Montebello Packaging manufactures tubes for pharmaceuticals and other industries, and offers sustainable packaging options, like infinitely recyclable aluminum and eco-friendly laminates.
Rising Self-Medication and OTC Product Demand
Increasing preference for self-care and over-the-counter (OTC) medications is boosting demand for convenient, easy-to-use packaging formats like tubes. Consumers favor tubes for their portability, resealability, and hygienic dispensing, making them ideal for products such as oral gels, pain relief ointments, and topical antibiotics. Pharmacies and retailers are expanding OTC product offerings, further increasing the need for attractive and functional tube packaging. This trend is particularly strong in emerging markets where access to healthcare services may be limited, encouraging pharmaceutical companies to optimize packaging for consumer-friendly use.
Key Trends & Opportunities
Adoption of Digital Printing and Customization
Digital printing technology is enabling cost-efficient, high-quality graphics and personalization on pharmaceutical tubes. This helps brand owners improve product differentiation and meet regulatory requirements for labeling and batch traceability. Small-batch and rapid production capabilities support contract manufacturing organizations (CMOs) handling multiple SKUs for clinical and commercial products. This trend creates opportunities for packaging converters to invest in advanced printing equipment and expand offerings for niche and specialty drug manufacturers seeking flexible, compliant solutions.
- For instance, CCL Industries has invested over $500 million in pharmaceutical printing plants globally and uses digital printing capabilities, including those in its CCL Healthcare division, to provide batch-level serialization and 2D codes for full product traceability. The company operates in many markets worldwide and provides these solutions to serve the healthcare sector, which requires high levels of security and traceability.
Growth of Child-Resistant and Tamper-Evident Designs
Increasing focus on patient safety is driving demand for child-resistant closures and tamper-evident tube formats. Regulatory compliance for hazardous or high-potency drugs requires packaging that minimizes accidental ingestion risks. Manufacturers are integrating smart closures and improved sealing mechanisms to prevent misuse while ensuring convenience for adult users. This opens opportunities for innovation in cap design and advanced materials that balance safety, ease of use, and cost-effectiveness across a range of pharmaceutical applications.
- For instance, Hoffmann Neopac AG produces Polyfoil® tubes with child-resistant caps and tamper-evident foil seals. The company's tubes are certified according to child-safety standards, including ISO 8317 and USA Norm 16 CFR § 1700.20.
Key Challenges
Price Pressure and Cost Optimization
Rising raw material costs for polyethylene, polypropylene, and aluminum are creating margin pressure for tube packaging manufacturers. Pharmaceutical companies expect cost-efficient solutions without compromising quality or compliance. This challenge forces suppliers to focus on lightweighting, production efficiency, and recycling content while maintaining durability and performance. Balancing sustainability initiatives with affordability remains a critical issue, especially for high-volume generic drug producers operating in competitive, price-sensitive markets.
Stringent Regulatory and Quality Compliance
Pharmaceutical tube packaging must meet strict regulatory standards for barrier protection, leachability, and labeling accuracy. Compliance with FDA, EMA, and ISO guidelines requires extensive testing and documentation, which increases development costs and time to market. Any deviation can result in product recalls or regulatory penalties. Ensuring consistent quality across global production sites and meeting serialization and traceability requirements add further complexity for manufacturers supplying multiple regions with varying compliance needs.
Regional Analysis
North America
North America held 36% share of the pharmaceutical tube packaging market in 2024, driven by strong pharmaceutical production and a robust network of contract manufacturing organizations. The region benefits from rising demand for topical medications, OTC products, and dermatology treatments. The U.S. leads the market with high adoption of laminated and plastic tubes for prescription and self-care drugs. Strict FDA regulations and focus on tamper-evident, child-resistant packaging further boost demand for advanced tube formats. Growth is supported by innovation in sustainable materials and digital printing to meet regulatory compliance and patient-friendly packaging requirements.
Europe
Europe accounted for 30% of the pharmaceutical tube packaging market in 2024, supported by a well-established pharmaceutical industry and strict EMA guidelines for packaging compliance. Germany, Switzerland, and the U.K. lead demand, particularly for aluminum tubes that offer superior barrier properties for sensitive formulations. The region’s emphasis on sustainability is driving adoption of recyclable and lightweight plastic tubes. Growth is fueled by the increasing use of nutraceuticals, topical treatments, and contract manufacturing for global drug supply. Investments in eco-friendly solutions and child-resistant cap designs further enhance Europe’s position as a leader in innovative tube packaging technologies.
Asia-Pacific
Asia-Pacific captured 24% share in 2024 and is the fastest-growing region in the pharmaceutical tube packaging market. Growth is driven by expanding generic drug production in India and China, increasing healthcare spending, and rising self-medication trends. Manufacturers in the region are rapidly adopting laminated and plastic tubes for cost-effective, high-volume production. Demand is boosted by growing awareness of personal care and dermatology treatments, as well as expanding distribution networks in rural areas. Government initiatives promoting local pharmaceutical manufacturing and sustainability efforts are encouraging the adoption of recyclable materials and modern packaging formats to meet rising demand.
Latin America
Latin America held 6% of the pharmaceutical tube packaging market in 2024, with Brazil and Mexico being the largest contributors. Rising demand for OTC medications, pain relief ointments, and oral care products is fueling growth. The region is witnessing increased investment from multinational pharmaceutical companies and contract manufacturers, driving higher adoption of laminated and plastic tubes. GDP compliance initiatives and modernization of local packaging facilities are improving product quality. Growth opportunities lie in developing patient-friendly packaging with tamper-evident and child-resistant features to meet global export standards and enhance consumer safety in the region.
Middle East & Africa
Middle East & Africa represented 4% share of the pharmaceutical tube packaging market in 2024, supported by rising imports of pharmaceutical products and government-led healthcare expansion projects. GCC countries lead demand due to higher spending on specialty drugs and personal care products. Investments in local pharmaceutical manufacturing and packaging facilities are creating opportunities for laminated tube suppliers and eco-friendly material providers. Africa’s growing population and public health campaigns are increasing the use of affordable topical treatments, boosting demand for cost-effective tube packaging solutions suitable for diverse climatic conditions and long-distance distribution.
Market Segmentations:
By Product Type
- Laminated Tubes
- Aluminum Tubes
- Plastic Tubes
By Material
- Polyethylene (PE)
- Polypropylene (PP)
- Aluminum
- Others (Eco-friendly and Bioplastics)
By Cap Type
- Flip-Top Caps
- Stand-Up Caps
- Nozzle Caps
- Screw Caps
By Application
- Topical Medications (Ointments, Creams, Gels)
- Oral Care (Pharmaceutical Toothpaste, Oral Gels)
- Nutraceuticals
- Other Pharmaceutical Formulations
By End-User
- Pharmaceutical Companies
- Contract Manufacturing Organizations (CMOs)
- Healthcare Institutions & Clinics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the pharmaceutical tube packaging market is shaped by leading players such as Amcor plc, Hoffmann Neopac AG, Essel Propack Ltd (Huhtamaki Company), Albéa Group, Montebello Packaging, CCL Industries Inc., Tuboplast (Berry Global Inc.), ALLTUB Group, Pirlo Group, and Linhardt GmbH & Co. KG. These companies focus on developing high-barrier laminated and plastic tubes that protect product integrity while meeting regulatory requirements. Strategic priorities include expanding production capacity, adopting recyclable and bio-based materials, and integrating digital printing technologies for compliance labeling. Players are also investing in tamper-evident and child-resistant closures to enhance patient safety and meet global standards. Partnerships with pharmaceutical manufacturers and contract manufacturing organizations (CMOs) are common to ensure timely supply and cost efficiency. Continuous innovation in lightweight materials, sustainable packaging formats, and customization capabilities positions these companies to compete effectively in both developed and emerging markets.
Key Player Analysis
- Amcor plc
- Hoffmann Neopac AG
- Essel Propack Ltd (Huhtamaki Company)
- Albéa Group
- Montebello Packaging
- CCL Industries Inc.
- Tuboplast (Berry Global Inc.)
- ALLTUB Group
- Pirlo Group
- Linhardt GmbH & Co. KG
Recent Developments
- In June 2025, Amcor plc achieved a 16.67% reduction in wall thickness for its 50 mm diameter flexible tubes in 100 ml and 150 ml sizes (used by Bulldog). The change is expected to save about 8.5 metric tonnes of plastic annually, while maintaining leak-test and printing quality,
- In June 2025, Amcor plc also increased the amount of post-consumer recycled (PCR) plastic to over 62% in the complete tube for the same Bulldog flexible tubes.
- In May 2025, Hoffmann Neopac AG won two Tube of the Year Awards from the US Tube Council for its Voltaren Polyfoil® tube. The tube has an aluminium-barrier laminate with a wall thickness of 0.35 mm.
- In June 2024, Essel Propack Ltd (EPL) emphasized the pharmaceutical sector as a thrust area and is expanding the use of its laminated tubes (strong barrier and high printability) for pharma gels, indicating product development toward healthcare applications.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Cap Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for laminated and plastic tubes will rise with increasing topical and OTC drug usage.
- Adoption of recyclable and bio-based tubes will grow to meet sustainability and regulatory goals.
- Digital printing will see higher use for labeling, serialization, and brand differentiation.
- Child-resistant and tamper-evident caps will become standard for sensitive drug packaging.
- Contract manufacturing organizations will expand tube production capacity to meet pharma outsourcing needs.
- Lightweight and eco-friendly materials will be prioritized to lower carbon footprint in supply chains.
- Growth of self-medication and e-pharmacies will drive demand for portable and convenient tube formats.
- Emerging markets will contribute significantly due to expanding healthcare access and generics production.
- Manufacturers will invest in automation and smart production lines for efficiency and consistency.
- Personalized medicine and niche formulations will increase demand for small-batch and specialty tube packaging.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Pharmaceutical Tube Packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pharmaceutical Tube Packaging market projected to grow between 2025 and 2032?
Which Pharmaceutical Tube Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Pharmaceutical Tube Packaging market?
Who are the leading companies in the Pharmaceutical Tube Packaging market?
Which region commanded the largest share of the Pharmaceutical Tube Packaging market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pharmaceutical Tube Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pharmaceutical Tube Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,810.00 million → 2032: USD 9,909.17 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pharmaceutical Tube Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pharmaceutical Tube Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pharmaceutical Tube Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pharmaceutical Tube Packaging Market Drivers
- 3.3 Pharmaceutical Tube Packaging Market Restraints & Challenges
- 3.4 Pharmaceutical Tube Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pharmaceutical Tube Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pharmaceutical Tube Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pharmaceutical Tube Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pharmaceutical Tube Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pharmaceutical Tube Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pharmaceutical Tube Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pharmaceutical Tube Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pharmaceutical Tube Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pharmaceutical Tube Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pharmaceutical Tube Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pharmaceutical Tube Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pharmaceutical Tube Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pharmaceutical Tube Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pharmaceutical Tube Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pharmaceutical Tube Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pharmaceutical Tube Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pharmaceutical Tube Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pharmaceutical Tube Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pharmaceutical Tube Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
