
Market Overview
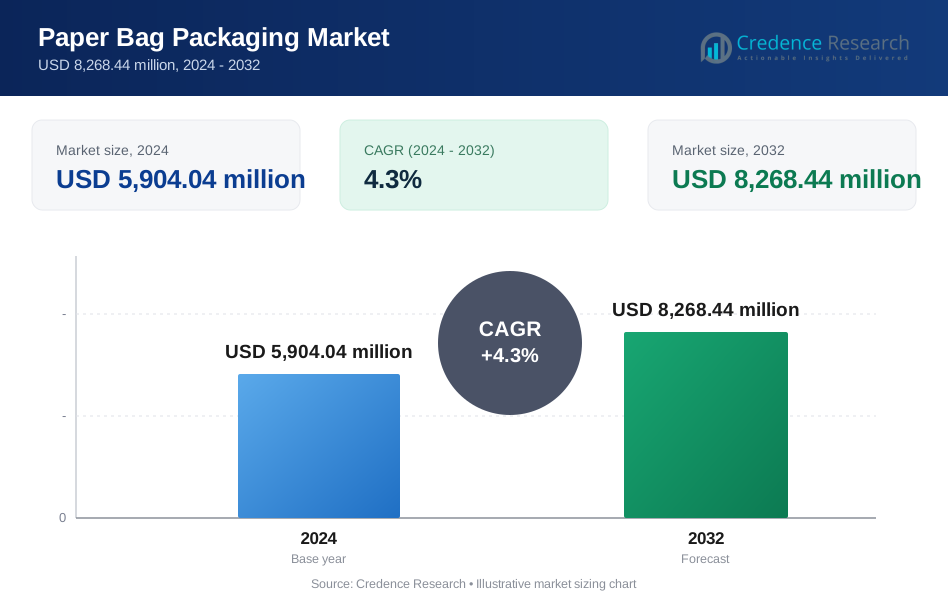
The paper bag packaging market was valued at USD 5,904.04 million in 2024 and is projected to reach USD 8,268.44 million by 2032, growing at a CAGR of 4.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Paper Bag Packaging Market Size 2024 | USD 5,904.04 Million |
| Paper Bag Packaging Market, CAGR | 4.3% |
| Paper Bag Packaging Market Size 2032 | USD 8,268.44 Million |
The paper bag packaging market is led by key players including Novolex Holdings Inc., Mondi, Oji Holdings Corporation, ProAmpac, United Bags, Huhtamaki Oyj, Welton Bibby & Baron Ltd, Smurfit Kappa, International Paper Company, and Rengo Co. Ltd. These companies focus on sustainable, recyclable, and high-strength kraft paper solutions to meet rising demand from retail, food service, and e-commerce sectors. North America leads the market with 33% share, driven by plastic bag bans and strong adoption in grocery and retail. Europe accounts for 30% share, supported by strict EU packaging regulations, while Asia Pacific holds 25% share and remains the fastest-growing region due to rapid industrialization, retail expansion, and government initiatives promoting eco-friendly packaging.
 Market Insights
- The paper bag packaging market was valued at USD 5,904.04 million in 2024 and is projected to reach USD 8,268.44 million by 2032, growing at a CAGR of 4.3%.
- Rising bans on single-use plastics and increasing demand for sustainable packaging solutions are driving growth, with brown kraft bags leading the material segment with over 60% share.
- Trends include adoption of customized printed bags for branding, development of high-strength multiwall sacks, and investment in recyclable coatings to improve moisture resistance.
- The market is competitive, with players such as Novolex Holdings Inc., Mondi, Smurfit Kappa, and International Paper Company focusing on sustainable innovation, capacity expansion, and strategic acquisitions to strengthen global presence.
- North America leads with 33% share, Europe follows with 30%, and Asia Pacific holds 25%; sewn open mouth bags dominate with more than 35% share, while food and beverages account for over 40% share of end-use demand.
Market Segmentation Analysis:
By Material
Brown kraft dominated the paper bag packaging market in 2024, holding over 60% share due to its strength, durability, and cost-effectiveness. Brown kraft bags are widely used in food service, retail, and grocery packaging because they offer excellent load-bearing capacity and are easily recyclable. Their natural appearance also supports sustainability goals, making them a preferred choice among eco-conscious brands. White kraft bags hold the remaining share, favored in premium applications such as branded retail and luxury packaging, where high printability and aesthetic appeal are key drivers.
- For instance, As of 2024, Mondi publicly reported a 3% increase in its paper bags sales volume. The company also announced investments, including a new kraft paper machine at its Štětí mill in the Czech Republic and acquiring a Canadian pulp mill, to enhance its sustainable packaging capacity. These actions reflect its ongoing focus on recyclable kraft solutions for retailers and other customers.
By Type
Sewn open mouth bags led the market with more than 35% share in 2024, driven by their heavy-duty construction and ability to carry bulk materials like grains, flour, and industrial powders. Their secure stitching makes them ideal for high-weight applications, ensuring product safety during storage and transport. Pinch bottom open mouth bags follow closely, preferred for products needing airtight closure. Pasted valve bags and other types cater to niche applications in chemicals, construction, and specialty segments requiring precision filling and high performance.
- For instance, An industrial FIBC bulk bag designed for bulk goods transport may have a breaking strength of over 10,000 N (1020 kg-force). With a standard 5:1 safety factor, its Safe Working Load (SWL) would be 200 kg (2000 N), which allows for the secure transport of bulk loads weighing up to 200 kg.
By End Use
Food and beverages accounted for over 40% share of the market in 2024, making it the dominant end-use segment. Growing demand for sustainable and recyclable packaging in quick-service restaurants, bakeries, and grocery stores is fueling adoption of paper bags. E-commerce represents a fast-growing segment, with retailers replacing plastic mailers with durable kraft paper bags for eco-friendly deliveries. Chemicals, agriculture, and other industrial uses continue to demand heavy-duty paper sacks to ensure safe handling and compliance with regulatory standards for bulk and powdered products.
Key Growth Drivers
Rising Demand for Sustainable Packaging
The global push to reduce plastic waste is significantly boosting demand for paper bag packaging. Governments are enforcing bans on single-use plastics, compelling retailers and food service providers to switch to eco-friendly alternatives. Brown and white kraft bags offer recyclability, biodegradability, and a lower environmental impact, making them highly preferred. Consumer awareness of sustainability and willingness to pay for greener products further fuel adoption. This transition is accelerating growth across sectors, particularly in retail, grocery, and food delivery services, where paper bags are replacing conventional plastic options.
- For instance, a paper bag manufacturer reported a production capacity of 10,000 to 20,000 paper bags per hour using automatic machinery calibrated for kraft paper between 70 and 120 GSM, operating at a high efficiency level and with quality control measures in place to keep defect rates low.
Expansion of E-commerce and Retail Sector
The rapid growth of e-commerce and organized retail is driving demand for durable and branded paper bags. E-commerce platforms and fashion retailers are replacing plastic mailers with strong kraft paper bags to improve sustainability credentials. These bags offer good printability, enhancing brand visibility and supporting premium unboxing experiences. Retailers are also adopting reinforced paper bags for heavier items to ensure safe delivery. This trend is particularly strong in Asia Pacific, where rising online shopping penetration is boosting large-scale adoption of cost-effective and recyclable paper packaging solutions.
- For instance, KETE's fully automated paper bag-making machines can produce up to 150 bags per minute and can be equipped with optional inline flexographic printing, enabling brands to achieve consistent print quality and size customization. These machines are suitable for a range of production environments, including those serving e-commerce distribution centers.
Growth in Food and Beverage Industry
Increasing demand for takeout meals, bakery products, and quick-service restaurant packaging is supporting market expansion. Paper bags are widely used for packaging bakery items, snacks, and beverages, offering grease resistance and product safety. The shift toward hygienic, disposable, and eco-friendly solutions post-pandemic further supports growth. Food chains are emphasizing branded paper bags to enhance customer experience and reinforce sustainability commitments. Rising consumption of packaged food in urban areas is creating consistent demand for high-strength and printed paper bags suitable for high-volume operations and fast-moving consumer goods.
Key Trends & Opportunities
Adoption of Customizable and Printed Paper Bags
Brands are leveraging high-quality printing on paper bags to enhance visibility and marketing impact. Customization allows businesses to promote logos, sustainability messages, and seasonal campaigns effectively. Advanced printing technologies are enabling short production runs and quick turnaround times for personalized packaging solutions. This trend presents opportunities for manufacturers to offer value-added services, catering to retail, fashion, and premium food sectors seeking differentiation through aesthetically appealing, branded paper bags.
- For instance, the Canon imagePRESS V900 digital printing system can print up to 90 pages per minute with substrate adaptability from 52 to 350 GSM. Its advanced features, including the Fiery print server, enable rapid production of high-color-accuracy short runs with complex variable data for personalized branding.
Shift Toward High-Strength Multiwall Bags
Industries such as chemicals, agriculture, and construction are increasing demand for multiwall paper bags that offer superior durability and moisture resistance. These bags support bulk packaging of powders, seeds, and fertilizers, replacing plastic sacks. Manufacturers are investing in improved adhesives and barrier coatings to meet performance requirements while maintaining recyclability. This creates opportunities for suppliers to expand offerings in industrial applications, where safety, compliance, and eco-friendliness are critical.
- For instance, Mondi offers a range of multiwall bags, some with multi-layer construction, including specific products that provide strong moisture barriers for humidity-sensitive products. These bags can achieve high-performance barrier properties suitable for products like fertilizers and chemicals and are offered in specifications that can handle bulk loads of up to 50 kg.
Key Challenges
Fluctuating Raw Material Prices
Price volatility in wood pulp and kraft paper poses challenges for manufacturers, impacting profit margins. Rising input costs can lead to higher product prices, affecting competitiveness against plastic alternatives. To mitigate this, producers must adopt efficient sourcing strategies and invest in process optimization to reduce waste and improve cost control.
Durability and Moisture Resistance Issues
Paper bags, though eco-friendly, can be less durable and more prone to tearing or moisture damage compared to plastic. This limits their application for heavy or wet products. Manufacturers are required to innovate by developing coated, laminated, or reinforced paper solutions that maintain recyclability while improving strength and water resistance, ensuring broader adoption across industries.
Regional Analysis
North America
North America held 33% share of the paper bag packaging market in 2024, driven by strong demand from retail, grocery, and food service sectors. The United States leads the region due to widespread adoption of paper bags following state-level bans on single-use plastics. Growth is also supported by rising e-commerce activity and preference for branded, eco-friendly packaging. Canada contributes with its focus on sustainability and regulatory initiatives encouraging recyclable and compostable packaging. Manufacturers are investing in high-strength kraft paper production and advanced printing solutions to cater to the growing demand for customized, durable paper bags.
Europe
Europe accounted for 30% share in 2024, supported by strict environmental regulations such as the EU Single-Use Plastics Directive. Countries including Germany, France, and the UK are leading adopters of recyclable and biodegradable paper bags, replacing plastic alternatives in retail and food service industries. The region’s focus on circular economy practices is encouraging use of recycled kraft paper and water-based inks. Growth is also driven by premiumization trends in fashion and luxury packaging. Manufacturers are innovating with coated and laminated paper bags that offer enhanced strength and moisture resistance while maintaining recyclability standards.
Asia Pacific
Asia Pacific captured 25% share of the market in 2024 and is the fastest-growing region due to rapid urbanization and rising disposable incomes. China and India are key contributors, driven by increasing retail expansion and government efforts to reduce plastic waste. Demand is particularly strong in food delivery and e-commerce, where lightweight, recyclable bags are preferred. Japan and South Korea support growth with their focus on sustainable solutions and premium printed packaging for retail and gifting purposes. Investments in paper mill capacity and adoption of advanced manufacturing technologies are boosting local supply and reducing import dependency.
Latin America
Latin America held 7% share in 2024, led by Brazil and Mexico where regulations against plastic bags are driving adoption of kraft paper alternatives. Growing retail chains, supermarkets, and quick-service restaurants are fueling demand for durable and cost-effective paper bags. E-commerce platforms are also adopting paper-based mailers and sacks to align with sustainability goals. Manufacturers are expanding capacity to meet regional demand and reduce import reliance. Rising awareness among consumers about environmental benefits of paper packaging is further supporting market growth, creating opportunities for local players to innovate with affordable, recyclable solutions.
Middle East & Africa
The Middle East & Africa region accounted for 5% share of the paper bag packaging market in 2024, supported by growing retail, hospitality, and food service industries. The UAE and Saudi Arabia are leading markets, implementing restrictions on plastic bags and encouraging the switch to paper-based alternatives. South Africa contributes with rising adoption in supermarkets and convenience stores. Demand is also supported by luxury retail and tourism sectors seeking premium, branded paper bags. Regional manufacturers are focusing on cost-efficient production and moisture-resistant coatings to meet performance requirements in hot and humid climates.
Market Segmentations:
By Material
- Brown Kraft
- White Kraft
By Type
- Sewn Open Mouth
- Pinch Bottom Open Mouth
- Pasted Valve
- Others
By End Use
- Food & Beverages
- E-commerce
- Chemicals
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the paper bag packaging market features major players such as Novolex Holdings Inc., Mondi, Oji Holdings Corporation, ProAmpac, United Bags, Huhtamaki Oyj, Welton Bibby & Baron Ltd, Smurfit Kappa, International Paper Company, and Rengo Co. Ltd. These companies focus on producing high-strength kraft paper bags, laminated multiwall sacks, and custom-printed solutions to cater to diverse end-use industries including retail, food and beverages, and e-commerce. Sustainability is a key competitive differentiator, with investments in recyclable and compostable materials aligning with global regulations on plastic reduction. Players are also leveraging advanced printing and converting technologies to deliver premium, branded packaging that enhances shelf visibility. Strategic initiatives such as mergers, acquisitions, and capacity expansions are helping companies expand market reach, particularly in high-growth regions like Asia Pacific and Latin America. The market remains competitive, with global leaders balancing innovation, cost efficiency, and regulatory compliance to gain a larger share.
Key Player Analysis
- Novolex Holdings Inc.
- Mondi
- Oji Holdings Corporation
- ProAmpac
- United Bags
- Huhtamaki Oyj
- Welton Bibby & Baron Ltd
- Smurfit Kappa
- International Paper Company
- Rengo Co. Ltd.
Recent Developments
- In July 2025, International Paper divested five European corrugated-box plants (including those making box goods) to satisfy regulatory requirements of its DS Smith acquisition.
- In January 2025, International Paper completed its merger with DS Smith, forming a larger entity in paper & packaging.
- In October 2024, Novolex Holdings Inc. launched Power Prep™ bags and rolls for grab-and-go hot sandwiches and similar food items.
- In November 2023, Smurfit Kappa introduced a recyclable polyethylene film to replace nylon in Bag-in-Box products.
Report Coverage
The research report offers an in-depth analysis based on Material, Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for paper bags will grow as more countries enforce plastic bag bans worldwide.
- Brown kraft bags will continue to dominate due to strength, cost-efficiency, and recyclability.
- Customized and printed bags will gain traction as brands focus on marketing and visibility.
- Growth of e-commerce will boost demand for durable, branded, and eco-friendly paper mailers.
- Multiwall and high-strength paper bags will see rising adoption in industrial applications.
- Asia Pacific will remain the fastest-growing region, supported by retail and food delivery expansion.
- Investments in recyclable coatings and moisture-resistant finishes will improve performance of paper bags.
- Manufacturers will expand production capacity to meet growing demand from retail and food service sectors.
- Strategic partnerships and acquisitions will enhance global supply networks and reach.
- Sustainability commitments will drive innovation in biodegradable and compostable paper packaging solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Plastic Bag Bans and Regulatory Push
Government bans and restrictions on single-use plastics in major markets are compelling retailers and food service providers to switch to paper bag packaging, directly boosting demand for sustainable alternatives.
Growth of E-commerce and Retail
The rapid expansion of e-commerce and organized retail, especially in Asia Pacific, is driving the need for durable, branded, and recyclable paper bags that can replace plastic mailers and enhance the unboxing experience.
Sustainability and Consumer Preferences
Increasing consumer awareness and preference for eco-friendly, recyclable, and biodegradable packaging are encouraging brands to adopt paper bags, particularly brown kraft, to align with sustainability commitments and market expectations.
Expansion in Food & Beverage Sector
Rising demand for takeout, bakery, and quick-service restaurant packaging is fueling the adoption of paper bags, which offer grease resistance, hygiene, and branding opportunities for food and beverage businesses.
Innovation in High-Strength and Customizable Solutions
Advancements in multiwall construction, moisture-resistant coatings, and high-quality printing are enabling paper bags to serve a wider range of applications, from industrial bulk packaging to premium retail, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Paper Bag Packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Paper Bag Packaging market projected to grow between 2025 and 2032?
Which Paper Bag Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Paper Bag Packaging market?
Who are the leading companies in the Paper Bag Packaging market?
Which region commanded the largest share of the Paper Bag Packaging market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sewn Open Mouth
- 1.2.2 Pinch Bottom Open Mouth
- 1.2.3 Pasted Valve
- 1.2.4 Others
- 1.3 By End Use
- 1.3.1 Food & Beverages
- 1.3.2 E-commerce
- 1.3.3 Chemicals
- 1.3.4 Others
- 1.4 By Material
- 1.4.1 Brown Kraft
- 1.4.2 White Kraft
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,904.04 million → 2032: USD 8,268.44 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Paper Bag Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Paper Bag Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Paper Bag Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Paper Bag Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Paper Bag Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Paper Bag Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Paper Bag Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Paper Bag Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,904.04 million → 2032: USD 8,268.44 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Paper Bag Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sewn Open Mouth
- 12.3.7.2 Pinch Bottom Open Mouth
- 12.3.7.3 Pasted Valve
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food & Beverages
- 12.4.7.2 E-commerce
- 12.4.7.3 Chemicals
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Brown Kraft
- 12.5.7.2 White Kraft
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Paper Bag Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Paper Bag Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Paper Bag Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Paper Bag Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novolex Holdings Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mondi
- 18.4 Oji Holdings Corporation
- 18.5 ProAmpac
- 18.6 United Bags
- 18.7 Huhtamaki Oyj
- 18.8 Welton Bibby & Baron Ltd
- 18.9 Smurfit Kappa
- 18.10 International Paper Company
- 18.11 Rengo Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

