
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Parental Control Software Market Size 2024 | USD 1,389.5 Million |
| Parental Control Software Market, CAGR | 11.82% |
| Parental Control Software Market Size 2032 | USD 3,396.36 Million |
Market Overview
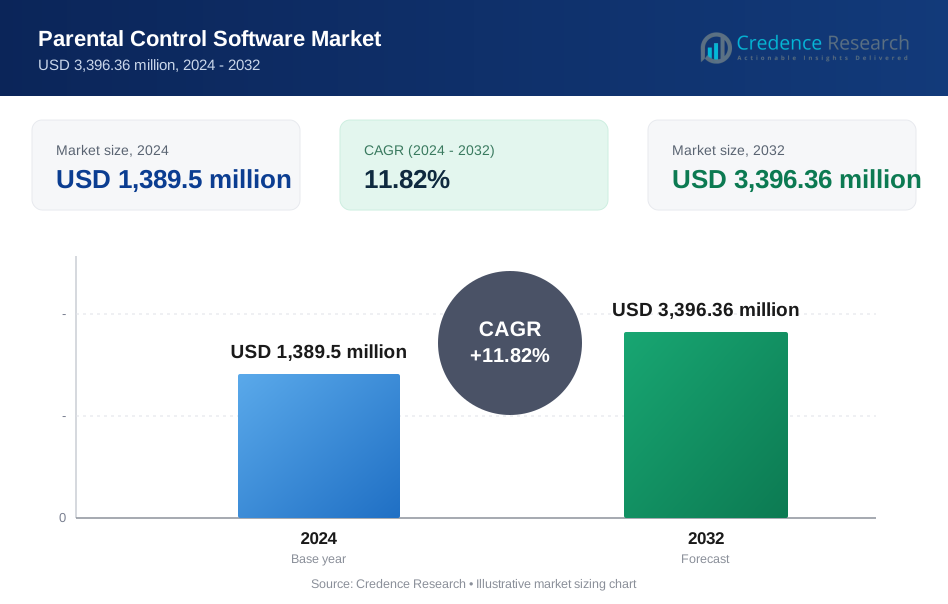
The Parental Control Software Market is projected to grow from USD 1,389.5 million in 2024 to USD 3,396.36 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.82%. The parental control software market is driven by the increasing need for safeguarding children in the digital age, with rising concerns over online privacy and exposure to inappropriate content. Advancements in technology, such as artificial intelligence and machine learning, enhance the effectiveness of these tools by enabling real-time monitoring and customized filtering options. Additionally, the growing trend of remote learning and increased screen time due to the pandemic has heightened the demand for robust parental control solutions. As parents seek to balance technology use and child safety, the market is poised for sustained growth and innovation. The parental control software market exhibits significant geographical variation, with North America and Europe leading in market share due to heightened awareness of online safety and regulatory support. Major players, including Microsoft Corporation, McAfee, and NortonLifeLock in the U.S., drive innovation with advanced features tailored to parental needs. Meanwhile, companies like AO Kaspersky Lab in Russia and Avast Software in the Czech Republic enhance their offerings in the European market. As demand grows, emerging players like Qustodio SL and Bark Technologies are gaining traction, contributing to a dynamic competitive landscape across various regions.Market Drivers
Rising Concerns about Online Safety and Cyberbullying Parents today face significant challenges regarding their children's safety online. The increasing exposure to harmful content, such as violence, explicit material, and online predators, raises alarms among caregivers. For instance, nearly half of teens aged 13-17 have been bullied or harassed online. Additionally, the prevalence of cyberbullying has become a pressing issue, emphasizing the need for parental oversight. By utilizing parental control software, parents can effectively monitor and mitigate these risks, ensuring their children engage with safe and appropriate content while navigating the digital landscape. Increased Use of Digital Devices The surge in digital device usage among children underscores the necessity of monitoring online activities. With early exposure to smartphones, tablets, and computers, young users are more vulnerable to potential dangers. For instance, most 2-year-olds in the United States use a digital device daily, and 9 out of 10 children are introduced to a device before their first birthday. Furthermore, the widespread use of social media platforms by minors invites risks like privacy breaches and online grooming. Parental control software plays a crucial role in this context, enabling parents to oversee their children's interactions and safeguard them against various online threats. Government Regulations and Awareness Campaigns Government initiatives and awareness campaigns are critical drivers in promoting the use of parental control software. Stricter data privacy regulations are being implemented to protect children's personal information, urging parents to adopt tools that enhance online safety. Public awareness initiatives are further highlighting the importance of parental supervision in the digital world, emphasizing the need for proactive measures to ensure a safer online environment for children. Advancements in Technology Recent advancements in technology have significantly enhanced parental control software's effectiveness. Sophisticated features such as location tracking, app blocking, and content filtering empower parents to manage their children's online experiences seamlessly. User-friendly interfaces and remote management capabilities also facilitate easier monitoring, allowing parents to ensure their children’s safety while promoting responsible internet usage. As parental involvement increases, these technological innovations provide peace of mind, fostering a secure digital space for children.Market Trends
Integration of IoT Devices and AI-Powered Features The integration of parental control software with Internet of Things (IoT) devices marks a significant trend in the market. As smart homes become increasingly prevalent, parents can now monitor and manage their children's online activities across various connected devices, providing a holistic approach to digital supervision. For instance, a survey conducted by a leading technology company revealed that a majority of parents found IoT-enabled parental control devices to be highly effective in monitoring their children’s online activities. Additionally, GPS-enabled devices facilitate real-time location tracking, which enhances children’s safety and offers peace of mind for parents. The utilization of artificial intelligence further elevates the effectiveness of these solutions. Advanced monitoring capabilities leverage AI to detect potential cyberbullying incidents, identify harmful content, and analyze usage patterns. Moreover, AI-driven personalized recommendations cater to a child's age, interests, and online behavior, ensuring a tailored experience that fosters safer internet use while encouraging responsible habits. Focus on Screen Time Management and Enhanced Privacy Amid growing concerns about excessive device usage, there is a strong focus on screen time management within parental control software. Parents are actively seeking tools to help their children develop healthy screen time habits, limiting their online engagement and promoting balanced lifestyles. Many software solutions offer features that enable parents to set time limits on device usage, ensuring children do not spend too much time online. Concurrently, the heightened emphasis on data protection has led parental control software providers to implement robust security measures to safeguard children’s personal information. As privacy concerns mount, encryption and other security features are increasingly adopted to protect sensitive data transmitted between devices. This dual focus on responsible screen time management and enhanced privacy ensures that children can enjoy a safe and balanced online experience, while parents maintain control over their digital environments.Market Challenges Analysis
Technological Limitations and Privacy Concerns One of the most pressing challenges facing parental control software is the rapid evolution of online threats and technological advancements. As new technologies emerge, so do sophisticated online dangers, making it increasingly difficult for software solutions to keep pace and effectively mitigate risks. For instance, a study by Concordia University found that many parental control solutions leak personal information and are vulnerable to attacks, betraying the trust of parents and children. Additionally, the proliferation of diverse devices and operating systems complicates the development of universally compatible software. This fragmentation can lead to inconsistencies in performance and reliability across different platforms, hindering parents’ ability to monitor their children's activities comprehensively. Alongside these technological hurdles, privacy concerns pose significant challenges for both parents and software providers. Many parents express apprehension about the extent of data collection by parental control applications, questioning how this information is utilized and safeguarded. The risk of data breaches and unauthorized access to children’s personal information further exacerbates these fears, creating a tension between the need for oversight and the desire for privacy. As these concerns linger, it becomes crucial for software developers to address these issues transparently, ensuring that users feel secure and informed about the data handling practices of the tools they employ. User Resistance and Cost Implications User resistance emerges as another significant challenge for parental control software. Children often perceive parental monitoring as an infringement on their autonomy, leading to feelings of restriction and conflict within the family dynamic. This resistance can hinder the effectiveness of the software, as children may actively seek ways to bypass controls or avoid open discussions about online safety. Furthermore, establishing trust between parents and children regarding online safety can be a complex process, complicating the implementation and enforcement of necessary parental controls. Compounding these challenges are the cost and complexity associated with many parental control solutions. While some software applications require ongoing subscription fees, which can be a financial burden for families, others present technical complexities that may deter non-tech-savvy parents from effectively setting up and managing these tools. The intricacies involved in configuring these systems can lead to frustration and ineffective monitoring, further undermining parents’ efforts to safeguard their children online. Addressing these multifaceted challenges will be critical for the continued success and adoption of parental control software in an increasingly complex digital landscape.Market Segmentation Analysis:
By Operating System The operating system segment of the parental control software market is dominated by three main platforms: Windows, Android, and iOS, along with cross-platform solutions. Windows remains a popular choice due to its widespread use in households and educational institutions. The flexibility of cross-platform software appeals to parents seeking comprehensive monitoring across various devices, including smartphones, tablets, and computers. Android holds a significant share, primarily because of its prevalence among mobile devices, allowing parents to manage their children's online activities seamlessly. iOS, while less customizable, provides robust security features and is favored by users seeking a more controlled environment. Each operating system segment caters to distinct user needs, making it crucial for software providers to develop tailored features that align with the unique functionalities of each platform. By Deployment In terms of deployment, the parental control software market is primarily segmented into on-premise and cloud-based solutions. On-premise deployment appeals to users who prioritize data security and wish to maintain complete control over their software and personal information. This option is often favored by educational institutions that require strict compliance with data protection regulations. Conversely, cloud-based deployment is gaining popularity due to its accessibility and ease of management. It allows parents to monitor their children's online activities from anywhere, using various devices. This flexibility caters to the increasing demand for real-time monitoring, making cloud solutions a preferred choice for many families. As both segments continue to evolve, providers must adapt their offerings to meet the diverse needs of consumers.Segments:
Based on Operating System- Windows
- Android
- iOS
- Cross Platform/Multiplatform
- On-premise
- Cloud
- Residential
- Educational Institutes
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America The North American region commands a substantial share of the parental control software market, accounting for approximately 35% of total revenue. This dominance is largely attributed to heightened awareness regarding online safety and privacy issues among parents, coupled with the widespread use of digital devices by children. The prevalence of cyberbullying and exposure to harmful online content have heightened the demand for comprehensive parental control solutions. North America benefits from a robust technological infrastructure, enabling the deployment of sophisticated software features such as real-time monitoring, location tracking, and content filtering. Furthermore, government initiatives aimed at promoting online safety, alongside increased media focus on child protection, have further driven parental demand for these solutions. As a result, companies in this region are continually innovating to offer enhanced features that cater to the specific needs of families. Asia-Pacific In contrast, the Asia-Pacific region is poised for rapid growth, with an expected market share increase from 20% to 30%. This surge is fueled by the increasing smartphone penetration and internet access among children, along with a rising awareness of the importance of online safety. Countries like India and China are experiencing a cultural shift towards prioritizing children's digital wellbeing, which has led parents to seek effective monitoring solutions. Additionally, the growing adoption of parental control measures within educational institutions supports market expansion, as schools recognize the need to ensure student safety in a digital environment. As technology continues to evolve, software developers are focusing on creating user-friendly and culturally relevant solutions that address the unique needs of families in the Asia-Pacific region, further driving the demand for parental control software.Key Player Analysis
- Microsoft Corporation (U.S.)
- Avast Software s.r.o. (Czech Republic)
- Bark Technologies, Inc. (U.S.)
- McAfee, LLC (U.S.)
- Qustodio SL (Family Zone Cyber Safety) (Spain)
- AO Kaspersky Lab (Russia)
- Alphabet Inc. (Google LLC) (U.S.)
- Mobicip LLC (U.S.)
- NortonLifeLock Inc. (U.S.)
- AT&T Inc. (U.S.)
Competitive Analysis
The parental control software market is highly competitive, characterized by key players like Alphabet Inc. (Google LLC), AT&T Inc., Mobicip LLC, McAfee, Microsoft Corporation, Avast Software s.r.o., NortonLifeLock Inc., AO Kaspersky Lab, Qustodio SL, and Bark Technologies, Inc. Key players differentiate themselves by providing user-friendly interfaces, advanced monitoring capabilities, and strong data privacy protections. Some companies focus on seamless integration with various devices and operating systems, enhancing the overall user experience. Others prioritize customization options that cater to diverse parental needs and preferences, such as screen time management and content filtering. Additionally, ongoing advancements in technology, including AI-powered features, enable these firms to stay ahead of emerging online threats. As consumer demand for online safety and monitoring grows, competition within the market intensifies, driving continuous improvement and innovation in parental control solutions.Recent Developments
- In January 2024, Snapchat announced the launch of new parental control that allows parents to control their kids' usage of the MyAI chatbot. With the new feature, parents can control and monitor their children’s privacy settings and quickly access the family center, specially developed for parental control.
- In August 2023, Xsolla removed obstructions for direct-to-consumer delivery with an incorporated parental control capability for game developers. With the introduction of the parental control feature range, Xsolla's product line permits developers to assimilate an extra level of authentication for parents.
- In May 2023, Kaspersky launched an updated version of its Safe Kids mobile platform application. The new upgrade comprises a new interface and design for applications, along with advanced features, such as banner hints focused on offering parents tips and settings for better control and digital safety of their children. The new version is available on both iOS and Android.
- In April 2023, Internet Matters and Amazon Kids announced a collaboration to offer resources for carers and parents to help their children navigate through the digital experience. The resources are provided through the Family Digital Well-Being Hub of Amazon, proposing a better understanding of family-friendly devices and ensuring safety from connected technology.
- In February 2023, Bark Technologies collaborated with Vilo Living. Vilo Living is a startup that delivers affordable, reliable, and easy Wi-Fi connectivity. The alliance allows Vilo consumers to benefit from Bark's parental control solutions by assimilating in-home parental controls within mesh Wi-Fi systems of Vilo without any extra cost to all end users in the U.S.
- In January 2023, Linewise (a division of Family Zone) introduced Qustodio, its new parental control application, accessible to all classwise customers and school managers. Being part of the Linewise Community, Qustodio expands visibility, controls, and reporting to guardians and parents on the usage of school-allotted devices at home and school.
Market Concentration & Characteristics
The parental control software market exhibits moderate concentration, with several key players dominating the landscape while numerous smaller companies also contribute to the competitive dynamics. This dual structure fosters innovation and diversity in offerings, as larger firms leverage their resources to develop advanced features and comprehensive solutions. Key characteristics of the market include rapid technological advancements, such as the integration of artificial intelligence and machine learning, which enhance monitoring capabilities and provide personalized user experiences. Additionally, the market is characterized by a growing emphasis on data privacy and security, prompting providers to adopt stringent measures to protect sensitive user information. Subscription-based pricing models are becoming increasingly prevalent, allowing for continuous updates and access to the latest features. Furthermore, the rising awareness of online safety among parents drives demand, creating opportunities for both established and emerging companies to capture market share by addressing specific consumer needs and preferences effectively.Report Coverage
The research report offers an in-depth analysis based on Operating System, Deployment, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The parental control software market is expected to witness significant growth driven by increasing concerns about children's online safety.
- Integration with artificial intelligence will enhance monitoring capabilities and provide personalized recommendations for users.
- The adoption of subscription-based models will become more common, offering ongoing updates and flexibility for consumers.
- Enhanced privacy features will be a priority, addressing growing concerns about data security and protecting children's personal information.
- There will be a rise in cross-platform compatibility, allowing users to manage parental controls across multiple devices seamlessly.
- The demand for screen time management tools will increase, promoting healthy digital habits among children.
- Educational institutions will increasingly adopt parental control measures to ensure student safety in digital environments.
- Partnerships with IoT device manufacturers will expand, facilitating comprehensive monitoring of children's online activities.
- Gamification elements will be integrated into parental control solutions, making online safety education more engaging for children.
- The market will see increased regulatory scrutiny, prompting software providers to comply with stricter data protection regulations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Concerns about Online Safety and Cyberbullying
Growing awareness of online threats such as cyberbullying, exposure to inappropriate content, and online predators is prompting parents to adopt parental control software to safeguard children’s digital experiences.
Increased Use of Digital Devices
The proliferation of smartphones, tablets, and computers among children has heightened the need for monitoring and managing online activities, driving demand for comprehensive parental control solutions.
Government Regulations and Awareness Campaigns
Stricter data privacy laws and public awareness initiatives are encouraging parents and educational institutions to implement parental control software to comply with regulations and ensure child safety online.
Advancements in Technology
Innovations such as artificial intelligence, machine learning, and IoT integration are making parental control tools more effective, user-friendly, and capable of real-time monitoring, thus boosting market adoption.
Screen Time Management and Digital Wellbeing
Concerns about excessive screen time and its impact on children’s health are leading parents to seek software that enables them to set limits and promote balanced digital habits.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Parental Control Software market?
What factors are driving the growth of the Parental Control Software market?
What are the key segments within the Parental Control Software market?
What are some challenges faced by the Parental Control Software market?
Who are the major players in the Parental Control Software market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Deployment
- 1.2.1 On-premise
- 1.2.2 Cloud
- 1.3 By Application
- 1.3.1 Residential
- 1.3.2 Educational Institutes
- 1.4 By Operating System
- 1.4.1 Windows
- 1.4.2 Android
- 1.4.3 iOS
- 1.4.4 Cross Platform/Multiplatform
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,389.5 million → 2032: USD 3,396.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Parental Control Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Parental Control Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Parental Control Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Parental Control Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Parental Control Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Parental Control Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Parental Control Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Parental Control Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,389.5 million → 2032: USD 3,396.36 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Parental Control Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Deployment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 On-premise
- 12.3.6.2 Cloud
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Residential
- 12.4.6.2 Educational Institutes
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Operating System - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Windows
- 12.5.6.2 Android
- 12.5.6.3 iOS
- 12.5.6.4 Cross Platform/Multiplatform
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Parental Control Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Parental Control Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Parental Control Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Parental Control Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 McAfee, LLC
- 18.4 NortonLifeLock Inc.
- 18.5 Avast Software s.r.o.
- 18.6 AO Kaspersky Lab
- 18.7 Qustodio SL (Family Zone Cyber Safety)
- 18.8 Bark Technologies, Inc.
- 18.9 Alphabet Inc. (Google LLC)
- 18.10 Mobicip LLC
- 18.11 AT&T Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

