
Polymer Based Prefilled Syringe Market Overview:
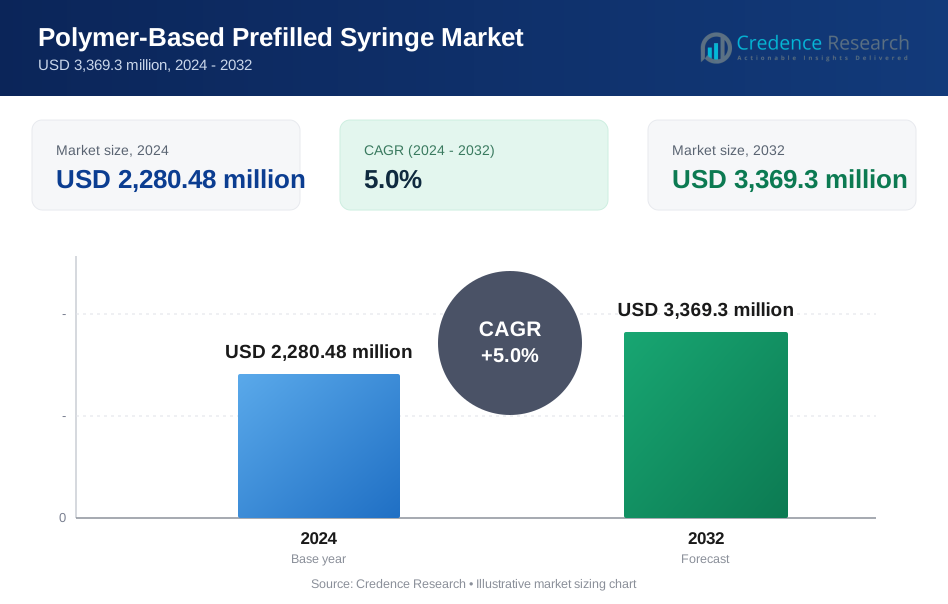
The Polymer Based Prefilled Syringe Market size was valued at USD 2,280.48 million in 2024 and is anticipated to reach USD 3,369.3 million by 2032, at a CAGR of 5.0% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polymer Based Prefilled Syringe Market Size 2024 | USD 2,280.48 million |
| Polymer Based Prefilled Syringe Market, CAGR | 5.0% |
| Polymer Based Prefilled Syringe Market Size 2032 | USD 3,369.3 million |
Top players in the polymer-based prefilled syringe market include Becton, Dickinson and Company, Gerresheimer AG, Schott Pharma, Terumo Corporation, Stevanato Group, West Pharmaceutical Services, Inc., and Baxter International Inc. These companies lead through advanced manufacturing capabilities, strategic partnerships with pharmaceutical firms, and innovations in cyclic olefin materials. Becton, Dickinson and Company holds a dominant share due to its broad syringe portfolio and global distribution. Gerresheimer and Schott Pharma strengthen their positions through precision glass-to-polymer transitions and automation-ready designs. North America leads the global market with a 35% share in 2024, driven by biologics growth, home healthcare adoption, and regulatory support. Europe follows closely due to high safety standards and strong pharmaceutical manufacturing.

Polymer Based Prefilled Syringe Market Insights
- The Polymer Based Prefilled Syringe Market was valued at USD 2,280.48 million in 2024 and is projected to reach USD 3,369.3 million by 2032, growing at a CAGR of 5.0% during the forecast period.
- Rising demand for biologics and specialty injectables is driving strong adoption of polymer-based syringes due to their durability, purity, and compatibility with sensitive formulations.
- A key trend is the shift toward self-administration and home healthcare, increasing demand for ready-to-use, lightweight, and break-resistant syringe formats.
- The market is competitive with leading players like Becton, Dickinson and Company, Gerresheimer AG, and Schott Pharma focusing on innovation, automation, and drug-device integration.
- North America leads with a 35% share, followed by Europe at 30% and Asia Pacific at 22%; by capacity, the up to 5 ml segment dominates with over 55% share due to high use in vaccines, insulin, and chronic therapy.
Polymer Based Prefilled Syringe Market Segmentation Analysis:
By Material
Cyclic Olefin Polymer (COP) dominates the material segment, accounting for over 60% of the market share in 2024. COP’s superior moisture barrier properties, high transparency, and strong chemical resistance make it the preferred choice for biologics and sensitive formulations. Its dimensional stability supports automated fill-finish processes in large-scale production. Cyclic Olefin Copolymer (COC), while gaining adoption, trails due to relatively lower resistance under high-stress conditions. However, COC remains viable in cost-sensitive settings requiring moderate barrier performance. Overall, demand for COP is driven by the increasing shift toward biologics and stricter contamination control in injectable drug delivery.
- For instance, SCHOTT’s TOPPAC COP syringes show water vapor transmission rates below 0.1 g/m²/day and maintain dimensional tolerances within ±0.05 mm for automated fill-finish lines.
By Capacity
The “Up to 5 ml” segment leads the capacity category, holding nearly 55% market share in 2024. This dominance is due to the high volume of standard-dose applications in vaccines, insulin, and emergency injectables. Smaller volume syringes offer better dose accuracy and are compatible with autoinjectors and wearable injectors, making them popular in self-administration settings. The 6 ml to 20 ml range serves larger biologic or infusion therapies, especially in oncology and specialty care. While demand is growing in higher capacity formats, product standardization, regulatory familiarity, and manufacturing ease continue to favor the up to 5 ml segment.
- For instance, BD’s 1 mL prefillable syringe platform supports fill volumes as low as 0.25 mL and meets ISO 11040 dimensional standards for autoinjectors.
By End‑use
Hospitals represent the largest end-use segment, contributing more than 40% of total market share in 2024. High patient volume, emergency care demands, and broad therapeutic use cases drive syringe adoption in hospital settings. Clinics and ambulatory surgery centers follow due to rising outpatient procedures and demand for time-saving, ready-to-administer formats. Research laboratories and clinical research centers contribute steadily as polymer-based syringes reduce interaction with reactive compounds during trials. Drug manufacturing facilities increasingly use prefilled formats for bulk packaging in vaccine and therapeutic production. However, hospitals remain the key demand center due to standardized workflows and safety requirements.
Polymer Based Prefilled Syringe Market Key Growth Drivers
Rising Adoption of Biologics and Specialty Injectable Drugs
The growing use of biologics and specialty injectables strongly drives the polymer‑based prefilled syringe market. Biologic drugs require high container purity, low extractables, and strong barrier protection. Polymer syringes meet these needs better than traditional glass formats. Cyclic olefin materials reduce risks of breakage, delamination, and drug interaction. Pharmaceutical companies increasingly prefer ready‑to‑use delivery systems to ensure drug stability and patient safety. Growth in monoclonal antibodies, vaccines, and hormone therapies supports consistent demand. Many biologics also target chronic conditions, increasing long‑term syringe consumption. The shift toward self‑administered therapies further boosts adoption. Polymer syringes support autoinjectors and wearable devices used in home care. Regulatory focus on drug integrity and contamination control also favors advanced polymer packaging. Together, biologic pipeline expansion and delivery safety needs create sustained demand momentum.
- For instance, SCHOTT’s TOPPAC COP syringes demonstrate extractables below 10 µg per device under USP <1663> testing, supporting monoclonal antibody stability. Ready-to-use formats improve safety and efficiency.
Expansion of Self‑Administration and Home Healthcare Models
Self‑administration trends significantly accelerate market growth for polymer‑based prefilled syringes. Patients increasingly manage chronic diseases at home using injectable therapies. Prefilled syringes simplify dosing and reduce preparation errors. Polymer materials improve handling safety by minimizing breakage risks. Lightweight designs enhance patient comfort and ease of use. Home healthcare growth reduces hospital burden and supports cost‑effective treatment delivery. Devices compatible with polymer syringes, such as autoinjectors, improve adherence and treatment outcomes. Aging populations and rising prevalence of diabetes, autoimmune disorders, and hormonal deficiencies increase demand. Healthcare systems also promote home care to control costs. Polymer syringes align well with these models due to durability and user safety. This shift in care delivery strongly supports long‑term market expansion.
- For instance, BD’s polymer prefillable syringes withstand drop testing from 1.2 meters without structural failure, supporting home use. Lightweight design improves handling comfort.
Technological Advancements in Drug Packaging and Fill‑Finish Processes
Continuous innovation in drug packaging technologies drives polymer‑based prefilled syringe adoption. Manufacturers invest in advanced molding, coating, and sterilization techniques to improve performance. Polymer syringes offer high dimensional accuracy, supporting automated fill‑finish operations. Automation improves production speed, consistency, and regulatory compliance. Reduced silicone oil usage lowers risks of protein aggregation. Enhanced barrier properties extend shelf life for sensitive drugs. Packaging innovation also supports combination products and device integration. Pharmaceutical companies seek scalable, efficient systems for large biologic pipelines. Polymer formats help reduce recalls linked to glass defects. As fill‑finish capacity expands globally, demand for compatible polymer syringes continues to rise. Technology‑driven efficiency gains remain a key growth driver.
Polymer Based Prefilled Syringe Market Key Trends & Opportunities
Shift from Glass to Polymer Syringes for Safety and Reliability
A major trend is the gradual shift from glass to polymer‑based prefilled syringes. Polymer formats reduce breakage during transport and clinical use. This improves safety for healthcare workers and patients. Manufacturers also benefit from lower product loss rates. Polymer syringes resist delamination and surface defects common in glass. This reliability is critical for high‑value biologics. Regulatory scrutiny on container integrity further accelerates this shift. Drug developers increasingly specify polymer syringes early in formulation stages. As confidence in polymer performance grows, adoption expands across therapeutic areas. This trend creates strong replacement opportunities within existing injectable portfolios.
- For instance, West Pharmaceutical Services reports that Daikyo Crystal Zenith polymer syringes show zero breakage incidents during simulated shipping vibration and drop testing at 1.2 meters.
Growth Opportunities in Emerging Markets and Contract Manufacturing
Emerging pharmaceutical markets present strong growth opportunities. Expanding vaccine programs and biologic production increase demand for prefilled formats. Contract development and manufacturing organizations scale fill‑finish capacity in Asia and Latin America. These facilities favor polymer syringes for automation compatibility and safety. Governments also invest in domestic drug manufacturing infrastructure. Rising clinical trial activity increases demand from research centers. Local production reduces reliance on imports and supports regional supply chains. Polymer syringes enable faster market entry for injectable drugs. This combination of manufacturing expansion and healthcare investment creates long‑term opportunity potential.
Key Challenges
Higher Material and Manufacturing Costs Compared to Glass
Cost remains a key challenge for polymer‑based prefilled syringes. Advanced polymer materials cost more than traditional glass. Specialized molding and quality control add to production expenses. Smaller manufacturers face barriers to large‑scale adoption. Price sensitivity in emerging markets limits rapid transition. Pharmaceutical companies weigh cost against performance benefits. Regulatory validation also increases upfront investment. These factors can slow adoption in cost‑driven therapeutic segments. Managing cost efficiency remains critical for broader market penetration.
Regulatory Complexity and Material Compatibility Concerns
Regulatory approval presents another challenge. Polymer materials must demonstrate long‑term drug compatibility. Extensive testing is required for extractables and leachables. Approval timelines may extend during product development. Any formulation change can trigger revalidation. This adds complexity for pharmaceutical developers. Regulatory expectations vary across regions, increasing compliance burden. Smaller firms may lack resources for extensive testing programs. Addressing these concerns requires close collaboration between drug and packaging manufacturers. Regulatory complexity can delay adoption despite performance advantages.
Polymer Based Prefilled Syringe Market Regional Analysis
North America
North America holds the largest share in the polymer-based prefilled syringe market, accounting for over 35% in 2024. The region benefits from high biologics adoption, advanced drug delivery technologies, and well-established healthcare infrastructure. The U.S. leads due to rising demand for self-administered injectables and the presence of major pharmaceutical manufacturers. Regulatory clarity from the FDA supports innovation in polymer-based packaging. Home healthcare trends and an aging population further drive syringe use. Additionally, the region sees high penetration of combination devices, such as autoinjectors and prefilled systems. Continuous R&D and high biologic consumption sustain regional market dominance.
Europe
Europe captures around 30% of the global polymer-based prefilled syringe market in 2024. Germany, France, and the UK lead regional growth through strong biologics demand and clinical research investments. The region prioritizes safety and sustainability in medical packaging, driving polymer adoption. EU-wide regulations encourage low-leachables and high-purity delivery systems. Prefilled syringes are widely used in immunization and chronic therapy programs across public healthcare settings. Increasing contract manufacturing capabilities and government-backed healthcare access continue to support syringe demand. With a mature pharmaceutical base and growing preference for break-resistant containers, Europe remains a key consumer of polymer formats.
Asia Pacific
Asia Pacific accounts for about 22% of the global market and stands as the fastest-growing region. Rising biologics production, expanding healthcare infrastructure, and growing chronic disease prevalence drive strong demand. China, Japan, South Korea, and India lead regional consumption. Local manufacturing capacity is increasing to meet domestic and export needs. Cost-effective polymer syringe formats support large-scale immunization programs. Moreover, contract development and manufacturing organizations (CDMOs) across the region boost fill-finish capacity. The shift toward modern, safer packaging in injectable drugs is driving polymer-based product expansion. Favorable government policies and high patient volume create long-term growth momentum.
Latin America
Latin America holds a modest share of around 7% in 2024 but offers steady growth potential. Brazil and Mexico are key contributors, supported by expanding pharmaceutical sectors and rising chronic disease treatment. Prefilled syringes gain traction in hospital procurement and vaccine programs. As regulatory frameworks mature, polymer syringes gain preference for their safety and stability. The region also sees growing partnerships with international drug manufacturers and CDMOs. While cost sensitivity remains a barrier to premium formats, ongoing health reforms and increasing public health expenditure create a favorable environment for polymer-based syringe adoption.
Middle East & Africa (MEA)
The Middle East & Africa region contributes about 6% of the global market in 2024. Market growth is driven by expanding immunization efforts, rising access to specialty care, and growing investments in healthcare infrastructure. GCC countries like Saudi Arabia and the UAE lead in terms of hospital upgrades and advanced therapeutic availability. Polymer-based prefilled syringes are increasingly adopted in public health procurement for safety and durability. However, adoption rates are slower in sub-Saharan regions due to limited budgets and infrastructure gaps. International aid programs and localized manufacturing partnerships could improve access and uptake over time.
Polymer Based Prefilled Syringe Market Segmentations:
By Material
- Cyclic Olefin Polymer (COP)
- Cyclic Olefin Copolymer (COC)
By Capacity
- Up to 5 ml
- 6 ml to 20 ml
- 21 ml to 40 ml
- Above 40 ml
By End‑use
- Hospitals
- Clinics
- Ambulatory Surgery Centers
- Research Laboratories
- Drug Manufacturing
- Clinical Research Centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The polymer-based prefilled syringe market features strong competition among leading players focused on innovation, quality, and scalability. Key companies such as Becton, Dickinson and Company, Gerresheimer AG, and Schott Pharma dominate through broad portfolios and high production capacities. Terumo Corporation and Stevanato Group emphasize advanced polymer technologies for injectable drug delivery, catering to both branded pharmaceuticals and CDMOs. West Pharmaceutical Services, Inc. and Baxter International Inc. enhance their market presence with integrated device systems and strategic collaborations. Players compete on material innovation, fill-finish compatibility, regulatory compliance, and drug-device integration. Customization for biologics, expansion of global manufacturing networks, and investments in automation further differentiate market leaders. Continuous product launches, partnerships with pharmaceutical firms, and regional expansion strategies define the evolving competitive dynamics.
Key Player Analysis
- Becton, Dickinson and Company
- Gerresheimer AG
- Schott Pharma
- Terumo Corporation
- Stevanato Group
- West Pharmaceutical Services, Inc.
- Baxter International Inc.
Recent Developments
- In 2023, Stevanato Group announced collaboration with Transcoject to provide pre-fillable syringe polymer options for pharmaceutical industry.
- In 2023, Gerresheimer announced the new construction of the plant at its Querétaro, Mexico, with a ground-breaking ceremony to increase its manufacturing capacity for RTF syringes for the North American market.
- In 2022, BD Company and Mitsubishi Gas Chemical Company, Inc. announced collaboration for development of OXYCAPT which is an innovation from MGC that integrates the best of plastic and glass for plastic syringes.
Report Coverage
The research report offers an in-depth analysis based on Material, Capacity, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for polymer-based prefilled syringes will grow with rising adoption of biologic therapies.
- Self-administration and homecare trends will continue to favor lightweight, break-resistant syringe formats.
- Advanced polymer materials will see increased use due to their compatibility with sensitive drug formulations.
- Automation in fill-finish processes will drive adoption of dimensionally stable polymer syringes.
- Pharmaceutical companies will favor polymer formats to reduce risks of contamination and glass breakage.
- Expansion in emerging markets will create new opportunities for low-cost, high-quality polymer syringes.
- Integration with autoinjectors and wearable injectors will expand the use of polymer-based delivery systems.
- Regulatory support for safe and clean injectable packaging will support wider market penetration.
- Innovation in design, such as low-silicone and high-barrier syringes, will enhance drug stability.
- Strategic partnerships between drug manufacturers and syringe suppliers will shape future supply chains.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Polymer based prefilled syringe market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polymer based prefilled syringe market projected to grow between 2024 and 2032?
Which Polymer based prefilled syringe market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polymer based prefilled syringe market?
Who are the leading companies in the Polymer based prefilled syringe market?
Which region commanded the largest share of the Polymer based prefilled syringe market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Polymer-Based Prefilled Syringe Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Polymer-Based Prefilled Syringe Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,280.48 million → 2032: USD 3,369.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Polymer-Based Prefilled Syringe Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Polymer-Based Prefilled Syringe Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Polymer-Based Prefilled Syringe Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Polymer-Based Prefilled Syringe Market Drivers
- 3.3 Polymer-Based Prefilled Syringe Market Restraints & Challenges
- 3.4 Polymer-Based Prefilled Syringe Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Polymer-Based Prefilled Syringe Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Polymer-Based Prefilled Syringe Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Polymer-Based Prefilled Syringe category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Polymer-Based Prefilled Syringe Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Polymer-Based Prefilled Syringe Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Polymer-Based Prefilled Syringe market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Polymer-Based Prefilled Syringe Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Polymer-Based Prefilled Syringe Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Polymer-Based Prefilled Syringe Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Polymer-Based Prefilled Syringe (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Polymer-Based Prefilled Syringe Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Polymer-Based Prefilled Syringe Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Polymer-Based Prefilled Syringe Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Polymer-Based Prefilled Syringe Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Polymer-Based Prefilled Syringe Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Polymer-Based Prefilled Syringe Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Polymer-Based Prefilled Syringe Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Polymer-Based Prefilled Syringe Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Polymer-Based Prefilled Syringe Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
