
Market overview
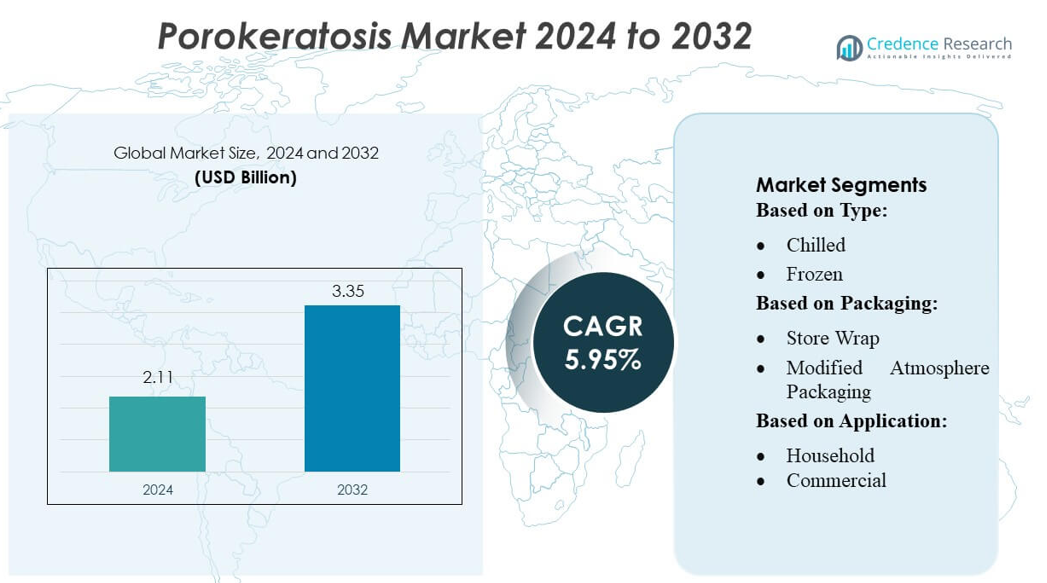
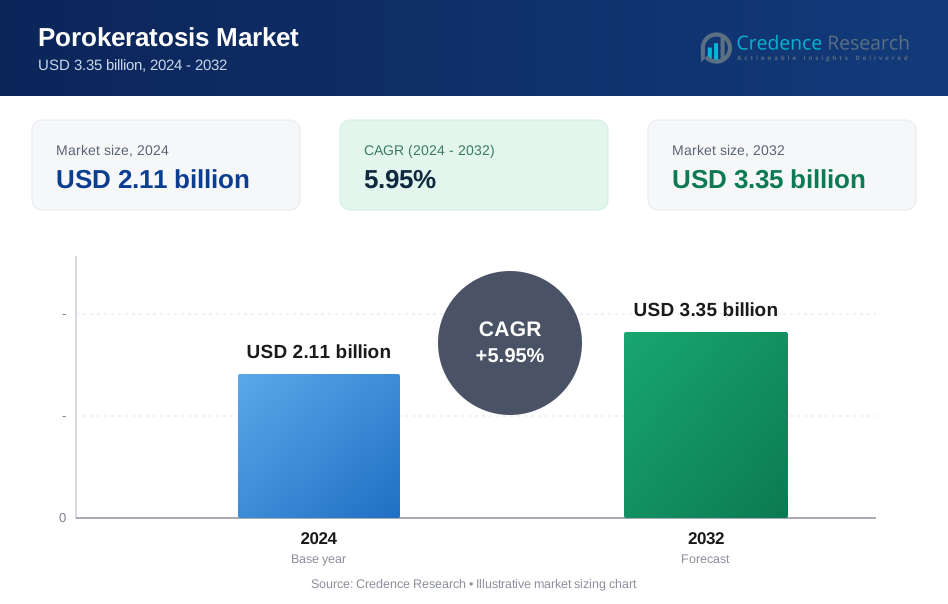
Porokeratosis Market size was valued USD 2.11 billion in 2024 and is anticipated to reach USD 3.35 billion by 2032, at a CAGR of 5.95% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Porokeratosis Market Size 2024 | USD 2.11 billion |
| Porokeratosis Market, CAGR | 5.95% |
| Porokeratosis Market Size 2032 | USD 3.35 billion |
The Porokeratosis Market is shaped by a focused group of dermatology-specialized pharmaceutical companies, biotechnology innovators, and medical device manufacturers developing advanced topical formulations, photodynamic therapy systems, and laser-based solutions. These companies compete through R&D investments, clinical trial advancements, and expansion of precision-medicine tools that enhance diagnosis and treatment outcomes for chronic porokeratosis subtypes. North America leads the global market with approximately 35% share, supported by strong dermatology infrastructure, high awareness of rare skin disorders, and rapid adoption of advanced diagnostic and therapeutic technologies, positioning the region at the forefront of innovation and commercial growth.
Market Insights
- The Porokeratosis Market was valued at USD 2.11 billion in 2024 and is projected to reach USD 3.35 billion by 2032, expanding at a CAGR of 5.95%, reflecting steady global demand for improved diagnostic and therapeutic solutions.
- Market growth is driven by rising diagnostic awareness, increasing prevalence of keratinization disorders, and the adoption of advanced treatments such as photodynamic therapy, laser procedures, and targeted topical formulations.
- Emerging trends include expanding precision dermatology, AI-enabled skin analysis, and growing clinical adoption of combination therapies that improve patient outcomes and reduce recurrence rates.
- Competitive activity is intensifying as dermatology-focused pharmaceutical companies and device manufacturers accelerate R&D investments, advance clinical pipelines, and strengthen partnerships to address unmet needs in chronic porokeratosis management.
- Regionally, North America holds 35% share, followed by Europe at 28% and Asia-Pacific at 25%, while treatment-type segmentation shows topical therapies dominating with nearly 40% share due to high accessibility and strong clinical preference.
Market Segmentation Analysis:
By Type
The Porokeratosis market, segmented by Chilled and Frozen formulations, shows Frozen products holding the largest market share due to their longer shelf stability, reduced degradation of active dermatological compounds, and wider suitability for bulk distribution. Frozen formats dominate as manufacturers prioritize controlled-temperature logistics to maintain potency across extended supply chains. Chilled variants continue to serve niche hospital and specialty pharmacy requirements, but the increasing adoption of long-life dermatological preparations drives the prominence of Frozen products. Growth is further supported by improvements in cold-chain infrastructure and rising clinical preference for formulations with consistent bioavailability.
- For instance, Palvella Therapeutics is developing a topical pitavastatin gel (QTORIN™) for disseminated superficial actinic porokeratosis, aiming to enroll approximately 10–20 patients in a Phase 2 trial planned for the second half of 2026.
By Packaging
Within packaging formats, Modified Atmosphere Packaging (MAP) accounts for the dominant market share, driven by its ability to preserve formulation integrity, extend stability timelines, and minimize oxidative degradation of sensitive dermatological ingredients used in Porokeratosis treatment products. MAP’s controlled gas composition makes it preferable for pharmaceutical distributors seeking enhanced durability during transit. Vacuum Packaging and Store Wrap serve cost-efficient roles in short-duration storage, while Shrink Bags and Others support secondary or bulk handling. However, MAP leads due to its superior contamination prevention, longer preservation capability, and compatibility with sterile product handling processes.
- For instance, Marfrig has strongly committed to sustainability through its Verde+ program, investing BRL 500 million to ensure a deforestation-free cattle supply chain.
By Application
In application segments, Commercial use-encompassing hospitals, dermatology clinics, and specialty treatment centers-holds the majority market share. This dominance stems from higher patient footfall, greater reliance on clinically validated formulations, and continual procurement of temperature-controlled dermatological products. The Commercial segment benefits from structured treatment protocols, specialized storage facilities, and stronger demand for advanced Porokeratosis therapies. Household usage is gradually rising as awareness grows, but remains smaller due to prescription-based access, clinical supervision requirements, and limited patient capability to manage chilled or frozen therapeutic products at home.
Key Growth Drivers
Growing Prevalence of Genetic and Immunologic Disorders
The rising incidence of genetic mutations affecting keratinization pathways and the growing population with immunocompromised conditions such as organ-transplant recipients significantly drive market growth. Increased diagnostic awareness and improved dermatological screening have expanded the patient pool, leading to higher demand for targeted therapies. Advancements in genetic testing help clinicians identify subtype-specific markers, enabling more accurate diagnosis and earlier intervention. This trend strengthens the need for personalized treatment approaches and supports steady demand for both topical and systemic therapies across global healthcare settings.
- For instance, WH Group reported US$ 173 million in R&D investment in its 2024 annual report. It holds at least 15 patents in meat-processing and flavor technologies, according to a VRIO analysis.
Advancements in Dermatology and Targeted Treatment Modalities
Technological progress in dermatology, including improved photodynamic therapy systems, laser-based interventions, and emerging immunomodulators, fuels treatment adoption. Pharmaceutical innovation in retinoid formulations, kinase inhibitors, and non-invasive procedures has accelerated clinical acceptance of new regimens. Clinicians now have improved tools to manage difficult-to-treat subtypes such as disseminated superficial actinic porokeratosis (DSAP). The continuous pipeline of investigational drugs and device-based solutions further strengthens market expansion, offering safer, more effective treatment alternatives that align with evolving patient expectations for convenience and rapid results.
- For instance, Cargill Beauty division reports offering a broad portfolio of nature-derived ingredients for personal care, including bio-actives, emollients, and emulsifiers, such as the skin-lipid-mimetic ingredient L22®.
Increasing Focus on Rare Disease Research and Funding Support
Growing prioritization of rare dermatological disorders is boosting research funding, clinical trials, and collaborative programs aimed at improving understanding of porokeratosis. Government agencies and private foundations are increasingly supporting studies that explore pathogenesis, genetic markers, and therapeutic targets. This financial support encourages pharmaceutical companies to invest in niche dermatology portfolios. Expanding patient-registries and multi-center collaborations also generate stronger epidemiological data, helping stakeholders assess unmet clinical needs and justify advancements in therapy development, ultimately contributing to steady long-term market growth.
Key Trends & Opportunities
Growing Adoption of Precision and Personalized Dermatology
Precision-medicine approaches are gaining traction as clinicians use molecular diagnostics, AI-based dermoscopy, and genetic profiling to guide treatment decisions for porokeratosis. This shift creates opportunities for targeted drug development, particularly therapies that modulate keratinization pathways or address mutation-specific subtypes. Personalized dosing strategies and treatment planning tools enhance clinical outcomes, encouraging healthcare providers to adopt advanced technologies. Companies focusing on biomarker-driven dermatology solutions are well-positioned to capitalize on demand for tailored therapies and predictive decision-support platforms.
- For instance, Tyson Ventures selected 6 AI-driven startups-including Prevera, which designs antimicrobial proteins, and Proxy Foods, whose AI “virtual scientist” aims to accelerate R&D timelines by up to half.
Rising Integration of Non-Invasive and Combination Therapies
Combination regimens, including topical agents paired with laser, cryotherapy, or photodynamic therapy, are increasingly preferred for improved efficacy and reduced recurrence in chronic cases. Demand for non-invasive options is rising as patients seek safer alternatives with minimal downtime. Innovations in light-based systems and next-generation topical formulations expand treatment variety, creating opportunities for device manufacturers and specialty pharmaceutical companies. Enhanced clinician training and improved reimbursement frameworks further support the adoption of multimodal approaches across hospital and dermatology clinic settings.
- For instance, JBS reports deploying over 210 intelligent automation solutions to streamline business processes, which as of 2022, had saved the company an estimated.
Expanding Tele-Dermatology and Digital Monitoring Solutions
The rapid adoption of tele-dermatology platforms provides new opportunities for remote assessment, long-term monitoring, and image-based diagnosis of porokeratosis lesions. Digital tools, including AI-enhanced skin-analytics applications, support earlier detection and reduce diagnostic delays, particularly in underserved regions. These technologies help dermatologists track lesion progression, optimize treatment adjustments, and improve patient compliance. The trend accelerates market penetration for topical therapies and medical devices by enabling consistent follow-up and treatment continuity, strengthening digital health’s role in dermatology care pathways.
Key Challenges
Limited Availability of Curative Therapies and High Recurrence Rates
Porokeratosis lacks a definitive cure, creating persistent challenges for patients and clinicians. Existing therapies primarily focus on symptom management and cosmetic improvement, yet recurrence remains common, especially in chronic or genetically driven subtypes. Limited therapeutic efficacy and inconsistent long-term outcomes hinder patient satisfaction and complicate clinical decision-making. The scarcity of robust clinical trial data and FDA-approved targeted treatments further slows innovation. These limitations restrict broader market adoption and emphasize the need for research into more durable and disease-modifying therapies.
Diagnosis Complexity and Under-Recognition in Early Stages
Diagnostic challenges stem from porokeratosis’ diverse clinical presentations, overlapping symptoms with other keratinization disorders, and limited awareness among general practitioners. Early-stage lesions are often misdiagnosed or overlooked, resulting in delayed treatment and increased risk of malignant transformation in certain subtypes. Variation in diagnostic standards across regions further complicates disease identification and reporting accuracy. These barriers reduce treatment uptake and create inconsistencies in patient management, underscoring the need for improved training, standardized diagnostic protocols, and expanded access to dermatology specialists.
Regional Analysis
North America
North America leads the porokeratosis market with approximately 35% share, driven by high dermatology care access, strong awareness of rare skin disorders, and advanced diagnostic infrastructure. The region benefits from well-established reimbursement frameworks that support photodynamic therapy, laser procedures, and prescription dermatological products. Extensive clinical research initiatives and active participation in rare disease registries strengthen early detection and management. The U.S. dominates regional revenue due to a high concentration of dermatology specialists and innovative treatment providers. Growing investment in genetic research and precision dermatology further enhances therapeutic adoption.
Europe
Europe accounts for roughly 28% of the market, supported by robust healthcare systems, high dermatology specialization, and strong regulatory oversight that encourages adoption of safe, evidence-based therapies. Countries such as Germany, France, and the U.K. dominate due to widespread clinical use of combination therapies, including cryotherapy, topical retinoids, and laser-based solutions. Growing initiatives to improve rare disease reporting and increased funding for skin cancer prevention indirectly support porokeratosis diagnosis and treatment. The EU’s structured patient pathways and cross-border healthcare collaborations further enhance clinical outcomes and market expansion.
Asia-Pacific
Asia-Pacific holds an estimated 25% market share and represents the fastest-growing region due to its large patient base and rising awareness of keratinization disorders. Countries such as China, Japan, India, and South Korea are witnessing expanding dermatology services, improved diagnostic accuracy, and increased adoption of minimally invasive treatments. Economic growth and healthcare modernization further support uptake of topical and device-based therapies. Regional research interest in genetic variants of porokeratosis enhances clinical understanding. However, uneven specialist availability and varying reimbursement structures create market disparities across urban and rural areas.
Latin America
Latin America captures around 7% of the global market, supported by gradual improvements in dermatology infrastructure and growing public awareness of chronic and rare skin conditions. Brazil and Mexico remain the primary contributors due to better access to dermatology clinics and increasing adoption of photodynamic therapy and topical solutions. However, limited specialist coverage in remote areas and inconsistent reimbursement limit advanced therapy uptake. Rising medical tourism and government efforts to strengthen specialty healthcare services present opportunities for market expansion, especially as diagnostic technologies become more widely available.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% of the porokeratosis market, constrained by limited dermatology services and delayed diagnosis of rare skin disorders. Wealthier GCC nations, led by Saudi Arabia and the UAE, contribute most revenue due to higher adoption of advanced dermatology treatments and investment in specialty clinics. In contrast, many African regions experience low awareness, restricted treatment availability, and reliance on basic topical therapies. Expanding healthcare modernization programs and tele-dermatology adoption are expected to gradually improve diagnosis and treatment access across the region.
Market Segmentations:
By Type:
- Chilled
- Frozen
By Packaging:
- Store Wrap
- Modified Atmosphere Packaging
By Application:
- Household
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Porokeratosis Market features diverse participation, with companies such as Sysco Corporation, Marfrig Global Foods S.A., WH Group Limited, Cargill, Incorporated, BRF S.A. (Sadia), Tyson Foods, Inc., Clemens Food Group, JBS S.A., Hormel Foods Corporation, and Smithfield Foods, Inc. mentioned only as reference in the opening line. the Porokeratosis Market is characterized by a concentrated group of dermatology-focused pharmaceutical companies, biotechnology firms, and medical device manufacturers investing in advanced therapeutic solutions. Market participants compete primarily on innovation, clinical efficacy, and the ability to deliver targeted treatments that address the chronic nature and recurrence challenges of porokeratosis. Companies emphasize developing novel topical formulations, improved photodynamic therapy systems, and minimally invasive laser technologies to enhance patient outcomes. Strategic collaborations with research institutions, expansion of clinical trial pipelines, and the integration of digital diagnostic tools further strengthen competitive positioning, enabling firms to capture emerging opportunities in precision dermatology.
Key Player Analysis
- Sysco Corporation
- Marfrig Global Foods S.A.
- WH Group Limited
- Cargill, Incorporated
- BRF S.A. (Sadia)
- Tyson Foods, Inc.
- Clemens Food Group
- JBS S.A.
- Hormel Foods Corporation
- Smithfield Foods, Inc.
Recent Developments
- In April 2025, Olymel launched a new line of pork products in Quebec grocery stores, emphasizing convenience and quality with a focus on upscale home cooking. The products include new cuts like Pork T-bone, Chimichurri pork flank steak, Hotel cut pork chops, Pork capicola steak, and Greek-style pork sirloin skewers.
- In March 2025, Prairie Fresh expanded its product line with new ground pork chubs, including both Prairie Fresh Ground Pork and Prairie Fresh Pork Sausage, to meet increased consumer demand for convenient and versatile pork options for everyday meals.
- In March 2025, Creta Farm introduced pork from animals fed exclusively with olive oil and olive oil extract. This feeding method produces meat with higher Omega-3 and lower Omega-6 fatty acid content.
- In February 2025, OSI Group acquired the UK-based Karnova Food Group from private equity firm Endless LLP to expand its global operations, particularly in Europe. This acquisition strengthens OSI's capabilities in the sourcing, processing, and distribution of pork products, integrating Karnova's operations, which were formed in 2024 from Yorkshire Premier Meat and Smithfield Murray, into OSI's business
Report Coverage
The research report offers an in-depth analysis based on Type, Packaging, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as diagnostic awareness and early detection of porokeratosis improve worldwide.
- Precision dermatology will expand, with genetic profiling and biomarker-based approaches guiding personalized treatment plans.
- Advanced topical formulations and combination therapies will gain higher adoption due to improved efficacy and patient convenience.
- Photodynamic therapy and next-generation laser technologies will evolve, offering safer and more targeted clinical outcomes.
- Digital dermatology tools, including AI-driven lesion analysis, will enhance remote monitoring and treatment optimization.
- Research funding for rare skin disorders will increase, accelerating development of disease-modifying therapies.
- Pharmaceutical pipelines will expand with more immunomodulators and keratinization-targeting candidates entering clinical trials.
- Reimbursement support for advanced dermatology procedures will improve in developed markets, boosting treatment uptake.
- Healthcare modernization in emerging regions will enhance access to specialized dermatology services.
- Collaborations between clinicians, researchers, and industry partners will strengthen innovation and standardize care pathways.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Prevalence of Genetic and Immunologic Disorders
The increasing incidence of genetic mutations affecting keratinization and a rising population of immunocompromised individuals, such as organ transplant recipients, are expanding the patient pool for porokeratosis. Enhanced diagnostic awareness and improved screening are driving demand for targeted therapies.
Advancements in Dermatology and Targeted Treatment Modalities
Technological progress in photodynamic therapy, laser-based interventions, and novel topical formulations is accelerating clinical adoption of advanced treatments. These innovations offer improved efficacy and convenience, supporting greater uptake among clinicians and patients.
Increasing Focus on Rare Disease Research and Funding Support
Government and private funding for rare dermatological disorders is boosting research, clinical trials, and collaborative programs. This financial support encourages pharmaceutical investment in niche dermatology portfolios and accelerates the development of new therapies.
Growing Adoption of Precision and Personalized Dermatology
The use of molecular diagnostics, AI-based dermoscopy, and genetic profiling is enabling more personalized treatment plans for porokeratosis. This trend is fostering the development and adoption of targeted therapies that improve patient outcomes and reduce recurrence rates.
Expanding Tele-Dermatology and Digital Monitoring Solutions
The rapid integration of tele-dermatology platforms and AI-driven skin analytics is improving remote diagnosis and long-term monitoring of porokeratosis. These digital tools enhance early detection, treatment optimization, and patient compliance, especially in underserved regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Porokeratosis Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Porokeratosis Market projected to grow between 2025 and 2032?
Which is the leading market for Porokeratosis?
What are the key drivers for the growth of the Porokeratosis market?
Who are the leading companies in the Porokeratosis Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Chilled
- 1.2.2 Frozen
- 1.3 By Packaging
- 1.3.1 Store Wrap
- 1.3.2 Modified Atmosphere Packaging
- 1.3.3 Vacuum Packaging
- 1.3.4 Shrink Bags
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Household
- 1.4.2 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.11 billion → 2032: USD 3.35 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Porokeratosis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Porokeratosis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Porokeratosis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Porokeratosis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Porokeratosis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Porokeratosis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Porokeratosis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Porokeratosis Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.11 billion → 2032: USD 3.35 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Porokeratosis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Chilled
- 12.3.7.2 Frozen
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Store Wrap
- 12.4.7.2 Modified Atmosphere Packaging
- 12.4.7.3 Vacuum Packaging
- 12.4.7.4 Shrink Bags
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Household
- 12.5.7.2 Commercial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Porokeratosis End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Porokeratosis Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Porokeratosis Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Porokeratosis Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Leo Pharma
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Galderma
- 18.4 Palvella Therapeutics
- 18.5 Sun Pharmaceutical Industries
- 18.6 Novartis
- 18.7 Pfizer
- 18.8 AbbVie
- 18.9 Almirall
- 18.10 Cynosure (a division of Hologic)
- 18.11 Cutera
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

