
Market Overview
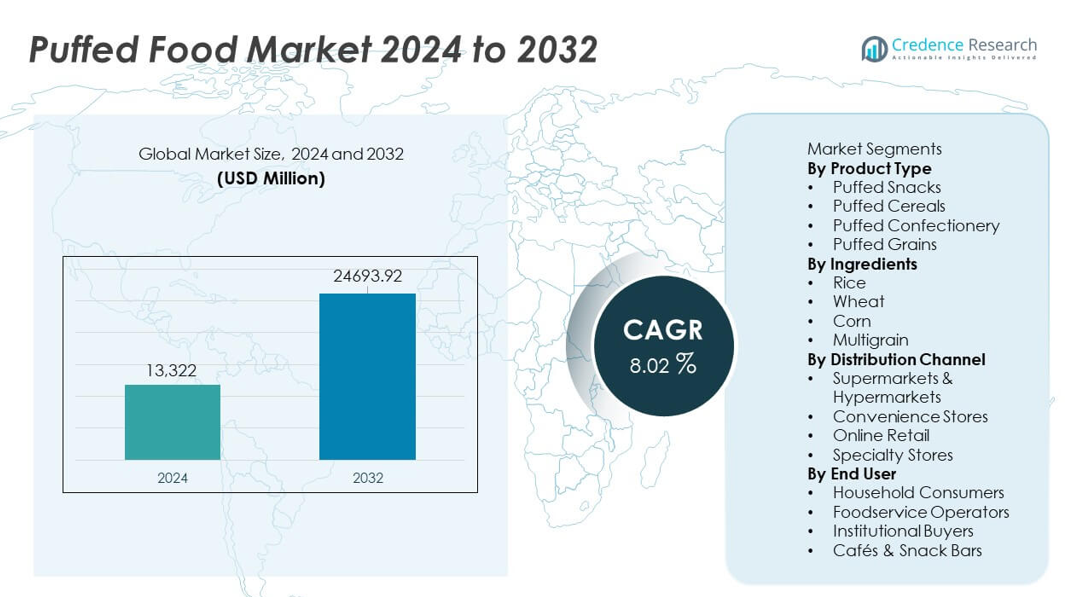
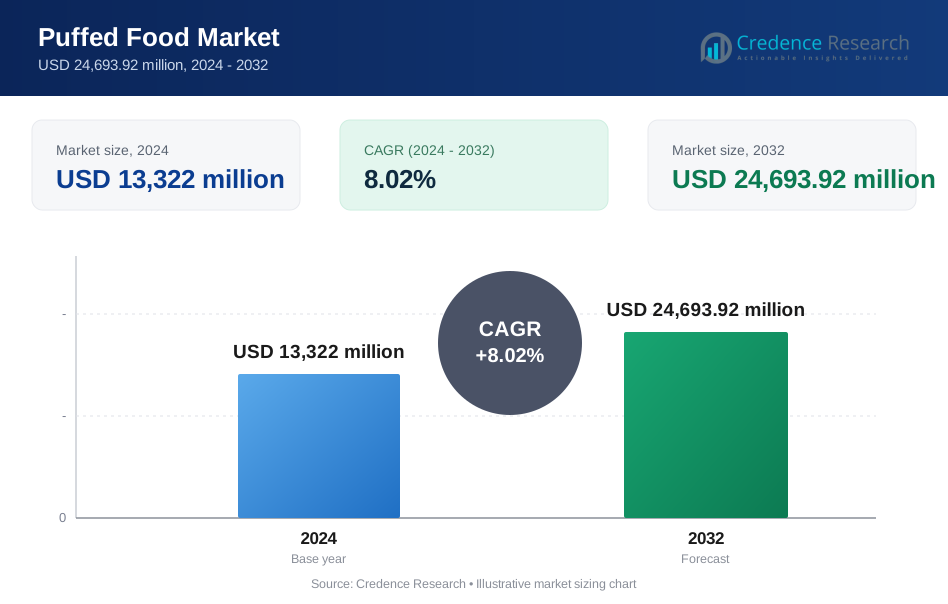
The Puffed Food Market was valued at USD 13,322 million in 2024 and is projected to reach USD 24,693.92 million by 2032, growing at a CAGR of 8.02% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Puffed Food Market Size 2024 | USD 13,322 million |
| Puffed Food Market, CAGR | 8.02% |
| Puffed Food Market Size 2032 | USD 24,693.92 million |
Top players in the Puffed Food market include Kellogg Company, General Mills Inc., PepsiCo (Frito-Lay), Nestlé S.A., Conagra Brands Inc., Ricegrowers Limited (SunRice), Arcor Group, Bagrry’s India Ltd., The Quaker Oats Company, and WEETABIX Limited. These companies lead through strong global distribution, continuous flavor innovation, and expansion of healthier, clean-label puffed products. Asia Pacific remains the dominant region with a 34% market share, driven by rising urban consumption, affordable product lines, and strong retail growth. North America follows with a 32% share, supported by high demand for nutritious, low-calorie snacks and strong brand presence across supermarkets and online channels.
Market Insights
- The Puffed Food market reached USD 13,322 million in 2024 and will grow at a CAGR of 8.02% through 2032, supported by rising global demand for light and convenient snacks.
- Health-focused consumers drive strong adoption of puffed snacks, with the product type segment led by puffed snacks holding a 42% share, supported by clean-label and low-calorie preferences.
- Innovation in flavors, multigrain blends, and fortified ingredients shapes key market trends, while leading players expand premium and plant-based ranges to strengthen competitiveness.
- Cost volatility in rice, corn, and wheat and intense competition from private-label brands restrain growth, especially in price-sensitive regions.
- Asia Pacific leads regional demand with a 34% share, followed by North America at 32% and Europe at 28%, driven by strong retail networks and rising interest in healthier puffed food options.
Market Segmentation Analysis:
By Product Type
Puffed snacks lead this segment with a 42% share, driven by rising demand for ready-to-eat products and wider flavor innovation. Consumers prefer light, low-oil snacks, which pushes brands to expand healthier formulations. Puffed cereals gain support from busy households seeking quick breakfast options with added nutrients. Puffed confectionery and puffed grains show moderate traction due to niche use in bakery and snack mixes. The focus on clean-label and fortified snacks supports long-term growth across all product types.
- For instance, Kellogg Company has implemented various energy-saving measures, including the use of advanced heat-recovery units. In 2019, the company reduced greenhouse gas emissions across its manufacturing sites by more than 20 percent, surpassing its original goal.
By Ingredients
Rice-based puffed products dominate the ingredients segment with a 38% share, supported by their use in gluten-free and low-fat snacks. Rice enables light texture and high digestibility, which attracts health-focused buyers. Wheat and corn remain widely used due to strong supply chains and established applications in snack formats. Multigrain options grow as brands blend oats, barley, and millet to raise fiber and protein content. The push toward nutritious and natural ingredients strengthens adoption across all sub-segments.
- For instance, Frito-Lay North America, a division of PepsiCo, introduced Sun Chips multigrain snacks, which use a blend of corn, oats, and wheat to offer a good source of whole grains and are made with sunflower oil, appealing to consumers seeking healthier options.
By Distribution Channel
Supermarkets and hypermarkets hold the dominant position with a 46% share, supported by wide product visibility and strong consumer footfall. These stores offer large assortments, allowing brands to promote new puffed snacks and cereals effectively. Convenience stores maintain steady demand through impulse purchases and smaller pack formats. Online retail expands due to bulk ordering, digital promotions, and home delivery advantages. Specialty stores attract buyers seeking organic or premium puffed products, further strengthening channel diversity.
Key Growth Drivers
Rising Demand for Healthy and Low-Calorie Snacks
Health-focused consumers drive strong adoption of puffed foods as they seek low-calorie, baked, and oil-free snack options. Manufacturers respond with clean-label, gluten-free, and fortified product lines that support better nutrition without compromising taste. Growing awareness of digestive health and controlled calorie intake increases interest in puffed grains, multigrain snacks, and high-fiber cereals. Brands leverage natural ingredients and simple processing methods, which strengthen consumer trust and expand category acceptance. This shift toward mindful snacking continues to boost market penetration across retail and online channels.
- For instance, Nestlé upgraded its cereal line by deploying a hot-air puffing module, which reduced oil use and cut product density for lighter texture. The system also fortified each serving with fiber using a stable chicory-root extract.
Expansion of Convenient and Ready-to-Eat Food Consumption
Urban lifestyles, busy schedules, and rising workforce participation fuel demand for convenient puffed foods that offer quick consumption and portability. Consumers prefer puffed snacks and cereals due to their long shelf life, lightweight packaging, and ease of storage. Foodservice operators add puffed ingredients in meals and dessert applications to enhance texture and improve menu variety. This convenience-driven shift encourages manufacturers to introduce single-serve packs and value-added flavor options. The broad appeal supports consistent growth across supermarkets, convenience stores, and digital retail platforms.
- For instance, General Mills improved its cereal production by developing and installing a continuous puffing gun process to increase output, which produces a more uniform product with less burned pieces compared to the previous batch method.
Product Innovation and Flavor Diversification
Continuous innovation shapes market expansion as brands develop new flavors, textures, and ingredient blends that appeal to diverse taste preferences. Companies experiment with savory, spicy, and ethnic flavor profiles to attract younger consumers seeking novel snacking experiences. Multigrain and protein-enhanced puffed variants gain momentum as consumers explore functional foods. Advanced extrusion technology improves product consistency and volume, enabling large-scale production of high-quality puffed items. This innovation-driven environment strengthens brand competitiveness and boosts category growth across global markets.
Key Trends & Opportunities
Growth of Clean-Label and Plant-Based Formulations
Clean-label and plant-based puffed foods represent a major trend as consumers shift toward natural ingredients and minimal processing. Brands introduce plant-derived proteins, whole grains, and allergen-friendly snacks to meet rising dietary expectations. Demand increases for products free from artificial colors, preservatives, and trans fats. This trend encourages manufacturers to reformulate existing lines and launch organic or non-GMO puffed items. Strong preference for sustainable and transparent labeling offers long-term opportunities, especially in health-conscious markets and premium retail channels.
- For instance, PepsiCo uses extrusion technology to produce plant-based puffed snacks using ingredients like lentil and chickpea bases, and this process can be optimized for nutrient retention.
Rising Online Retail Adoption and Direct-to-Consumer Models
Digital commerce enhances access to puffed food products through subscription packs, curated snack boxes, and personalized recommendations. Consumers benefit from wider product variety and competitive pricing online. Brands leverage e-commerce analytics to introduce targeted promotions and limited-edition flavors. Small manufacturers gain visibility through online marketplaces, improving reach without major retail investment. This trend expands opportunities for niche categories such as gourmet puffed snacks, organic cereals, and multigrain blends. The growth of home delivery further accelerates demand across developed and emerging regions.
- For instance, Weetabix Limited improved its operational efficiency through a business-led digital transformation program, leveraging a new enterprise resource planning (ERP) system.
Key Challenges
Fluctuating Raw Material Costs
Volatile prices of rice, corn, wheat, and multigrain ingredients create cost pressures for manufacturers. Weather disruptions, supply chain delays, and global commodity shifts affect stability in sourcing essential grains used in puffed products. These fluctuations raise production costs and push companies to adjust pricing, which may reduce consumer affordability. Manufacturers adopt long-term contracts, diversified sourcing, and improved processing efficiency to control cost swings. However, persistent instability remains a challenge for maintaining consistent margins and competitive pricing strategies.
Intense Competition and Product Saturation
The market faces strong competition as numerous global and regional brands offer similar puffed snacks, cereals, and grain-based products. High product saturation limits differentiation and increases promotional spending. Smaller players struggle to compete with established brands that possess stronger distribution networks and higher marketing budgets. Companies must innovate with unique flavors, healthier ingredients, and value-added packaging to maintain visibility. The challenge intensifies as private-label products gain traction, offering lower-priced alternatives that attract cost-sensitive consumers.
Regional Analysis
North America
North America holds a 32% market share, supported by strong demand for convenient and healthier snacking options. Consumers favor puffed snacks and cereals with clean-label ingredients, low fat, and added nutrients. Major brands introduce innovative flavors and protein-enhanced variants to meet evolving dietary habits. Retail expansion and strong online delivery networks improve access to premium and organic puffed products. Busy lifestyles and high consumer spending strengthen category penetration across supermarkets and convenience stores. Growing interest in plant-based and multigrain formulations continues to drive regional market growth.
Europe
Europe accounts for a 28% market share, driven by rising preference for natural, sustainable, and low-calorie puffed snacks. Consumers adopt puffed grains and cereals as part of balanced diets that focus on fiber intake and reduced additives. Strict food regulations encourage manufacturers to use clean-label ingredients and transparent sourcing. Growth accelerates through strong retail networks and increasing demand for organic puffed products in Western Europe. Flavor innovation and gluten-free variants attract health-conscious buyers. Expanding private-label offerings improve affordability and widen consumer reach across the region.
Asia Pacific
Asia Pacific leads the global market with a 34% market share, fueled by rapid urbanization, expanding middle-class consumption, and strong demand for ready-to-eat snacks. Traditional grain-based puffed foods support high regional acceptance, while modern flavored variants attract younger consumers. Manufacturers scale production with advanced extrusion technology to meet rising demand across India, China, and Southeast Asia. Growing interest in affordable, portable, and nutrient-enhanced puffed items strengthens distribution through supermarkets and convenience stores. E-commerce growth boosts direct-to-consumer sales, further accelerating regional expansion.
Latin America
Latin America holds a 4% market share, supported by rising interest in convenient snack formats and expanding retail penetration. Consumers adopt puffed snacks due to affordability, diverse flavors, and suitability for on-the-go consumption. Local brands introduce corn and multigrain-based puffed items to match regional taste preferences. Growth improves as supermarkets and neighborhood stores increase shelf space for packaged snacks. Health trends progress slowly, yet demand for low-oil and baked alternatives is rising. Digital retail platforms broaden access, helping international brands gain visibility across key markets.
Middle East & Africa
The Middle East & Africa region captures a 2% market share, driven by gradual adoption of packaged snacks and increasing exposure to global food trends. Urban consumers show growing interest in puffed cereals and light snacks that offer convenience and longer shelf life. Retail expansion and rising supermarket chains improve access to branded puffed products. Imported goods dominate, but regional manufacturers expand production to meet cost-sensitive demand. Health awareness is increasing, supporting uptake of low-fat and multigrain puffed variants. Economic growth and improving distribution networks contribute to steady market development.
Market Segmentations:
By Product Type
- Puffed Snacks
- Puffed Cereals
- Puffed Confectionery
- Puffed Grains
By Ingredients
- Rice
- Wheat
- Corn
- Multigrain
By Distribution Channel
- Supermarkets & Hypermarkets
- Convenience Stores
- Online Retail
- Specialty Stores
By End User
- Household Consumers
- Foodservice Operators
- Institutional Buyers
- Cafés & Snack Bars
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive andscape
The competitive landscape features leading players such as Kellogg Company, General Mills Inc., PepsiCo (Frito-Lay), Nestlé S.A., Conagra Brands Inc., Ricegrowers Limited (SunRice), Arcor Group, Bagrry’s India Ltd., The Quaker Oats Company, and WEETABIX Limited. These companies strengthen their market position through continuous product innovation, flavor diversification, and expansion of healthier puffed snack and cereal lines. Major brands invest in advanced extrusion technology to improve texture, volume, and nutrient retention, supporting better product quality. Strategic partnerships with retailers enhance shelf visibility, while e-commerce channels expand consumer reach. Companies also focus on clean-label, gluten-free, and plant-based offerings to align with rising health trends. Private-label products intensify competition by offering lower-cost alternatives, pushing established players to prioritize branding, packaging upgrades, and targeted marketing campaigns. Regional manufacturers gain traction by introducing affordable, locally flavored puffed products, further shaping the competitive dynamics of the global market.
Key Player Analysis
- Kellogg Company
- General Mills Inc.
- PepsiCo (Frito-Lay)
- Nestlé S.A.
- Conagra Brands Inc.
- Ricegrowers Limited (SunRice)
- Arcor Group
- Bagrry’s India Ltd.
- The Quaker Oats Company
- WEETABIX Limited
Recent Developments
- In May 2025, General Mills, Inc. pushed a seasonal line-up that included salty snacks and sweet treats along with their cereals. The update included new snack-type items.
- In March 2025, Nestlé S.A. (via Nestlé India) introduced a new version of a cereal product under the “CEREGROW” brand that contains no refined sugar - showing a move toward healthier breakfast/snack offerings
Report Coverage
The research report offers an in-depth analysis based on Product Type, Ingredients, Distribution Channel, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for healthier, low-calorie puffed snacks will rise as consumers shift toward mindful eating.
- Expansion of gluten-free, multigrain, and plant-based puffed products will strengthen product diversity.
- Flavor innovation will accelerate, with brands introducing regional, spicy, and protein-rich variants.
- Online retail channels will grow rapidly as consumers prefer doorstep delivery and wider product choice.
- Advanced extrusion technology will improve texture, volume, and nutrient retention in puffed foods.
- Clean-label and natural ingredient formulations will gain stronger adoption across global markets.
- Premium puffed snacks will gain traction as buyers seek high-quality, value-added offerings.
- Local manufacturers will expand presence in emerging markets through affordable and culturally aligned flavors.
- Sustainability initiatives will push brands to adopt eco-friendly packaging and transparent sourcing.
- Private-label competition will intensify, encouraging brands to invest more in branding, innovation, and targeted marketing.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Puffed Food market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Puffed Food market projected to grow between 2025 and 2032?
Which health attributes segment will post the highest CAGR in the forecast period?
Which Puffed Food market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Puffed Food market?
Who are the leading companies in the Puffed Food market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Puffed Food Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Puffed Food Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 13,322 million → 2032: USD 24,693.92 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Puffed Food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Puffed Food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Puffed Food Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Puffed Food Market Drivers
- 3.3 Puffed Food Market Restraints & Challenges
- 3.4 Puffed Food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Puffed Food Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Puffed Food Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Puffed Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Puffed Food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Puffed Food Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Puffed Food. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Puffed Food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Puffed Food Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Puffed Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Puffed Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Puffed Food
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Puffed Food Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Puffed Food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Puffed Food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Puffed Food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Puffed Food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Puffed Food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Puffed Food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Puffed Food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
