
Market Overview:
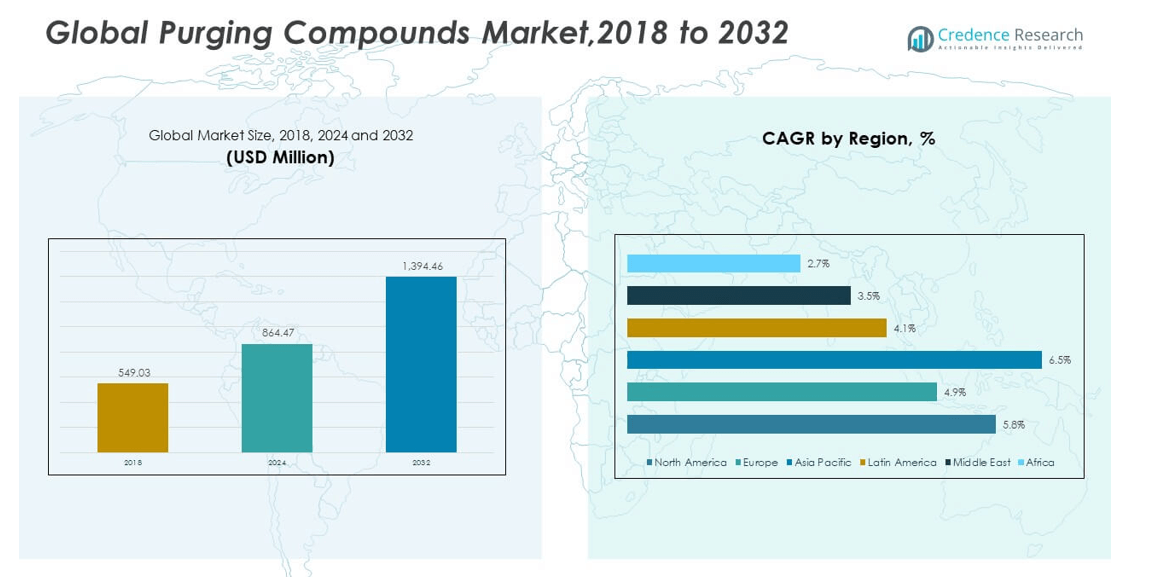
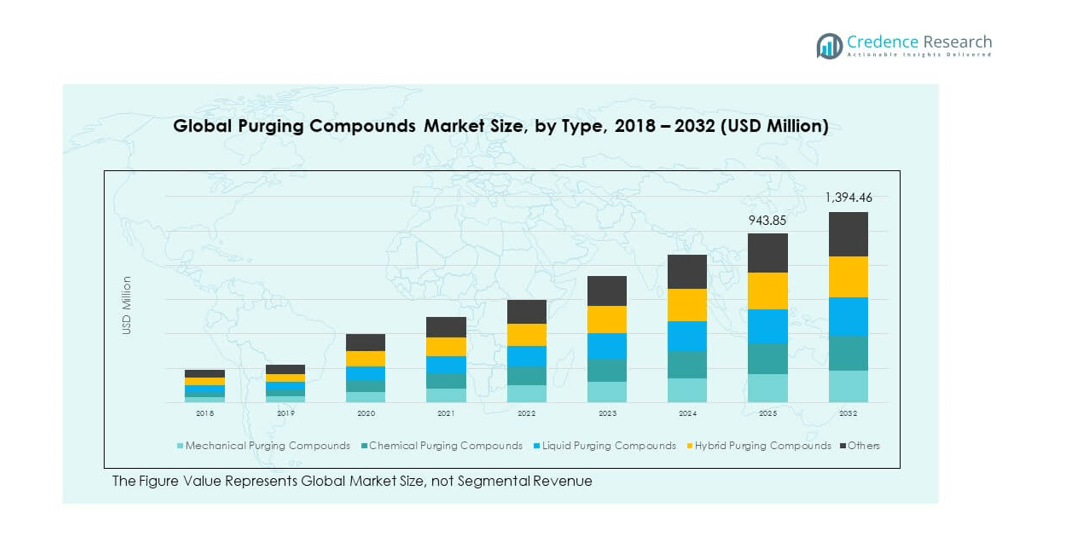
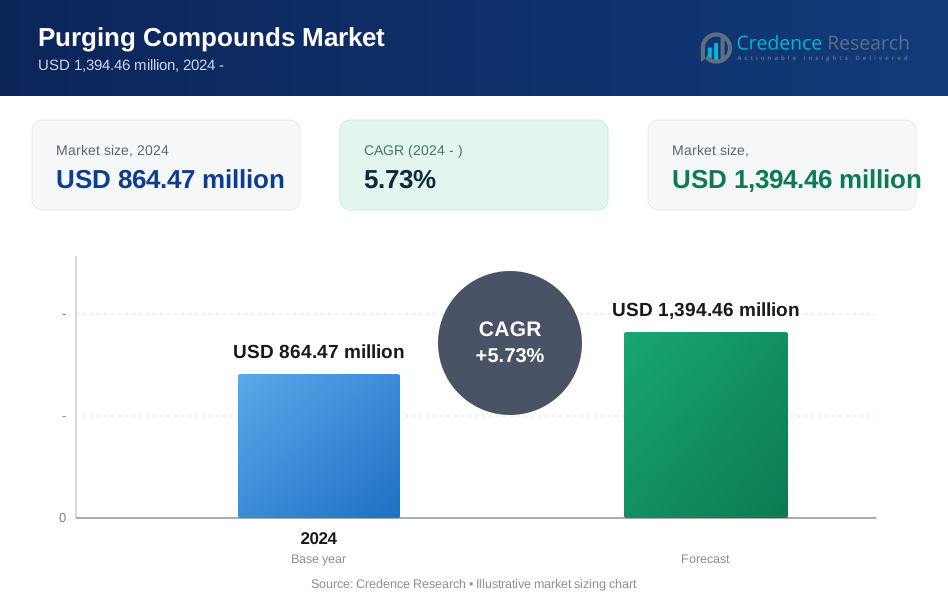
The Global Purging Compounds Market size was valued at USD 549.03 million in 2018 to USD 864.47 million in 2024 and is anticipated to reach USD 1,394.46 million by 2032, at a CAGR of 5.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Purging Compounds Market Size 2024 | USD 864.47 million |
| Purging Compounds Market, CAGR | 5.73% |
| Purging Compounds Market Size 2032 | USD 1,394.46 million |
The market grows due to rising demand for efficient plastic processing operations. Manufacturers focus on reducing machine downtime and scrap rates. Purging compounds support faster resin and color changeovers. This benefit improves overall production efficiency. Growing use of engineering plastics increases cleaning complexity. Processors prefer chemical and mechanical purging solutions for consistency. Sustainability goals push firms to cut waste and energy use. Recycled resin processing also raises contamination risks. Purging compounds help maintain quality during frequent material transitions. These factors sustain steady demand across polymer processing industries.
Asia Pacific leads the market due to strong plastics manufacturing growth. China, India, and Southeast Asia expand injection molding and extrusion capacity. Rising packaging, automotive, and consumer goods output supports demand. North America remains a mature market with focus on high-performance purging solutions. The United States drives adoption through advanced polymer processing. Europe shows steady growth supported by strict quality standards. Germany and Italy lead machinery-intensive applications. Latin America and the Middle East emerge gradually. Industrial expansion and local plastics production support future uptake.
Market Insights:
- The market expanded from USD 549.03 million in 2018 to USD 864.47 million in 2024 and is projected to reach USD 1,394.46 million by 2032, reflecting a 5.73% CAGR driven by higher purge frequency in plastics processing.
- Asia Pacific (44%), Europe (26%), and North America (21%) lead regional shares due to large plastics manufacturing bases, strong packaging demand, and strict quality standards that favor efficient changeovers.
- Asia Pacific is the fastest-growing region with a 44% share, supported by rapid capacity expansion in China and India, rising consumer goods output, and frequent resin transitions.
- By type, mechanical purging compounds (~40%) and chemical purging compounds (~30%) dominate usage, as processors balance routine maintenance with deep cleaning needs.
- Liquid purging compounds (~20%) gain traction for faster coverage and shorter cycles, while hybrid and others (~10%) serve complex, multi-resin environments.
Market Drivers:
Rising Need For Faster And Cleaner Polymer Processing Changeovers
The Global Purging Compounds Market benefits from frequent resin and color changes. Manufacturers seek shorter transition cycles between production runs. Purging compounds reduce residual polymer build-up inside machines. This improves product quality across batches. It lowers scrap generation during start-up phases. Equipment uptime improves through effective barrel and screw cleaning. Processors value predictable cleaning outcomes. Demand grows across injection molding and extrusion lines.
- For instance, Asahi Kasei’s Asaclean grades report purge time reductions of up to 50% and faster color changeovers in injection molding applications, supporting higher line availability.
Focus On Cost Control And Waste Reduction In Plastics Manufacturing
The Global Purging Compounds Market gains support from strict cost control goals. Plastic processors aim to reduce raw material losses. Purging compounds limit off-spec production during changeovers. It helps conserve high-cost engineering resins. Lower scrap rates support margin stability. Manufacturers prefer repeatable cleaning performance. Energy use drops due to shorter purge cycles. Operational efficiency drives adoption across facilities.
- For instance, Chem-Trend’s Ultra Purge™ compounds have been cited to cut scrap material by up to 30% during resin transitions, improving cost efficiency across extrusion operations.
Growing Use Of Engineering And Specialty Polymers In Production
The Global Purging Compounds Market advances with complex polymer usage. Engineering plastics leave stubborn residues in processing equipment. Standard purging methods fail to remove deposits fully. Specialized compounds improve cleaning depth and consistency. It protects screw geometry and barrel surfaces. Quality standards rise in automotive and electronics plastics. Processors invest in reliable cleaning solutions. This trend sustains long-term demand growth.
Expansion Of High-Volume Plastic Processing Industries Worldwide
The Global Purging Compounds Market grows with plastics industry expansion. Packaging production scales across food and consumer goods. Automotive molding volumes remain strong in many regions. Medical device manufacturing demands clean processing environments. Purging compounds support frequent material changes. It ensures compliance with quality requirements. High-output lines value minimal downtime. Industrial growth supports steady market demand.
Market Trends:
Shift Toward Ready-To-Use And Customized Purging Formulations
The Global Purging Compounds Market shows preference for ready-to-use solutions. Processors avoid manual blending and preparation steps. Customized grades match specific resin types and temperatures. It simplifies operator training across shifts. Consistent results improve confidence in purge cycles. Suppliers offer application-specific product portfolios. This trend supports premium product positioning. Ease of use influences purchasing decisions.
- For instance, some purging compounds offer resin-specific grades that manufacturers report can reduce purging costs by over 60% and significantly accelerate changeovers, supporting standardized plant operations.
Increasing Preference For Low-Odor And Low-Residue Purging Solutions
The Global Purging Compounds Market reflects demand for cleaner shop floors. Operators favor low-odor compounds for better work conditions. Reduced smoke improves visibility near machines. It supports safety and compliance standards. Low-residue formulas limit secondary cleaning needs. Processors value smooth restart after purging cycles. Production stability improves with cleaner systems. Comfort and safety drive formulation innovation.
Integration Of Purging Solutions Into Preventive Maintenance Practices
The Global Purging Compounds Market aligns with preventive maintenance programs. Manufacturers schedule purging during planned downtime. This approach prevents severe build-up inside barrels. It extends equipment service life. Maintenance teams track purge cycles systematically. Predictive upkeep reduces unexpected breakdowns. Structured cleaning routines gain traction. Purging becomes part of standard operating procedures.
Growing Adoption Of Purging Compounds In Recycled Plastic Processing
The Global Purging Compounds Market adapts to recycled resin usage. Recycled polymers carry higher contamination risks. Frequent cleaning protects product consistency. It supports stable melt flow and color control. Processors handle mixed resin streams more confidently. Purging compounds limit cross-contamination effects. Recycling growth boosts specialized product demand. Circular economy goals influence market evolution.
Market Challenges Analysis:
Limited Awareness And Improper Usage Across Small Processing Units
The Global Purging Compounds Market faces awareness gaps in small plants. Many operators rely on traditional purge methods. Improper usage reduces performance benefits. It leads to inconsistent cleaning results. Training gaps affect purge cycle efficiency. Cost sensitivity limits product trials. Smaller processors delay adoption decisions. Education remains a key market challenge.
Performance Variability Across Different Machine And Resin Combinations
The Global Purging Compounds Market encounters compatibility concerns. One compound rarely suits all processing conditions. Incorrect grade selection affects cleaning depth. It may leave residue inside equipment. Trial costs discourage experimentation. Processors expect predictable outcomes. Suppliers must guide application choices. Technical support demands remain high.
Market Opportunities:
Product Innovation Focused On Sustainable And Low-Waste Processing Needs
The Global Purging Compounds Market holds scope for sustainable solutions. Manufacturers seek reduced purge material consumption. Efficient formulations lower disposal volumes. It aligns with waste reduction targets. Bio-based and recyclable compounds gain attention. Regulatory pressure supports cleaner formulations. Innovation creates differentiation opportunities. Sustainability trends shape future demand.
Growth Potential Across Emerging Manufacturing Regions And Industries
The Global Purging Compounds Market finds opportunity in emerging economies. Industrial expansion boosts plastic processing capacity. Local manufacturers upgrade production quality standards. It raises demand for professional cleaning solutions. Packaging and consumer goods output increases rapidly. Automotive localization supports molding growth. Suppliers expand regional distribution networks. Emerging markets offer long-term growth potential.
Market Segmentation Analysis:
By Type
The Global Purging Compounds Market shows clear differentiation across product types. Mechanical purging compounds see wide use due to simple application and low residue risk. It suits routine maintenance in standard polymer runs. Chemical purging compounds support deep cleaning for high-temperature and engineered resins. Liquid purging compounds gain attention for uniform dispersion and faster coverage inside barrels. It supports short purge cycles and reduced material loss. Hybrid purging compounds combine mechanical and chemical action. This segment serves complex processing environments with frequent material changes.
- For instance, Chem-Trend reports hybrid formulations that remove carbonized deposits at processing temperatures above 300°C, serving complex multi-resin environments.
By Process
The Global Purging Compounds Market reflects varied demand across processing methods. Extrusion operations rely on purging to maintain steady melt flow and surface finish. It helps manage color transitions in continuous lines. Injection molding drives strong demand due to frequent tool and resin changes. Blow molding applications value purging for clean parison formation and consistent wall thickness. It supports packaging quality standards. Other processes include compression and transfer molding. These segments adopt purging compounds to protect equipment performance and maintain product consistency.
- For instance, users of Asaclean in extrusion lines report stable output after purging without dismantling screws, helping protect equipment performance and product consistency.
Segmentation:
By Type- Mechanical Purging Compounds
- Chemical Purging Compounds
- Liquid Purging Compounds
- Hybrid Purging Compounds
- Extrusion
- Injection Molding
- Blow Molding
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Purging Compounds Market size was valued at USD 119.33 million in 2018 to USD 183.97 million in 2024 and is anticipated to reach USD 298.43 million by 2032, at a CAGR of 5.8 during the forecast period. The Global Purging Compounds Market maintains stable demand across the region due to advanced plastic processing infrastructure. The United States leads with strong injection molding activity. Automotive, packaging, and medical sectors drive consistent usage. It benefits from strict quality control norms and downtime reduction goals. Processors favor chemical and hybrid grades for complex polymers. Equipment modernization supports frequent purge cycles. North America accounts for about 21% market share in 2024.
Europe
The Europe Purging Compounds Market size was valued at USD 146.17 million in 2018 to USD 221.31 million in 2024 and is anticipated to reach USD 334.68 million by 2032, at a CAGR of 4.9 during the forecast period. The Global Purging Compounds Market shows steady performance across Europe. Germany, France, and Italy anchor demand through strong industrial bases. Packaging and automotive molding drive consistent consumption. It supports high standards for surface finish and color accuracy. Sustainability goals influence product preferences. Mechanical and liquid compounds remain widely used. Europe holds nearly 26% market share in 2024.
Asia Pacific
The Asia Pacific Purging Compounds Market size was valued at USD 234.01 million in 2018 to USD 382.42 million in 2024 and is anticipated to reach USD 655.41 million by 2032, at a CAGR of 6.5 during the forecast period. The Global Purging Compounds Market finds its largest regional base here. China, India, and Southeast Asia drive high-volume plastic production. Packaging and consumer goods output expands rapidly. It supports frequent resin and color changes. Cost efficiency shapes buying decisions. Local suppliers compete with global brands. Asia Pacific holds about 44% market share in 2024.
Latin America
The Latin America Purging Compounds Market size was valued at USD 25.45 million in 2018 to USD 39.56 million in 2024 and is anticipated to reach USD 56.33 million by 2032, at a CAGR of 4.1 during the forecast period. The Global Purging Compounds Market grows steadily in this region. Brazil and Mexico lead demand through packaging and household plastics. Quality improvement efforts support adoption. It aligns with gradual equipment upgrades. Cost sensitivity affects product selection. Distributor presence improves access. Latin America represents about 5% market share in 2024.
Middle East
The Middle East Purging Compounds Market size was valued at USD 15.56 million in 2018 to USD 22.42 million in 2024 and is anticipated to reach USD 30.59 million by 2032, at a CAGR of 3.5 during the forecast period. The Global Purging Compounds Market shows moderate growth in the region. UAE and Saudi Arabia lead industrial usage. Packaging and construction plastics support demand. It benefits from diversification initiatives. Import dependence shapes supply trends. Awareness of purge efficiency improves gradually. The Middle East holds nearly 3% market share in 2024.
Africa
The Africa Purging Compounds Market size was valued at USD 8.51 million in 2018 to USD 14.80 million in 2024 and is anticipated to reach USD 19.02 million by 2032, at a CAGR of 2.7 during the forecast period. The Global Purging Compounds Market remains limited across Africa. South Africa and Egypt lead regional activity. Plastic processing capacity stays modest. It supports basic packaging demand. Cost constraints slow adoption. Mechanical compounds dominate usage. Africa accounts for about 2% market share in 2024.
Key Player Analysis:
- Calsak Corporation
- Plastic Solutions, Inc.
- Neutrex, Inc.
- Perfect Colourants & Plastics Pvt. Ltd.
- Asahi Kasei Corporation
- Chem-Trend L.P.
- 3M
Competitive Analysis:
The Global Purging Compounds Market features a mix of global chemical firms and specialized niche suppliers. Competition centers on product performance, ease of use, and application support. Leading players focus on chemical, hybrid, and liquid formulations for complex polymers. It rewards suppliers that offer consistent purge efficiency across machines. Technical service and customer training strengthen long-term contracts. Regional players compete on price and local availability. Innovation targets faster cleaning cycles and low-residue performance. Strategic partnerships with processors enhance market presence. Brand reputation plays a key role in buyer selection.
Recent Developments:
- In September 2025, Asahi Kasei announced the launch of its newest innovation in the purging compounds market by starting European sales activities of the Asaclean™ R-Series. This strategic product launch represents a significant addition to the company's family of purging compounds for plastics processing equipment. The Asaclean™ R-Series consists of three distinct grades designed to optimize different processing requirements: the universal grade RU, the time-optimized RX grade, and the RE grade, which is specifically optimized for quick and efficient material changeover. The new series achieves outstanding cleaning performance while requiring significantly less rinsing material after the purging process, contributing to time-, cost-, and material-optimization in the plastics processing industry. Asahi Kasei presented this innovation at K 2025, the world's No. 1 trade fair for the plastics and rubber industry held in Düsseldorf from October 8-15, 2025.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Process. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise with frequent resin and color changeovers.
- Hybrid purging compounds will gain wider industrial acceptance.
- Recycling-driven processing will increase purge frequency.
- Low-residue formulations will attract quality-focused processors.
- Asia Pacific will remain the primary growth engine.
- Preventive maintenance adoption will support steady demand.
- Sustainability goals will shape product development.
- Distributor networks will expand in emerging regions.
- Custom formulations will strengthen supplier differentiation.
- Technical support will influence long-term contracts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Purging Compound, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Purging Compound market projected to grow between 2025 and 2032?
Which Purging Compound market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Purging Compound market?
Who are the leading companies in the Purging Compound market?
Which region commanded the largest share of the Purging Compound market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Purging Compounds Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Purging Compounds Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 864.47 million → forecast year: USD 1,394.46 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Purging Compounds Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Purging Compounds Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Purging Compounds Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Purging Compounds Market Drivers
- 3.3 Purging Compounds Market Restraints & Challenges
- 3.4 Purging Compounds Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Purging Compounds Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Purging Compounds Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Purging Compounds category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Purging Compounds Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through the forecast period
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through the forecast period
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Purging Compounds Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Purging Compounds. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Purging Compounds Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Purging Compounds Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Purging Compounds Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Purging Compounds (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Purging Compounds
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Purging Compounds Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & ) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Purging Compounds Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Purging Compounds Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Purging Compounds Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Purging Compounds Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Purging Compounds Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Purging Compounds Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Purging Compounds Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
