
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Quadriplegia Care Devices Market Size 2024 | USD 6,402.04 Million |
| Quadriplegia Care Devices Market, CAGR | 6.80% |
| Quadriplegia Care Devices Market Size 2032 | USD 11,253.52 Million |
Market Overview
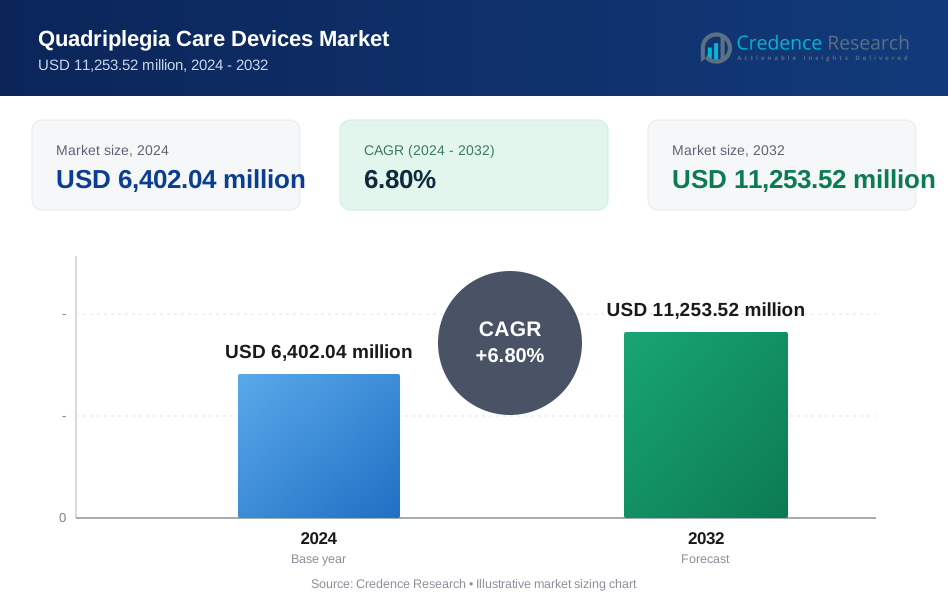
The Quadriplegia Care Devices Market size was valued at USD 4,188.03 million in 2018, increased to USD 6,402.04 million in 2024, and is anticipated to reach USD 11,253.52 million by 2032, at a CAGR of 6.80% during the forecast period.
The Quadriplegia Care Devices Market is experiencing robust growth driven by increasing prevalence of spinal cord injuries, rising awareness about advanced mobility solutions, and growing investments in healthcare infrastructure. Demand for specialized assistive technologies, such as motorized wheelchairs and patient transfer systems, continues to rise as the aging population expands and post-accident rehabilitation needs intensify. Technological advancements are enabling the development of innovative devices that enhance patient mobility and independence, supporting market expansion. Trends indicate a shift toward integration of smart features, including connectivity and remote monitoring, which improve user convenience and safety. The market also benefits from supportive government initiatives and reimbursement policies that make these devices more accessible. However, high costs and limited access in low-income regions remain key challenges. Overall, ongoing innovation, heightened patient needs, and supportive policy frameworks are shaping a dynamic landscape for the quadriplegia care devices market.
The Quadriplegia Care Devices Market demonstrates strong geographical diversity, with North America, Europe, and Asia Pacific serving as the primary centers of demand and innovation. North America benefits from a well-developed healthcare infrastructure and rapid adoption of advanced assistive technologies, while Europe is characterized by robust government support and an expanding elderly population requiring specialized care solutions. Asia Pacific is emerging as a key growth region, supported by increasing healthcare investments and rising patient awareness in countries such as China, Japan, and India. Leading companies such as ReWalk Robotics, Ekso Bionics, and Medtronic Plc play pivotal roles in shaping the market landscape. These key players focus on continuous innovation, expanding their product portfolios with advanced mobility and rehabilitation devices to address evolving patient needs and improve quality of life for individuals living with quadriplegia across diverse regions.
Market Insights
- The Quadriplegia Care Devices Market reached USD 6,402.04 million in 2024 and is projected to achieve USD 11,253.52 million by 2032, reflecting a CAGR of 6.80% during the forecast period.
- Demand for quadriplegia care devices is increasing due to the rising prevalence of spinal cord injuries and neurological disorders worldwide.
- Integration of smart technologies, such as IoT connectivity and remote monitoring, is a key trend that enhances user convenience and safety.
- Leading companies in this market include ReWalk Robotics, Ekso Bionics, and Medtronic Plc, all investing in innovative product development and strategic partnerships to expand global reach.
- High costs of advanced care devices and inconsistent reimbursement policies in several countries restrict market accessibility, especially for lower-income populations.
- North America leads the market in terms of technological advancement and healthcare infrastructure, while Asia Pacific is emerging rapidly due to increasing healthcare investments and a growing patient population.
- The market continues to benefit from supportive government initiatives and evolving patient preferences for home-based rehabilitation, creating new opportunities for manufacturers and healthcare providers.
Market Drivers
Rising Prevalence of Spinal Cord Injuries and Neurological Disorders Increases Device Demand
The rising prevalence of spinal cord injuries and neurological disorders remains a key driver for the Quadriplegia Care Devices Market. Global rates of traumatic accidents, sports injuries, and chronic conditions continue to climb, contributing to a larger population in need of advanced care solutions. Healthcare providers are seeking effective assistive devices to address patient mobility and daily care needs. These factors lead to consistent demand growth across hospitals, rehabilitation centers, and home care settings. Awareness campaigns and early diagnosis help identify cases faster, prompting earlier intervention with specialized equipment. The market responds with an expanding product portfolio to meet varying degrees of patient dependency.
- For instance, Ekso Bionics has deployed its exoskeleton systems in more than 270 rehabilitation centers worldwide, supporting intensive gait training for individuals recovering from spinal cord injuries.
Technological Advancements Drive Innovation in Assistive Devices
Technological innovation plays a pivotal role in shaping the Quadriplegia Care Devices Market. Manufacturers are focusing on developing user-friendly, customizable devices equipped with advanced features such as automated controls, IoT integration, and remote monitoring capabilities. These advancements improve patient comfort, mobility, and overall quality of life. Companies invest heavily in research and development to create devices that are lightweight, durable, and easy to operate. It benefits healthcare professionals by simplifying patient handling and reducing the risk of injury. Enhanced safety features and interoperability with other healthcare technologies further expand the adoption rate.
- For instance, Medtronic’s Intellis™ Spinal Cord Stimulator system allows for 16 independent stimulation programs and has supported over 70,000 global implants since launch.
Supportive Government Initiatives and Favorable Reimbursement Policies Expand Access
Government initiatives and favorable reimbursement policies provide critical support for the Quadriplegia Care Devices Market. Public health agencies recognize the importance of accessible care for people with severe mobility challenges. Financial incentives, funding for assistive technology programs, and comprehensive insurance coverage help lower financial barriers for patients. Regulatory bodies streamline approval processes for innovative devices, accelerating market entry. Support from non-profit organizations and advocacy groups also drives access to quality care equipment. These factors help bridge the gap for underserved populations and sustain market momentum.
Increasing Focus on Home-Based Care and Rehabilitation Solutions Shapes Market Growth
A growing preference for home-based care and rehabilitation solutions influences the Quadriplegia Care Devices Market. Patients and families seek independence and comfort, choosing home settings over long-term hospitalization. It prompts manufacturers to design compact, portable devices tailored for domestic use. Healthcare providers implement remote monitoring and tele-rehabilitation services to support home care models. The trend reduces overall healthcare costs while improving patient satisfaction. Market players respond by expanding distribution channels and enhancing after-sales support, reinforcing the shift toward home-based quadriplegia care.
Market Trends
Growing Emphasis on Aesthetics and Ergonomic Design Enhances User Acceptance
Aesthetic appeal and ergonomic design are gaining prominence in the Quadriplegia Care Devices Market. Users seek devices that not only offer functional benefits but also blend with their personal preferences and living environments. Manufacturers prioritize lightweight materials, sleek profiles, and intuitive interfaces to increase adoption. Ergonomics play a key role in reducing fatigue and pressure-related injuries, enhancing comfort during prolonged use. Improved aesthetics contribute to reducing the social stigma often associated with medical devices. It reflects a broader movement toward user-friendly and discreet assistive technologies.
- For instance, Ottobock’s Zenit wheelchair weighs just 8.9 kg, with over 15,000 units sold globally, demonstrating high user preference for lightweight and ergonomically designed solutions.
Expansion of Personalized and Customizable Device Offerings Meets Diverse Patient Needs
Personalization and customization are becoming core strategies for manufacturers in the Quadriplegia Care Devices Market. Each patient presents unique requirements, and companies are responding by offering adjustable seating systems, adaptable controls, and modular components. 3D printing technology allows for bespoke solutions tailored to individual anatomies, improving comfort and usability. Manufacturers consult directly with patients, therapists, and caregivers to refine device features and design elements. This trend strengthens patient adherence to prescribed therapies and supports better clinical outcomes. Customization aligns with the increasing focus on patient-centered care in rehabilitation and long-term management.
- For instance, Ottobock has delivered more than 4,500 custom-contoured seating solutions using its Shape3D technology in the past year.
Integration of Smart Technologies and Remote Monitoring Transforms Patient Care
The integration of smart technologies and remote monitoring stands out as a significant trend in the Quadriplegia Care Devices Market. Device manufacturers are embedding sensors, IoT capabilities, and wireless connectivity into their products, allowing patients and caregivers to track health data in real-time. These advancements facilitate proactive care, timely intervention, and greater patient independence. Smart devices can transmit alerts to healthcare professionals and family members, improving overall safety. The trend supports data-driven decision-making, enabling continuous refinement of care protocols. It encourages the adoption of digital health platforms that enhance the overall user experience.
Sustainable Manufacturing Practices and Eco-Friendly Materials Enter the Spotlight
Sustainability is emerging as an influential trend within the Quadriplegia Care Devices Market. Companies are incorporating eco-friendly materials and implementing sustainable manufacturing processes to reduce environmental impact. Interest in recyclable components and energy-efficient production methods is increasing among market leaders. Regulatory agencies and consumers alike are showing preference for products that align with green initiatives. Adoption of environmentally responsible practices can enhance brand reputation and meet the expectations of a growing segment of environmentally conscious buyers. It signals a shift toward responsible growth and long-term market sustainability.
Market Challenges Analysis
High Cost of Advanced Devices and Limited Reimbursement Impede Widespread Adoption
The high cost of advanced devices presents a significant challenge for the Quadriplegia Care Devices Market. Many patients face financial barriers that prevent access to the latest technologies, particularly in regions with limited insurance coverage or inadequate public healthcare funding. Expensive features such as smart sensors, connectivity, and automated controls drive up the price of equipment, placing them out of reach for lower-income users. It limits adoption rates, especially in developing economies where healthcare budgets remain constrained. Inconsistent reimbursement policies further complicate matters, with some devices not covered or partially reimbursed by insurers. The financial burden on families and healthcare systems creates an uneven landscape for equitable access.
Lack of Skilled Professionals and Infrastructure Hinders Effective Utilization
A shortage of skilled professionals and inadequate infrastructure creates operational challenges for the Quadriplegia Care Devices Market. The effective use of advanced assistive devices requires proper training for healthcare providers, caregivers, and patients. Many care facilities, especially in rural or underserved areas, lack the resources and expertise needed for device setup, maintenance, and ongoing support. It leads to underutilization or improper use, compromising the benefits these technologies can deliver. Supply chain inefficiencies and limited distribution networks further restrict access to essential equipment. The market must address these barriers to realize the full potential of innovative quadriplegia care solutions.
Market Opportunities
Expansion into Emerging Markets Unlocks New Growth Potential
The expansion into emerging markets offers significant growth opportunities for the Quadriplegia Care Devices Market. Increasing healthcare investments and a rising focus on rehabilitation services in regions such as Asia Pacific, Latin America, and the Middle East create favorable conditions for market entry. Governments and non-governmental organizations support accessibility initiatives, helping to overcome traditional barriers in underserved areas. Growing awareness and changing perceptions about disability care further stimulate demand for advanced assistive devices. It enables manufacturers to broaden their distribution networks and establish local partnerships, ensuring products reach a wider population. Adaptation of devices to meet regional needs and price points enhances acceptance and drives sustained market growth.
Integration of Digital Health Technologies Enhances Patient Outcomes and Service Delivery
Integration of digital health technologies presents strong opportunities for innovation in the Quadriplegia Care Devices Market. The adoption of telehealth, remote monitoring, and smart connectivity features enables continuous patient support and real-time data collection. Healthcare providers can track patient progress and intervene proactively, leading to improved care outcomes. It encourages collaboration between device manufacturers, software developers, and medical professionals, paving the way for comprehensive care solutions. Digital platforms also facilitate remote training and technical support, increasing the efficiency of device usage. The evolution toward connected care models enhances both patient satisfaction and market competitiveness.
Market Segmentation Analysis:
By Device Type:
The Quadriplegia Care Devices Market demonstrates diverse growth across multiple device types, each tailored to address specific patient needs and care requirements. Motorized wheelchairs hold a significant share due to their widespread use for daily mobility support and independence among individuals with severe paralysis. Robotic exoskeletons and rehabilitation robotics are gaining momentum, driven by ongoing advancements in mobility restoration and intensive rehabilitation therapies. Neuroprosthetics and spinal cord stimulation devices are steadily emerging, offering promising outcomes for sensory and functional recovery. Functional Electrical Stimulation (FES) systems and assistive technologies continue to enhance patient autonomy, delivering solutions that support both active rehabilitation and daily living. The ‘Others’ category includes innovative devices that address niche requirements, reflecting the ongoing evolution of the market.
- For instance, ReWalk Robotics exoskeleton users have logged over 120,000 walking sessions since its commercial introduction.
By Application:
The Quadriplegia Care Devices Market addresses a wide spectrum of patient needs. Mobility assistance forms the backbone of the segment, providing crucial support to patients seeking greater independence. Neurological rehabilitation represents another key area, with devices designed to facilitate neuroplasticity and improve overall physical function. Pain management remains essential for quality of life, prompting the integration of advanced modalities for relief and comfort. Functional restoration devices enable patients to regain lost abilities and perform essential tasks. Daily living support solutions round out the application segment, offering equipment that simplifies and improves routine activities for individuals with quadriplegia.
- For instance, the Indego powered exoskeleton is used at over 60 rehabilitation centers worldwide, enabling more than 15,000 therapy sessions annually for spinal cord injury patients.
By End-User:
Hospitals serve as primary adopters, incorporating advanced technologies into acute and long-term care plans. Rehabilitation centers leverage a broad range of devices to deliver specialized therapy and facilitate patient recovery. Home care settings represent a rapidly growing segment, driven by patient preference for comfort and independence outside institutional settings. Long-term care facilities employ these devices to support ongoing care for residents with complex needs. Each end user segment contributes to the overall expansion of the Quadriplegia Care Devices Market, reflecting the increasing demand for specialized solutions that improve patient outcomes and streamline care delivery across diverse clinical and domestic environments.
Segments:
Based on Device Type:
- Motorized Wheelchairs
- Robotic Exoskeletons
- Neuroprosthetics
- Spinal Cord Stimulation Devices
- Functional Electrical Stimulation (FES) Systems
- Rehabilitation Robotics
- Assistive Technologies
- Others
Based on Application:
- Mobility Assistance
- Neurological Rehabilitation
- Pain Management
- Functional Restoration
- Daily Living Support
Based on End-User:
- Hospitals
- Rehabilitation Centers
- Home Care Settings
- Long-Term Care Facilities
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Quadriplegia Care Devices Market
North America Quadriplegia Care Devices Market grew from USD 1,741.09 million in 2018 to USD 2,632.49 million in 2024 and is projected to reach USD 4,640.90 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.8%. North America is holding a 41% market share. The United States leads the region, supported by strong healthcare infrastructure and early adoption of advanced assistive technologies. Canada also contributes significantly, driven by robust reimbursement policies and high awareness among patients and caregivers. Investment in research and development by leading companies fuels continuous innovation. North American hospitals and rehabilitation centers deploy a wide range of devices, strengthening market presence. Patient demand for home-based care further boosts device sales across the region.
Europe Quadriplegia Care Devices Market
Europe Quadriplegia Care Devices Market grew from USD 1,285.49 million in 2018 to USD 1,899.60 million in 2024 and is projected to reach USD 3,159.06 million by 2032, at a CAGR of 6.1%. Europe accounts for a 28% market share. Germany, the United Kingdom, and France represent the largest country-level markets. Strong government support for disability care and favorable reimbursement frameworks support regional growth. It benefits from an expanding elderly population and increasing incidence of spinal cord injuries. European manufacturers focus on integrating advanced robotics and smart features into care devices. The region’s hospitals and rehabilitation facilities emphasize innovation and high standards of patient care.
Asia Pacific Quadriplegia Care Devices Market
Asia Pacific Quadriplegia Care Devices Market grew from USD 852.52 million in 2018 to USD 1,406.50 million in 2024 and is projected to reach USD 2,783.39 million by 2032, achieving a CAGR of 8.4%. Asia Pacific holds a 25% market share. China, Japan, and India are driving market expansion through rising healthcare investments and growing patient populations. Governments and private organizations actively promote access to advanced rehabilitation devices. The rapid adoption of new technologies and expanding network of care facilities shape a dynamic growth landscape. Local manufacturers and global players compete to address diverse patient needs. Asia Pacific’s evolving healthcare infrastructure continues to create significant market opportunities.
Latin America Quadriplegia Care Devices Market
Latin America Quadriplegia Care Devices Market grew from USD 143.61 million in 2018 to USD 215.77 million in 2024 and is projected to reach USD 318.96 million by 2032, with a CAGR of 4.5%. Latin America represents a 3% market share. Brazil and Mexico dominate regional demand, supported by improving access to rehabilitation services and medical devices. Public and private investment in healthcare is on the rise, enabling steady market expansion. It faces challenges related to cost and distribution in remote areas. Partnerships between local distributors and international companies help expand device reach. Awareness initiatives by advocacy groups support greater adoption across the region.
Middle East Quadriplegia Care Devices Market
Middle East Quadriplegia Care Devices Market grew from USD 107.04 million in 2018 to USD 148.21 million in 2024 and is projected to reach USD 215.52 million by 2032, reflecting a CAGR of 4.3%. The Middle East accounts for a 2% market share. Saudi Arabia and the United Arab Emirates are the primary contributors to regional market growth. Increasing healthcare spending and a focus on medical tourism strengthen the region’s adoption of advanced devices. Efforts to build modern rehabilitation centers and improve healthcare access are underway. It continues to attract global market players interested in expanding their presence. Educational campaigns help increase acceptance of assistive technologies.
Africa Quadriplegia Care Devices Market
Africa Quadriplegia Care Devices Market grew from USD 58.29 million in 2018 to USD 99.48 million in 2024 and is projected to reach USD 135.70 million by 2032, with a CAGR of 3.4%. Africa represents a 1% market share. South Africa and Egypt are the leading markets, supported by targeted government programs and improving healthcare services. Limited access to advanced devices and lower purchasing power present challenges. It sees gradual improvement through donor-funded projects and partnerships with international organizations. Market players explore opportunities by offering cost-effective solutions suited to local needs. The expansion of rehabilitation services is expected to drive moderate growth across the region.
Key Player Analysis
- ReWalk Robotics
- Ekso Bionics
- Indego (Parker Hannifin Corporation)
- Rex Bionics Ltd.
- Caltech
- Össur
- Steeper Inc.
- Boston Scientific Corporation
- Medtronic Plc
- Ottobock
- RGK Wheelchair
Competitive Analysis
The Quadriplegia Care Devices Market features a competitive landscape dominated by several leading companies, including ReWalk Robotics, Ekso Bionics, Indego (Parker Hannifin Corporation), Rex Bionics Ltd., Caltech, Össur, Steeper Inc., Boston Scientific Corporation, Medtronic Plc, Ottobock, and RGK Wheelchair. These players focus on continuous innovation, regularly launching new products that incorporate advanced technologies such as robotic exoskeletons, neuroprosthetics, and smart assistive devices. Companies invest in expanding their global distribution networks, strategic partnerships, and collaborations with healthcare providers to reach a broader patient base and strengthen market presence. User-centric design, stringent regulatory compliance, and comprehensive after-sales support remain crucial factors in building customer trust and loyalty. The market also witnesses active patent filings and intellectual property strategies, further intensifying competition. Pricing strategies and product differentiation help companies stand out in a segment characterized by increasing demand for personalized care solutions. This competitive landscape drives ongoing improvements in device efficacy, safety, and accessibility, ensuring that patients benefit from the latest advances in quadriplegia care technologies.
Recent Developments
- In April 2025, ReWalk launched the ReWalk 7 Personal Exoskeleton, a wearable robotic device designed to provide powered leg motion for individuals with spinal cord injuries. This device builds upon ReWalk's existing exoskeleton technology, which is approved by the FDA for both rehabilitation and personal use
- In February 2024, Researchers have shown in a study published in Advanced Materials that their novel nanovector, called nanogel, can deliver anti-inflammatory drugs to glial cells that are actively involved in the development of spinal cord injury, a condition that can result in paraplegia or quadriplegia.
Market Concentration & Characteristics
The Quadriplegia Care Devices Market exhibits moderate concentration, with several established manufacturers holding significant shares alongside emerging players that drive niche innovation. It is characterized by a strong focus on advanced technologies, such as robotic exoskeletons, neuroprosthetics, and functional electrical stimulation systems, reflecting the industry’s commitment to enhancing patient mobility and independence. High entry barriers arise from strict regulatory requirements, the need for robust clinical evidence, and substantial investment in research and development. Product differentiation plays a key role, with companies competing on the basis of device reliability, safety, user comfort, and integration of smart features. The market supports both institutional and home-based care, responding to varied patient needs through a wide range of solutions. It benefits from growing awareness, government support, and evolving reimbursement policies, but cost pressures and limited access in low-resource settings continue to shape its overall structure and growth trajectory.
Report Coverage
The research report offers an in-depth analysis based on Device Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Quadriplegia Care Devices Market will witness broader adoption of robotic exoskeletons in rehabilitation centers and home care environments.
- Device manufacturers will integrate artificial intelligence to personalize therapy and improve patient engagement.
- Remote monitoring features will enable healthcare providers to track patient progress and adjust treatment plans in real-time.
- Adoption of wearable sensors will increase, facilitating precise movement analysis and feedback.
- Companies will collaborate with research institutions to develop neuroprosthetics that restore motor and sensory functions.
- Insurance coverage will expand, driving wider access to assistive technologies across various regions.
- Emerging markets will play a growing role, supported by investments in healthcare infrastructure and training.
- Device designs will shift toward modular and scalable solutions to accommodate diverse patient needs and treatment stages.
- Regulatory frameworks will evolve to support faster approval of innovative devices and digital health solutions.
- Sustainability will gain importance, prompting manufacturers to use eco-friendly materials and energy-efficient production methods.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Quadriplegia Care Devices Market?
What factors are driving the growth of the Quadriplegia Care Devices Market?
What are the key segments within the Quadriplegia Care Devices Market?
What are some challenges faced by the Quadriplegia Care Devices Market?
Who are the major players in the Quadriplegia Care Devices Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,402.04 million → 2032: USD 11,253.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Quadriplegia Care Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Quadriplegia Care Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Quadriplegia Care Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Quadriplegia Care Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Quadriplegia Care Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Quadriplegia Care Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Quadriplegia Care Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Quadriplegia Care Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,402.04 million → 2032: USD 11,253.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Quadriplegia Care Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Quadriplegia Care Devices Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Quadriplegia Care Devices Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Quadriplegia Care Devices Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
