
Market Overview
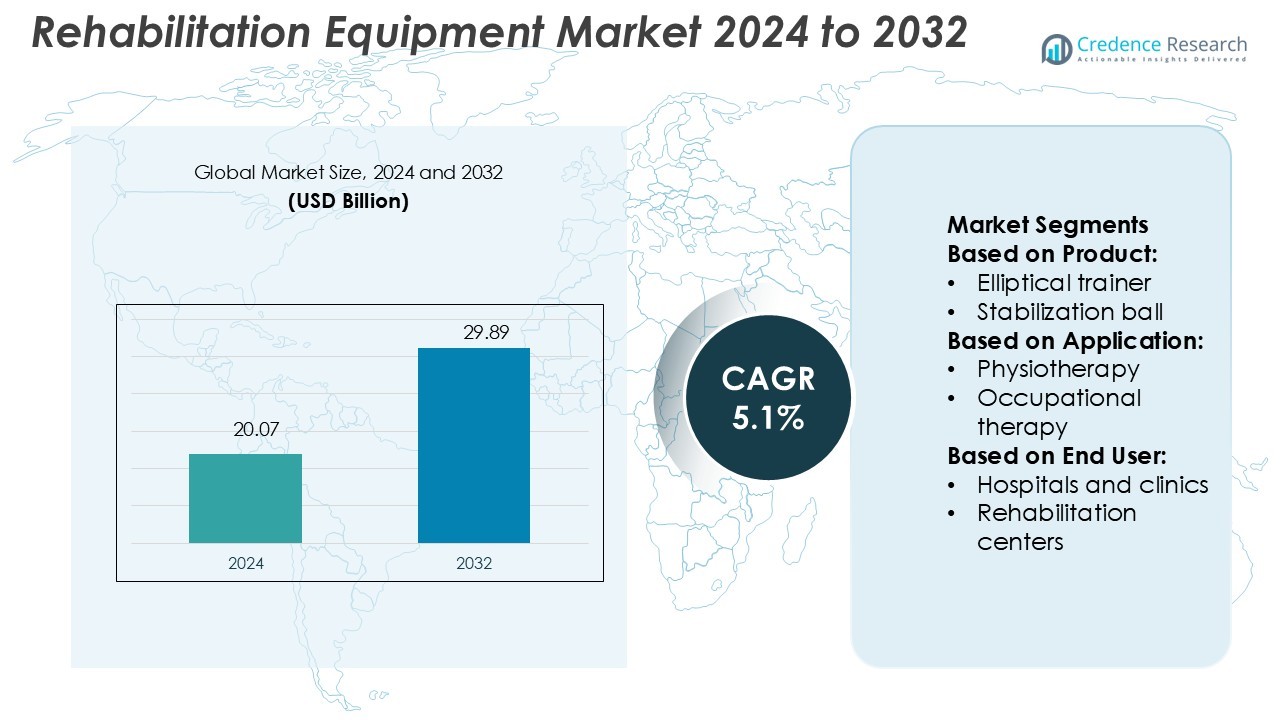
Rehabilitation Equipment Market size was valued USD 20.07 billion in 2024 and is anticipated to reach USD 29.89 billion by 2032, at a CAGR of 5.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rehabilitation Equipment Market Size 2024 | USD 20.07 Billion |
| Rehabilitation Equipment Market, CAGR | 5.1% |
| Rehabilitation Equipment Market Size 2032 | USD 29.89 Billion |
The rehabilitation equipment market is shaped by leading players such as Caremax Rehabilitation Equipment Co. Ltd, Invacare Corporation, Bioness Inc., Honeywell International, Inc., BioXtreme, DJO Global, Arjo, Halma plc, Dynatronics Corporation, and BTL. These companies strengthen their presence through innovation in physiotherapy, neurorehabilitation, mobility aids, and digitally integrated recovery solutions. Product diversification, strong distribution networks, and strategic R&D investments remain central to their competitive strategies. Regionally, North America leads the market with a 38% share, supported by advanced healthcare infrastructure, robust insurance coverage, and high adoption of smart rehabilitation devices, positioning it as the key growth hub globally.
Market Insights
- The Rehabilitation Equipment Market was valued at USD 20.07 billion in 2024 and is expected to reach USD 29.89 billion by 2032, growing at a CAGR of 5.1%.
- Key growth drivers include rising prevalence of chronic diseases, aging populations, and increasing demand for homecare rehabilitation solutions.
- Major players focus on innovation in physiotherapy, neurorehabilitation, and mobility aids, with strong R&D investments and global distribution networks strengthening competitiveness.
- High equipment costs and shortage of skilled rehabilitation professionals act as restraints, limiting adoption in developing markets.
- North America leads with 38% share due to advanced healthcare infrastructure, while stationary bicycles dominate product segments, supported by strong adoption in hospitals and rehabilitation centers.
Market Segmentation Analysis:
By Product
Within the rehabilitation equipment market, stationary bicycles hold the dominant share due to their widespread use in both clinical and homecare environments. Their popularity stems from ease of use, adaptability across different patient needs, and proven effectiveness in improving cardiovascular health and lower limb strength. Hospitals and rehabilitation centers prefer stationary bicycles for structured recovery programs, while rising adoption in homecare supports continued dominance. Growing demand for low-impact exercise solutions, coupled with integration of digital monitoring systems, further drives the stationary bicycle segment’s leadership over treadmills, rowers, and other rehabilitation products.
- For instance, Caremax Rehabilitation Equipment Co., Ltd. specializes in producing wheelchairs, rollators, crutches, walking canes, walker frames, commode chairs, and bathroom accessories. The company operates from a 30,000 m² facility in Foshan, Guangdong, China.
By Application
Physiotherapy represents the largest application segment, capturing the dominant market share as it serves patients recovering from musculoskeletal, neurological, and post-surgical conditions. The segment benefits from increasing prevalence of chronic diseases, sports-related injuries, and aging-related mobility issues. Rehabilitation equipment such as stationary bicycles, treadmills, and stabilization balls are heavily integrated into physiotherapy programs to restore function and mobility. Advancements in therapy techniques and supportive reimbursement policies strengthen adoption. As demand for evidence-based recovery solutions grows, physiotherapy continues to lead over occupational therapy and other applications in the rehabilitation equipment market.
- For instance, Dynatron Solaris® Plus 709 device offers up to 5 channels of stimulation and ultrasound therapy simultaneously, providing versatile treatment options for various patient needs.
By End-user
Hospitals and clinics dominate the end-user segment, accounting for the largest market share owing to their comprehensive rehabilitation infrastructure and wide patient base. These facilities invest heavily in advanced rehabilitation equipment, offering structured recovery programs under medical supervision. High admission rates of patients with chronic diseases, post-surgical recovery needs, and injury management create consistent demand for such equipment. Hospitals also benefit from government funding, insurance coverage, and continuous upgrades in rehabilitation technology. While rehabilitation centers and homecare settings are growing steadily, hospitals and clinics remain the most significant contributors to market expansion.
Key Growth Drivers
Rising Prevalence of Chronic Diseases and Disabilities
The increasing incidence of chronic conditions such as cardiovascular disorders, neurological impairments, and musculoskeletal injuries is a major driver for the rehabilitation equipment market. Growing aging populations, particularly in developed countries, contribute to higher cases of mobility limitations and post-surgical recovery needs. This fuels consistent demand for physiotherapy equipment, stationary bicycles, treadmills, and cardiopulmonary devices. Governments and healthcare systems are also focusing on preventive rehabilitation to reduce long-term costs, further boosting adoption across hospitals, rehabilitation centers, and homecare settings.
- For instance, BTL's Super Inductive System (SIS) operates at frequencies up to 150 Hz, making it suitable for various medical indications. Additionally, its patented Cool Flow Technology™ allows for continuous operation even under high-intensity settings, ensuring prolonged therapy sessions without overheating.
Technological Advancements in Rehabilitation Devices
Advancements in digital health and medical technologies significantly enhance the adoption of rehabilitation equipment. Integration of smart sensors, AI-based monitoring, and virtual reality tools enables real-time patient tracking and personalized therapy. These innovations improve treatment outcomes while allowing healthcare providers to optimize therapy sessions. Manufacturers are focusing on equipment that supports remote rehabilitation, catering to rising telehealth demand. As patient-centric technology evolves, advanced rehabilitation devices are becoming central to both clinical and homecare recovery pathways, accelerating market growth globally.
- For instance, Philips is developing video-based biosensing that estimates respiration rate and pulse rate using only a camera (remote PPG) during virtual consultations; this solution is in the pipeline for US FDA 510(k) clearance.
Growing Homecare and Outpatient Rehabilitation Demand
The demand for rehabilitation equipment in homecare settings is increasing due to convenience, affordability, and the rise of outpatient therapy models. Patients prefer equipment such as stationary bicycles, stabilization balls, and compact treadmills that support recovery outside clinical environments. Insurers and healthcare providers also encourage cost-effective home-based rehabilitation, reducing hospital readmissions and improving long-term care. This trend is further supported by growing awareness of self-care and fitness among elderly and disabled populations, making homecare a major driver of overall market expansion.
Key Trends & Opportunities
Integration of Digital Rehabilitation and Telehealth
A major trend shaping the market is the integration of rehabilitation equipment with telehealth platforms. Remote monitoring, connected devices, and digital applications enable therapy to continue beyond clinical settings. Patients gain access to guided sessions, progress tracking, and real-time feedback, improving adherence and recovery rates. This creates opportunities for manufacturers to develop smart rehabilitation equipment and partner with digital health providers. The shift toward hybrid rehabilitation models positions connected solutions as a significant growth area for the market.
- For instance, Omron has registered 1,661 patents in its healthcare division globally, of which 75 % relate to cardiovascular, blood pressure, or sensing technologies, supporting its connected health strategy.
Rising Investment in Rehabilitation Infrastructure
Governments and private healthcare providers are investing heavily in rehabilitation facilities and advanced equipment. These investments aim to address the rising burden of chronic diseases, sports injuries, and post-surgical care. Rehabilitation centers equipped with advanced treadmills, rowers, and cardiopulmonary devices are increasingly being established in both developed and emerging economies. Public health initiatives and supportive reimbursement structures further drive infrastructure development. This creates long-term opportunities for manufacturers to expand their presence and supply advanced solutions across diverse healthcare settings.
- For instance, the Duolith SD1 device imposes a limit on consecutive shocks: older devices (<serial 5000) permit 6,000 consecutive shocks before requiring a 5-minute pause; newer units (> serial 5000) permit 3,000 consecutive shocks before a 15-minute pause.
Adoption of Sustainable and Ergonomic Equipment Design
Sustainability and patient comfort are becoming central to rehabilitation equipment innovation. Manufacturers are adopting eco-friendly materials, energy-efficient designs, and ergonomic features to improve usability. Lightweight and portable equipment supports homecare demand, while durable, multi-functional systems enhance adoption in hospitals and clinics. This trend creates opportunities for companies to differentiate through environmentally conscious product lines. As healthcare systems emphasize sustainable procurement, rehabilitation equipment designed with eco-friendly features gains competitive advantage, appealing to both institutions and end-users.
Key Challenges
High Cost of Advanced Rehabilitation Equipment
The high cost of technologically advanced rehabilitation equipment remains a barrier, especially in developing economies. Devices integrated with smart sensors, robotics, or digital interfaces demand significant investment, limiting adoption in smaller hospitals and homecare environments. Many patients face affordability issues due to limited insurance coverage or out-of-pocket expenses. This restricts market penetration and creates disparity in access to advanced rehabilitation solutions. Addressing affordability challenges through cost-effective manufacturing and favorable reimbursement policies remains essential for sustained market growth.
Shortage of Skilled Rehabilitation Professionals
A shortage of trained rehabilitation specialists poses a significant challenge to market growth. Physiotherapists, occupational therapists, and rehabilitation experts are critical for operating equipment and guiding therapy programs effectively. In many regions, the limited availability of skilled professionals delays treatment and reduces the efficiency of rehabilitation services. The gap is more evident in rural and developing markets, where healthcare infrastructure is underdeveloped. Expanding training programs, digital guidance tools, and AI-assisted rehabilitation systems are necessary to overcome this challenge.
Regional Analysis
North America
North America leads the rehabilitation equipment market with a 38% share, driven by advanced healthcare infrastructure, high healthcare spending, and strong adoption of innovative rehabilitation solutions. The region’s aging population and growing prevalence of chronic diseases such as arthritis, cardiovascular conditions, and neurological disorders create consistent demand for physiotherapy and occupational therapy equipment. The United States dominates the regional market, supported by robust insurance coverage and investments in digital rehabilitation technologies. Increasing emphasis on home-based recovery and the presence of major manufacturers further strengthen North America’s leadership position in the global rehabilitation equipment industry.
Europe
Europe holds a 29% share of the rehabilitation equipment market, supported by well-established healthcare systems, rising geriatric populations, and strong government support for rehabilitation services. Countries such as Germany, the United Kingdom, and France are leading contributors, with a focus on advanced physiotherapy and post-surgical recovery solutions. Reimbursement policies and public healthcare programs enhance patient access to rehabilitation equipment. The region also emphasizes sustainable and ergonomic equipment designs, driving innovation among manufacturers. Growing investment in rehabilitation centers and demand for occupational therapy solutions continue to support Europe’s steady growth trajectory within the global market.
Asia Pacific
Asia Pacific accounts for 23% of the rehabilitation equipment market and is expected to register the fastest growth. Rapid industrialization, urbanization, and an increasing prevalence of chronic diseases contribute to rising demand. China, Japan, and India are major markets, supported by expanding healthcare infrastructure and government initiatives to improve rehabilitation services. The growing elderly population, particularly in Japan and China, drives adoption of homecare rehabilitation solutions. Rising healthcare expenditure and medical tourism also support growth. With increasing private investment in rehabilitation centers, Asia Pacific is positioned as a key growth engine for the rehabilitation equipment market.
Latin America
Latin America holds a 6% share of the rehabilitation equipment market, with Brazil and Mexico as the leading contributors. The market benefits from growing awareness of physiotherapy and rehabilitation care, alongside increasing investments in hospital and clinic infrastructure. Rising incidence of chronic diseases and sports-related injuries also supports demand for rehabilitation equipment such as stationary bicycles and treadmills. However, limited healthcare funding and affordability challenges restrict broader adoption. Despite these barriers, opportunities exist in expanding homecare rehabilitation solutions and private sector initiatives, which are expected to gradually improve market penetration in the region.
Middle East & Africa
The Middle East & Africa region accounts for a 4% share of the rehabilitation equipment market, reflecting its early-stage adoption. Growth is primarily driven by rising investments in healthcare infrastructure, particularly in Gulf countries such as Saudi Arabia and the UAE. Increased prevalence of non-communicable diseases, along with road traffic injuries, supports demand for rehabilitation solutions. However, limited awareness and shortage of skilled professionals in several African markets hinder wider adoption. Gradual improvement in healthcare access, coupled with international collaborations and public-private partnerships, is expected to drive future expansion in this region.
Market Segmentations:
By Product:
- Elliptical trainer
- Stabilization ball
By Application:
- Physiotherapy
- Occupational therapy
By End User:
- Hospitals and clinics
- Rehabilitation centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the rehabilitation equipment market features prominent players including Caremax Rehabilitation Equipment Co. Ltd, Invacare Corporation, Bioness Inc., Honeywell International, Inc., BioXtreme, DJO Global, Arjo, Halma plc, Dynatronics Corporation, and BTL. The rehabilitation equipment market is highly competitive, shaped by continuous innovation, diverse product portfolios, and expanding global demand. Companies focus on advancing technologies such as smart sensors, AI-enabled monitoring, and ergonomic designs to enhance patient outcomes and therapy efficiency. Growing emphasis on homecare rehabilitation and telehealth integration drives product development tailored for remote use. Price competitiveness, quality assurance, and compliance with regulatory standards are critical factors influencing market positioning. Additionally, strategic investments in research and development, mergers and acquisitions, and expansion into emerging economies are strengthening competitive dynamics, making the market increasingly innovation-driven and patient-focused.
Key Player Analysis
- Caremax Rehabilitation Equipment Co. Ltd
- Invacare Corporation
- Bioness Inc.
- Honeywell International, Inc.
- BioXtreme
- DJO Global
- Arjo
- Halma plc
- Dynatronics Corporation
- BTL
Recent Developments
- In March 2025, Healing Innovations partnered with Barrett Medical to expand access to advanced rehabilitation technology across the U.S., combining Healing Innovations' Rise&Walk InClinic with Barrett's Burt robotic trainer to create a comprehensive neurorehabilitation solution.
- In February 2025, WellSky announced significant growth and new innovations in 2024, enhancing its position in the rehabilitation equipment market through technological advancements and expanded service offerings.
- In September 2024, iFIT, a global player in exercise equipment and fitness content, unveiled its latest lineup of innovative products, marking a significant development in the rehabilitation equipment market. This new range boasts advanced hardware, a revamped operating system, the groundbreaking interactive AI Coach (currently in beta), and fresh outdoor content.
- In February 2024, Addverb introduced three robots designed for diverse applications. Venturing into healthcare robotics, the automation solutions provider launched Healan, an advanced medical cobot tailored for rehabilitation and imaging purposes.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for physiotherapy and occupational therapy equipment.
- Homecare rehabilitation solutions will gain stronger adoption due to aging populations and cost efficiency.
- Digital integration with telehealth platforms will transform rehabilitation practices globally.
- AI and sensor-enabled devices will enhance personalized therapy and remote monitoring.
- Investment in rehabilitation centers and advanced infrastructure will continue to rise.
- Portable and ergonomic designs will drive higher adoption in homecare and clinical settings.
- Emerging economies will witness rapid growth due to improving healthcare access.
- Sports injury recovery and post-surgical rehabilitation will remain strong demand drivers.
- Sustainability in equipment design will shape procurement and manufacturing trends.
- Strategic collaborations and R&D innovation will define future market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Chronic Disease Prevalence
The increasing proportion of elderly individuals and the rising incidence of chronic diseases such as cardiovascular, neurological, and musculoskeletal disorders are driving demand for rehabilitation equipment to support recovery and maintain mobility.
Technological Advancements and Digital Integration
Innovations such as smart sensors, AI-based monitoring, and telehealth-enabled devices are enhancing therapy outcomes, enabling remote rehabilitation, and making equipment more attractive to both clinical and homecare users.
Expansion of Homecare and Outpatient Rehabilitation
Growing preference for home-based and outpatient rehabilitation, driven by convenience, cost savings, and improved patient compliance, is boosting demand for portable and user-friendly rehabilitation equipment.
Investment in Rehabilitation Infrastructure
Governments and private healthcare providers are increasing investments in advanced rehabilitation centers and equipment, particularly in emerging markets, to address the growing burden of chronic conditions and improve patient outcomes.
Supportive Reimbursement and Preventive Healthcare Policies
Favorable insurance coverage and public health initiatives focused on preventive rehabilitation are making advanced equipment more accessible, encouraging adoption across hospitals, clinics, and homecare environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Rehabilitation Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rehabilitation Equipment Market projected to grow between 2025 and 2032?
Which Rehabilitation Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rehabilitation Equipment Market?
Who are the leading companies in the Rehabilitation Equipment Market?
Which region commanded the largest share of the Rehabilitation Equipment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Stationary Bicycles
- 1.2.2 Treadmills
- 1.2.3 Elliptical Trainers
- 1.2.4 Stabilization Balls
- 1.2.5 Wheelchairs & Mobility Aids
- 1.2.6 Rowers
- 1.3 By End User
- 1.3.1 Hospitals and Clinics
- 1.3.2 Rehabilitation Centers
- 1.3.3 Homecare Settings
- 1.4 By Application
- 1.4.1 Physiotherapy
- 1.4.2 Occupational Therapy
- 1.4.3 Neurorehabilitation
- 1.4.4 Cardiopulmonary Rehabilitation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20.07 billion → 2032: USD 29.89 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rehabilitation Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rehabilitation Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rehabilitation Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rehabilitation Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rehabilitation Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rehabilitation Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rehabilitation Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rehabilitation Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20.07 billion → 2032: USD 29.89 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rehabilitation Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Stationary Bicycles
- 12.3.7.2 Treadmills
- 12.3.7.3 Elliptical Trainers
- 12.3.7.4 Stabilization Balls
- 12.3.7.5 Wheelchairs & Mobility Aids
- 12.3.7.6 Rowers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals and Clinics
- 12.4.7.2 Rehabilitation Centers
- 12.4.7.3 Homecare Settings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Physiotherapy
- 12.5.7.2 Occupational Therapy
- 12.5.7.3 Neurorehabilitation
- 12.5.7.4 Cardiopulmonary Rehabilitation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rehabilitation Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Rehabilitation Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Rehabilitation Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Rehabilitation Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caremax Rehabilitation Equipment Co. Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Invacare Corporation
- 18.4 Bioness Inc.
- 18.5 Honeywell International, Inc.
- 18.6 BioXtreme
- 18.7 DJO Global
- 18.8 Arjo
- 18.9 Halma plc
- 18.10 Dynatronics Corporation
- 18.11 BTL
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

