
Market Overview
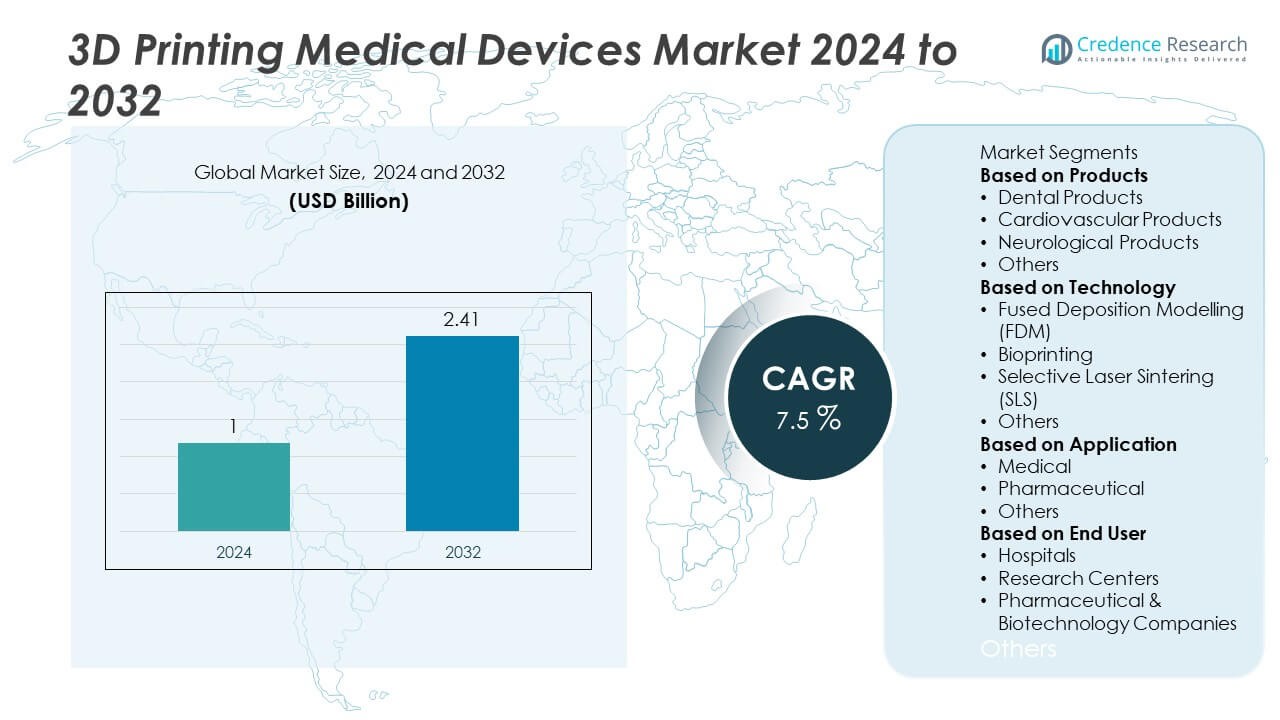
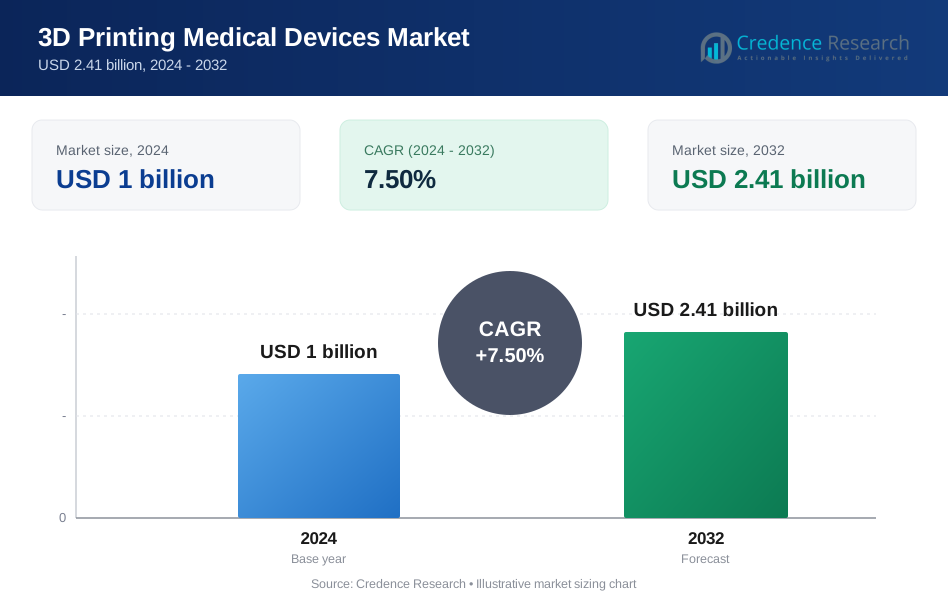
The 3D printing medical devices market was valued at USD 1 billion in 2024 and is projected to reach USD 2.41 billion by 2032, growing at a CAGR of 7.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 3D Printing Medical Devices Market Size 2024 | USD 1 Billion |
| 3D Printing Medical Devices Market, CAGR | 7.5% |
| 3D Printing Medical Devices Market Size 2032 | USD 2.41 Billion |
The 3D printing medical devices market is driven by leading players such as Stratasys Ltd., 3D Systems Corporation, Materialise NV, EOS GmbH, Renishaw plc, GE Additive, Prodways Group, SLM Solutions Group AG, EnvisionTEC (Desktop Health), and Formlabs Inc. These companies focus on developing advanced additive manufacturing technologies, biocompatible materials, and patient-specific implants to meet growing clinical demand. North America leads the market with 37% share, supported by strong adoption in hospitals and research institutions. Europe accounts for 30% share, driven by innovation in dental and orthopedic applications, while Asia-Pacific holds 25% share, emerging as the fastest-growing region due to rising healthcare investment and local manufacturing initiatives.
Market Insights
- The 3D printing medical devices market was valued at USD 1 billion in 2024 and is projected to reach USD 2.41 billion by 2032, growing at a CAGR of 7.5% during the forecast period.
- Rising demand for personalized implants, prosthetics, and surgical models drives growth, with dental products leading the segment with over 35% share due to their precision and customization benefits.
- Key trends include the expansion of bioprinting research, integration of AI in 3D printing workflows, and use of advanced biocompatible materials for complex medical applications.
- The market is competitive, with players such as Stratasys Ltd., 3D Systems, Materialise NV, EOS GmbH, and GE Additive focusing on technology innovation, partnerships with hospitals, and regulatory approvals to expand market presence.
- North America holds 37% share, Europe 30%, and Asia-Pacific 25%, while Latin America and Middle East & Africa collectively account for 8% share, supported by growing healthcare infrastructure and adoption.
Market Segmentation Analysis:
By Products
Dental products dominated the 3D printing medical devices market in 2024, accounting for over 35% share, driven by the rising demand for customized dental implants, crowns, bridges, and aligners. 3D printing enables high precision, faster turnaround times, and cost-effective production of patient-specific solutions. Growing adoption by dental laboratories and clinics for chairside manufacturing further supports segment growth. Cardiovascular and neurological products are emerging segments, benefiting from advances in biocompatible materials and regulatory approvals for patient-specific surgical models and implants, which enhance pre-surgical planning and improve patient outcomes.
- For instance, Formlabs launched its Tough 1500 V2 Resin and a second-generation Form Cure system in March 2025. When used with the company's Form 4 printer, the material enables the production of robust functional parts with an ultimate tensile strength of 34 MPa, similar to injection-molded polypropylene.
By Technology
Fused Deposition Modelling (FDM) held the largest share at over 40% in 2024, owing to its cost-efficiency, material versatility, and ability to produce complex prototypes quickly. FDM technology is widely used in orthopedic implants, surgical guides, and anatomical models. Bioprinting is gaining traction as research advances in tissue engineering and regenerative medicine accelerate, creating opportunities for functional tissue and organ printing. Selective Laser Sintering (SLS) also contributes significantly, preferred for producing high-strength, durable parts like cranio-maxillofacial implants and surgical instruments with superior mechanical properties.
- For instance, the Stratasys J5 Digital Anatomy 3D printer, released in June 2024, provides anatomical models with layer thickness down to 18 microns, enabling the reproduction of bone, muscle, and organ textures. The printer is used for surgical planning, education, and medical device development, with its biocompatible materials and hardware manufacturing sites being ISO 13485 certified.
By Application
Medical applications led the market with over 70% share in 2024, supported by rising use of 3D printing in surgical planning, prosthetics, orthopedics, and patient-specific implants. The technology improves treatment accuracy, reduces surgery time, and lowers healthcare costs by enabling highly tailored solutions. Pharmaceutical applications are growing steadily, with 3D printing being used to develop customized drug delivery systems, dosage forms, and rapid prototyping of medical devices. Other applications include research and education, where anatomical models printed in 3D are used for training healthcare professionals and improving clinical decision-making.
Key Growth Drivers
Rising Demand for Personalized and Patient-Specific Solutions
The market is driven by the growing need for personalized medical devices, contributing to over 40% of new 3D printing adoption in 2024. 3D printing enables production of customized implants, prosthetics, and surgical guides that improve patient outcomes and reduce recovery times. Healthcare providers are increasingly adopting these solutions to address anatomical variations and enhance treatment precision. This trend is particularly strong in dental, orthopedic, and cranio-maxillofacial applications where patient-specific designs are critical for functionality and comfort.
- For instance, Auxilium Biotechnologies used its AMP-1 Microfabrication Platform aboard the International Space Station to bioprint eight implantable medical devices simultaneously in two hours, demonstrating on-orbit manufacturing precision and drastically reducing production cycles for patient-specific implants.
Technological Advancements in 3D Printing Materials and Hardware
Continuous innovation in biocompatible materials, including polymers, metals, and bio-inks, drives over 35% share of market expansion. Advances in printing speed, accuracy, and scalability are making 3D printing more accessible for hospitals and research centers. Technologies such as FDM, SLS, and bioprinting are enabling production of complex structures like tissue scaffolds and surgical implants with improved mechanical strength and surface finish, expanding the range of medical applications.
- For instance, Nikon SLM Solutions multi-laser metal AM platform, used for producing custom medical implants, achieves high productivity and build rates and can produce titanium (Ti6Al4V) implants with an ultimate tensile strength well over 900 MPa, particularly after post-processing. The maximum laser scan speed can reach 10,000 mm/s on some systems, but the effective build speed is significantly lower.
Supportive Regulatory Approvals and Healthcare Investments
Regulatory bodies such as the FDA are increasingly approving 3D-printed devices, accelerating commercialization and adoption. Government and private sector investments in healthcare infrastructure and R&D are fostering innovation in additive manufacturing. This driver supports steady growth across hospitals and research institutions, encouraging the development of innovative solutions such as patient-specific models for surgical planning and drug delivery devices. Favorable reimbursement policies and collaborations between device manufacturers and healthcare providers further boost market penetration.
Key Trends & Opportunities
Growth of Bioprinting and Regenerative Medicine Applications
Bioprinting is emerging as a transformative trend, offering opportunities to create functional tissues and organ models. Research efforts are focused on printing cartilage, skin, and bone for transplant and drug testing applications. This trend attracts significant investment from biotechnology companies and academic institutions, positioning bioprinting as a key growth area over the next decade.
- For instance, researchers at the University of Galway successfully used a 4D bioprinting technique to create heart tissue constructs that undergo programmable shape-morphing. This shape-morphing process, driven by cell-generated forces, improved the structural and functional maturity of the heart tissues, resulting in stronger and faster contractions.
Integration of AI and Simulation in 3D Printing Workflows
AI-driven design tools and simulation software are being integrated into 3D printing processes, enabling faster prototyping and reducing material waste. Hospitals and research centers are using these tools to plan surgeries more accurately and optimize device performance before production. This integration opens opportunities for cost reduction and improved patient outcomes.
- For instance, 3D Systems has used its AI-powered Virtual Surgical Planning (VSP) solution for craniomaxillofacial surgical planning. In April 2024, the company announced FDA clearance for its 3D-printed PEEK cranial implants, noting that the manufacturing technology for patient-specific implants can use up to 85% less material than traditional methods.
Key Challenges
High Cost of Equipment and Materials
The significant capital investment required for advanced 3D printers, materials, and skilled labor remains a major challenge. This cost barrier limits adoption among smaller hospitals and clinics, particularly in developing regions. Maintaining production scalability while keeping costs competitive is critical for wider adoption.
Regulatory and Quality Assurance Complexities
Strict regulatory requirements for medical devices demand rigorous testing and validation, increasing time-to-market. Ensuring consistent quality, biocompatibility, and safety of 3D-printed devices is challenging due to variations in materials and printing processes. Companies must invest heavily in quality management systems to meet compliance standards, adding to operational costs.
Regional Analysis
North America
North America held 37% share in 2024, driven by strong adoption of 3D printing technologies in hospitals, dental clinics, and research centers. The United States leads with significant investments in additive manufacturing for patient-specific implants, surgical guides, and prosthetics. Favorable regulatory support from the FDA and collaborations between device manufacturers and healthcare providers accelerate innovation. High prevalence of chronic diseases and rising demand for advanced treatment solutions further boost adoption. Canada also contributes steadily with growing use of 3D printing for dental and orthopedic applications, supported by government-backed healthcare modernization programs.
Europe
Europe accounted for 30% share in 2024, supported by strong R&D capabilities and early adoption of medical 3D printing technologies. Countries like Germany, the U.K., and France lead in orthopedic and dental device production using additive manufacturing. EU initiatives promoting advanced healthcare technologies and investments in bioprinting research strengthen market growth. Regulatory alignment and focus on patient safety ensure smooth commercialization of 3D-printed devices. Increasing demand for customized implants and surgical models across hospitals is fueling consistent market expansion across both Western and Eastern European regions.
Asia-Pacific
Asia-Pacific captured 25% share in 2024, emerging as the fastest-growing regional market due to rising healthcare expenditure and rapid adoption of digital technologies. China, Japan, and India are leading markets with significant investments in 3D printing infrastructure for medical devices and research applications. Government initiatives to improve healthcare access and boost local manufacturing are supporting growth. Rising medical tourism and demand for cost-effective, patient-specific implants drive adoption across hospitals and dental clinics. Expanding partnerships between global players and regional manufacturers are helping accelerate technology transfer and market penetration.
Latin America
Latin America held 5% share in 2024, with growth supported by rising adoption of 3D printing in dental clinics, hospitals, and research centers. Brazil and Mexico lead the region, focusing on affordable orthopedic implants and surgical models. Expanding private healthcare infrastructure and increasing awareness of personalized treatment solutions are driving demand. However, limited access to high-end 3D printing equipment and skilled professionals can slow market expansion. Partnerships with global manufacturers and introduction of cost-effective printing solutions are creating opportunities for broader adoption across smaller healthcare facilities.
Middle East & Africa
The Middle East & Africa region accounted for 3% share in 2024, with demand concentrated in Gulf countries and South Africa. Investments in modernizing healthcare infrastructure, particularly in the UAE and Saudi Arabia, are encouraging adoption of 3D-printed prosthetics and surgical tools. Medical research institutions in the region are exploring bioprinting for regenerative medicine applications. Africa is witnessing gradual adoption with initiatives to improve access to affordable healthcare technologies. High equipment costs remain a barrier, but partnerships with technology providers and training programs are expected to boost growth in the coming years.
Market Segmentations:
By Products
- Dental Products
- Cardiovascular Products
- Neurological Products
- Others
By Technology
- Fused Deposition Modelling (FDM)
- Bioprinting
- Selective Laser Sintering (SLS)
- Others
By Application
- Medical
- Pharmaceutical
- Others
By End User
- Hospitals
- Research Centers
- Pharmaceutical & Biotechnology Companies
- Others
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The competitive landscape of the 3D printing medical devices market includes major players such as Stratasys Ltd., 3D Systems Corporation, Materialise NV, SLM Solutions Group AG, EOS GmbH, Renishaw plc, GE Additive, Prodways Group, EnvisionTEC (Desktop Health), and Formlabs Inc. These companies focus on advancing additive manufacturing technologies, expanding material portfolios, and delivering patient-specific solutions for dental, orthopedic, and surgical applications. Strategic initiatives include mergers, partnerships with hospitals and research institutes, and investments in bioprinting capabilities to develop functional tissues and implants. Players are also working on enhancing printing speed, precision, and cost efficiency to meet increasing demand from healthcare providers. Customization, regulatory compliance, and innovation in biocompatible materials remain key differentiators. With growing adoption of digital healthcare solutions and rising demand for personalized treatments, these players are positioned to strengthen their market presence and support the global shift toward precision medicine.
Key Player Analysis
- Stratasys Ltd.
- 3D Systems Corporation
- Materialise NV
- SLM Solutions Group AG
- EOS GmbH
- Renishaw plc
- GE Additive
- Prodways Group
- EnvisionTEC (Desktop Health)
- Formlabs Inc.
Recent Developments
- In July 2025, GE HealthCare (via GE Additive) Entered a strategic collaboration with Ascension to improve clinical and care-delivery technology efficiency.
- In May 2025, Materialise Released a report on Point-of-Care trends, noting broader clinical adoption beyond early users.
- In March 2025, Formlabs Introduced a new “10× Tougher Resin” and a faster post-cure process.
Report Coverage
The research report offers an in-depth analysis based on Products, Technology, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for 3D printing medical devices will rise with growing focus on personalized healthcare solutions.
- Dental and orthopedic applications will remain leading segments supported by increasing adoption in clinics and hospitals.
- Bioprinting will gain momentum with advances in tissue engineering and regenerative medicine research.
- Development of new biocompatible materials will enable production of stronger, safer, and more functional implants.
- North America will maintain its lead, while Asia-Pacific will grow fastest due to rising healthcare investments.
- Integration of AI and simulation tools will enhance design accuracy and reduce production time.
- Costs will gradually decline as printing technology becomes more efficient and widely available.
- Partnerships between medical device manufacturers and research institutes will accelerate innovation.
- Regulatory approvals will become faster as authorities gain confidence in 3D-printed medical solutions.
- Adoption of point-of-care 3D printing in hospitals will expand, improving treatment speed and customization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for 3D Printing Medical Devices market, and what is its projected size in 2032?
Which 3D Printing Medical Devices market segment held the largest share in 2024?
What are the primary factors fueling the growth of the 3D Printing Medical Devices market?
Who are the leading companies in the 3D Printing Medical Devices market?
Which region commanded the largest share of the 3D Printing Medical Devices market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 3D Printing Medical Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global 3D Printing Medical Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1 billion → 2032: USD 2.41 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 3D Printing Medical Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. 3D Printing Medical Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 3D Printing Medical Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 3D Printing Medical Devices Market Drivers
- 3.3 3D Printing Medical Devices Market Restraints & Challenges
- 3.4 3D Printing Medical Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 3D Printing Medical Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 3D Printing Medical Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, 3D Printing Medical Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 3D Printing Medical Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. 3D Printing Medical Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the 3D Printing Medical Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 3D Printing Medical Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 3D Printing Medical Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 3D Printing Medical Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in 3D Printing Medical Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New 3D Printing Medical Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global 3D Printing Medical Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America 3D Printing Medical Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe 3D Printing Medical Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific 3D Printing Medical Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America 3D Printing Medical Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East 3D Printing Medical Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa 3D Printing Medical Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. 3D Printing Medical Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
