
Market Overview
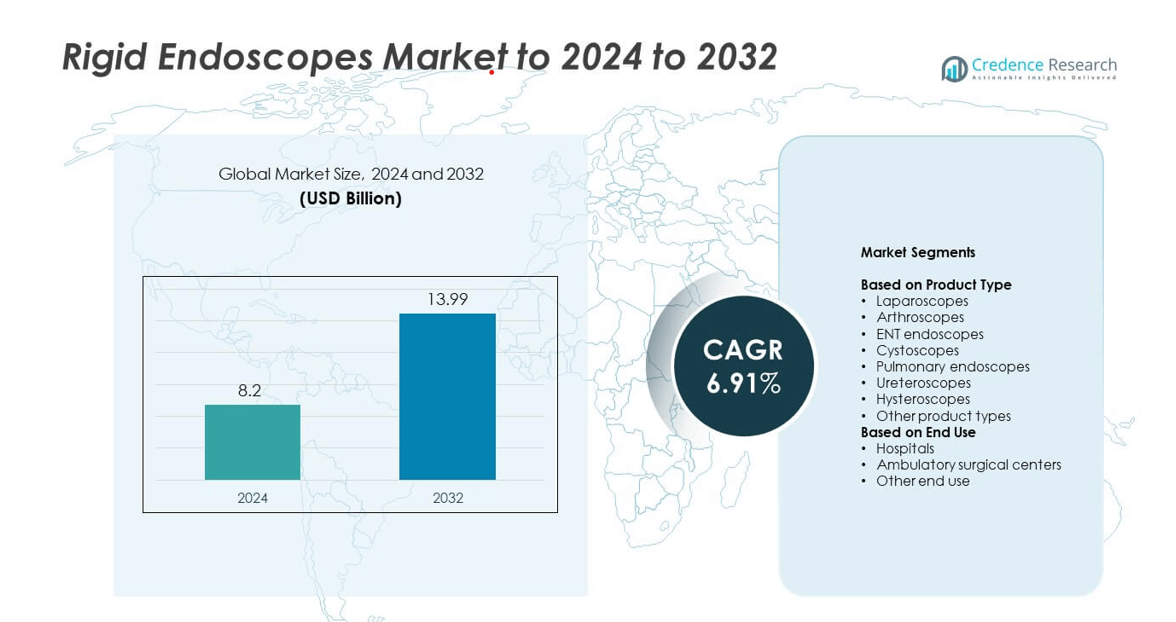
The rigid endoscopes market size was valued at USD 8.2 billion in 2024 and is anticipated to reach USD 13.99 billion by 2032, at a CAGR of 6.91% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rigid Endoscopes Market Size 2024 | USD 8.2 billion |
| Rigid Endoscopes Market, CAGR | 6.91% |
| Rigid Endoscopes Market Size 2032 | USD 13.99 billion |
The rigid endoscopes market is driven by major players such as Olympus Corporation, Karl Storz, Stryker, Medtronic, and Boston Scientific, which lead through strong innovation and global distribution networks. These companies focus on advanced optical technologies, 3D visualization, and robotic integration to enhance surgical accuracy and efficiency. Continuous R&D efforts support product upgrades and wider clinical applications across various surgical specialties. North America led the global market in 2024 with a 37% share, supported by advanced healthcare infrastructure, high procedural volumes, and early adoption of minimally invasive and robotic-assisted surgical technologies.
Market Insights
- The rigid endoscopes market was valued at USD 8.2 billion in 2024 and is projected to reach USD 13.99 billion by 2032, growing at a CAGR of 6.91%.
- Growth is driven by the rising adoption of minimally invasive surgeries, advanced imaging technologies, and expanding healthcare infrastructure worldwide.
- Key trends include the integration of robotics and AI in endoscopic systems, along with the growing use of reusable and sterilization-friendly instruments.
- The market is highly competitive, with players focusing on R&D, ergonomic designs, and global expansion to strengthen their market presence.
- Regionally, North America held a 37% share in 2024, followed by Europe with 29% and Asia-Pacific with 25%, while laparoscopes remained the dominant product segment with 34% of the market.
Market Segmentation Analysis:
By Product Type
Laparoscopes dominated the rigid endoscopes market in 2024, accounting for 34% of the total share. Their wide adoption in minimally invasive surgeries such as gallbladder removal, hernia repair, and bariatric procedures drives segment growth. Advancements in high-definition imaging and 3D visualization further enhance surgical accuracy, boosting demand. Arthroscopes and ENT endoscopes also show steady adoption due to growing orthopedic and sinus surgeries. Increasing patient preference for faster recovery and reduced hospital stays continues to strengthen laparoscope usage across global healthcare systems.
- For instance, the KARL STORZ IMAGE1 S 4U system features 3840×2160 (4K) resolution and a 3× digital zoom, while the weight of its compatible camera heads can vary.
By End Use
Hospitals held the largest share of 61% in 2024, driven by advanced infrastructure and access to skilled surgeons. The high volume of complex diagnostic and therapeutic endoscopic procedures supports hospital dominance. Increased funding for upgrading surgical units and integrating robotic-assisted systems further enhances adoption. Ambulatory surgical centers are gaining traction due to faster patient turnover and cost-effective operations. The growing trend of outpatient surgeries and enhanced recovery programs is expected to accelerate the demand for rigid endoscopes in both hospitals and specialty centers.
- For instance, Intuitive reported an installed base of 10,763 da Vinci systems and 427 quarterly placements.
Key Growth Drivers
Rising Adoption of Minimally Invasive Surgeries
The demand for rigid endoscopes is increasing due to the global shift toward minimally invasive surgical procedures. These surgeries reduce patient trauma, recovery time, and hospital costs while improving outcomes. Hospitals are rapidly upgrading operating rooms with advanced endoscopic equipment to meet patient demand. Surgeons favor rigid endoscopes for their superior image clarity and precision. The rising incidence of chronic diseases requiring surgical intervention, such as gastrointestinal and orthopedic disorders, continues to boost adoption across both developed and emerging healthcare markets.
- For instance, Medtronic’s LigaSure technology has been used in more than 35 million procedures.
Technological Advancements in Imaging and Optics
Continuous innovation in optical fibers, 3D visualization, and high-definition imaging is a major factor driving market growth. Modern rigid endoscopes now offer enhanced brightness, depth perception, and accuracy, improving surgical outcomes. The integration of digital sensors and AI-based image enhancement helps surgeons perform complex procedures with greater precision. Manufacturers are investing in compact and ergonomic designs, improving usability and sterilization. These developments not only enhance clinical efficiency but also extend product lifespans, further strengthening market expansion across surgical specialties.
- For instance, FUJIFILM surgical camera heads specify 4K UHD at 3840×2160 and 60 fps.
Growing Demand in Ambulatory Surgical Centers
Ambulatory surgical centers are rapidly adopting rigid endoscopes to perform outpatient surgeries efficiently. The demand is driven by lower treatment costs, faster recovery, and reduced hospital stays. Surgeons prefer rigid endoscopes in these settings for their reliability and consistent image quality. Increasing healthcare investments and insurance coverage for minimally invasive procedures further support this trend. The shift toward decentralized healthcare delivery models encourages equipment manufacturers to develop portable and cost-effective endoscopic systems, expanding their reach across smaller surgical facilities globally.
Key Trends & Opportunities
Integration of Robotics and AI in Endoscopic Systems
The combination of robotics and artificial intelligence with rigid endoscopy is transforming surgical precision. AI algorithms enable real-time image analysis, assisting surgeons in detecting abnormalities and reducing human error. Robotic-assisted endoscopy enhances dexterity and control during complex operations. Major healthcare providers are integrating these systems into surgical suites to improve outcomes and efficiency. This technological convergence presents significant opportunities for manufacturers to offer next-generation, intelligent endoscopy solutions, driving premium product adoption in advanced surgical centers worldwide.
- For instance, Asensus reported over 2,700 Senhance procedures year-to-date by September 30, 2023. By that same date, the company had initiated five new Senhance Surgical programs.
Rising Focus on Sterilization and Reusable Devices
A growing emphasis on infection control and sustainability is fueling the demand for reusable rigid endoscopes. Healthcare providers are seeking sterilization-friendly and durable models to reduce operating costs and medical waste. Advances in autoclaving materials and modular component design are extending product life. Regulatory bodies promoting eco-friendly practices are also encouraging the transition from disposable to reusable devices. This shift supports long-term efficiency and cost reduction while addressing environmental concerns within hospital and surgical center operations.
- For instance, Olympus warrants Goldtip rigid laparoscopes for 5 years against autoclave damage.
Expansion into Emerging Healthcare Markets
Emerging economies in Asia-Pacific and Latin America offer vast growth potential due to rising healthcare expenditure and improving surgical infrastructure. Government investments in public health facilities and growing awareness of minimally invasive procedures are accelerating adoption. Local manufacturers are collaborating with global brands to introduce affordable, high-performance endoscopes. Training programs for surgeons and ongoing hospital modernization efforts further support market penetration. These developments create lucrative opportunities for expanding the rigid endoscopes market across underserved regions.
Key Challenges
High Equipment and Maintenance Costs
Rigid endoscopes involve significant capital investments and high maintenance expenses, limiting adoption among smaller healthcare facilities. The cost of advanced imaging systems, sterilization units, and replacement parts further increases operational budgets. Developing regions often struggle with funding constraints, delaying infrastructure upgrades. Additionally, frequent calibration and repair requirements affect workflow efficiency. These factors collectively pose a challenge to widespread adoption, particularly in resource-limited medical environments seeking cost-effective surgical solutions.
Shortage of Skilled Endoscopic Professionals
A lack of trained surgeons and technicians capable of operating advanced rigid endoscopes hinders market expansion. Complex procedures require specialized skills in handling and maintaining delicate optical instruments. In many emerging regions, training facilities remain limited, and professional development programs are underfunded. This shortage affects surgical outcomes and slows the integration of new technologies. Addressing this challenge requires continuous medical education, investment in simulation-based training, and manufacturer-led skill enhancement initiatives.
Regional Analysis
North America
North America dominated the rigid endoscopes market with a 37% share in 2024. The region’s growth is driven by advanced healthcare infrastructure, high adoption of minimally invasive surgeries, and strong presence of key manufacturers. Increasing demand for laparoscopic and arthroscopic procedures in the United States and Canada supports steady expansion. Favorable reimbursement policies and continuous product innovation enhance procedural efficiency and clinical outcomes. The region also benefits from early adoption of 3D and robotic-assisted endoscopic systems, which improve surgical precision and patient recovery times across major hospitals and specialized centers.
Europe
Europe accounted for a 29% share of the rigid endoscopes market in 2024. Strong healthcare systems in Germany, France, and the United Kingdom contribute to significant adoption of advanced endoscopic solutions. The region’s emphasis on quality care and surgical accuracy drives steady demand. Favorable regulatory frameworks and government investments in modernizing healthcare facilities strengthen market penetration. The growing elderly population, coupled with rising cases of gastrointestinal and orthopedic conditions, increases surgical volumes. Manufacturers in Europe are also focusing on cost-effective, sterilization-friendly designs to support sustainability initiatives within hospitals and ambulatory centers.
Asia-Pacific
Asia-Pacific captured a 25% share of the rigid endoscopes market in 2024, showing the fastest growth rate globally. Expanding healthcare infrastructure, rising medical tourism, and increasing adoption of minimally invasive procedures are key contributors. Countries like China, Japan, and India are investing heavily in hospital modernization and surgical training. The region’s large patient population and growing awareness of early disease diagnosis are fueling demand. Local manufacturers are forming partnerships with international brands to deliver affordable, high-quality endoscopic systems. Government initiatives to enhance healthcare access further support strong market expansion across Asia-Pacific.
Latin America
Latin America held a 6% share of the rigid endoscopes market in 2024. The market is gradually expanding with growing investments in healthcare modernization and increased awareness of endoscopic procedures. Brazil and Mexico are leading in surgical adoption due to improving medical infrastructure and the availability of trained professionals. The shift toward minimally invasive surgeries in private hospitals and specialty clinics drives steady growth. However, high equipment costs and uneven healthcare access remain challenges. Despite these limitations, public health initiatives and regional partnerships continue to enhance market penetration across the region.
Middle East & Africa
The Middle East & Africa region accounted for a 3% share of the rigid endoscopes market in 2024. Growth is supported by rising healthcare investments, particularly in Saudi Arabia, the UAE, and South Africa. Expanding hospital networks and increased demand for advanced diagnostic and surgical technologies are boosting adoption. Government-led programs under national health strategies encourage modernization of surgical facilities. While high import costs and limited skilled professionals pose challenges, growing awareness of early disease management and adoption of minimally invasive procedures continue to drive gradual market development across the region.
Market Segmentations:
By Product Type
- Laparoscopes
- Arthroscopes
- ENT endoscopes
- Cystoscopes
- Pulmonary endoscopes
- Ureteroscopes
- Hysteroscopes
- Other product types
By End Use
- Hospitals
- Ambulatory surgical centers
- Other end use
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The rigid endoscopes market is led by prominent players such as Olympus Corporation, Karl Storz, Stryker, Medtronic, Boston Scientific, Arthrex, Fujifilm, B. Braun, Smith & Nephew, Richard Wolf, ConMed, PENTAX Medical, Henke-Sass Wolf, XION GmbH, Schölly Fiberoptic, Ambu A/S, and Cook Medical. These companies focus on expanding product portfolios through innovation in optics, 3D visualization, and integration of digital and robotic technologies. Strong distribution networks and partnerships with healthcare institutions enhance their global presence. Many manufacturers are investing in cost-efficient, sterilization-friendly, and reusable devices to meet sustainability goals. Strategic mergers, acquisitions, and R&D initiatives aim to strengthen surgical precision and improve patient outcomes. Growing demand for advanced imaging and minimally invasive tools is driving these firms to develop compact and ergonomic designs. Continuous technological upgrades, surgeon training programs, and region-specific product strategies further solidify their competitive positioning in both developed and emerging healthcare markets.
Key Player Analysis
- Olympus Corporation
- Karl Storz
- Stryker
- Medtronic plc
- Boston Scientific
- Arthrex
- Fujifilm
- B. Braun
- Smith & Nephew
- Richard Wolf
- ConMed
- PENTAX Medical
- Henke-Sass, Wolf
- XION GmbH
- Schölly Fiberoptic
- Ambu A/S
- Cook Medical
Recent Developments
- In 2025, Fujifilm Holdings Corporation Unveiled the groundbreaking ELUXEO 8000 Therapeutic Endoscopy Solution in India
- In 2024, Olympus Corporation opened its first flexible endoscope sterilization facility, Sapphire, in Melbourne, as part of a new service offering to improve risk management for endoscopy services.
- In 2024, Medtronic plc Introduced the ColonPRO AI software for its GI Genius intelligent endoscopy system in, a move aimed at improving patient care.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The rigid endoscopes market will continue to grow steadily due to rising surgical volumes.
- Adoption of minimally invasive and robotic-assisted surgeries will expand across healthcare facilities.
- Advancements in optics, 3D imaging, and AI-based visualization will enhance surgical precision.
- Hospitals will maintain dominance, while ambulatory surgical centers gain significant traction.
- Asia-Pacific will emerge as the fastest-growing region due to improving healthcare infrastructure.
- Demand for reusable and sterilization-friendly endoscopes will rise to support sustainability goals.
- Training programs for surgeons and technicians will expand to address skill shortages.
- Manufacturers will focus on ergonomic designs and digital integration for workflow efficiency.
- Strategic partnerships and mergers will increase to strengthen product portfolios and market presence.
- Government healthcare investments will support broader accessibility of advanced endoscopic technologies worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Rigid Endoscopes Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rigid Endoscopes Market projected to grow between 2025 and 2032?
Which Rigid Endoscopes Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rigid Endoscopes Market?
Who are the leading companies in the Rigid Endoscopes Market?
Which region commanded the largest share of the Rigid Endoscopes Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8.2 billion → 2032: USD 13.99 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rigid Endoscopes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rigid Endoscopes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rigid Endoscopes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rigid Endoscopes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rigid Endoscopes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rigid Endoscopes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rigid Endoscopes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rigid Endoscopes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8.2 billion → 2032: USD 13.99 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rigid Endoscopes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rigid Endoscopes Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rigid Endoscopes Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rigid Endoscopes Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

