
Market Overview:
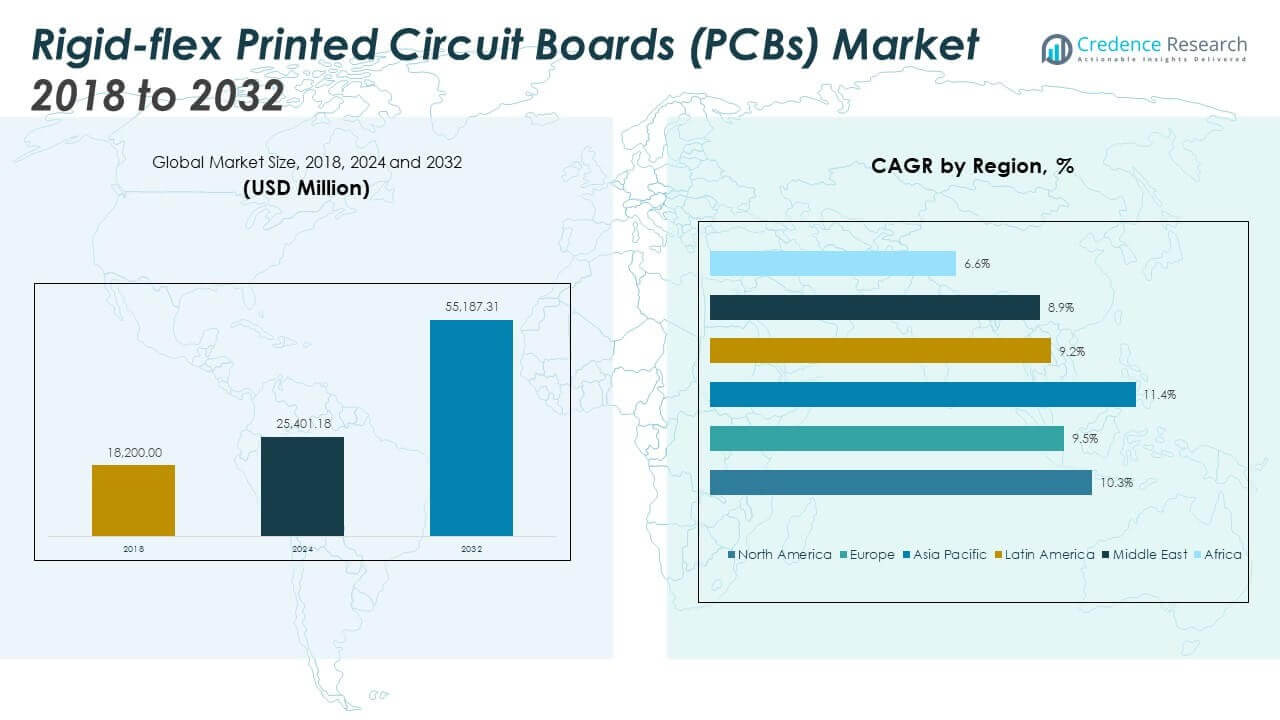
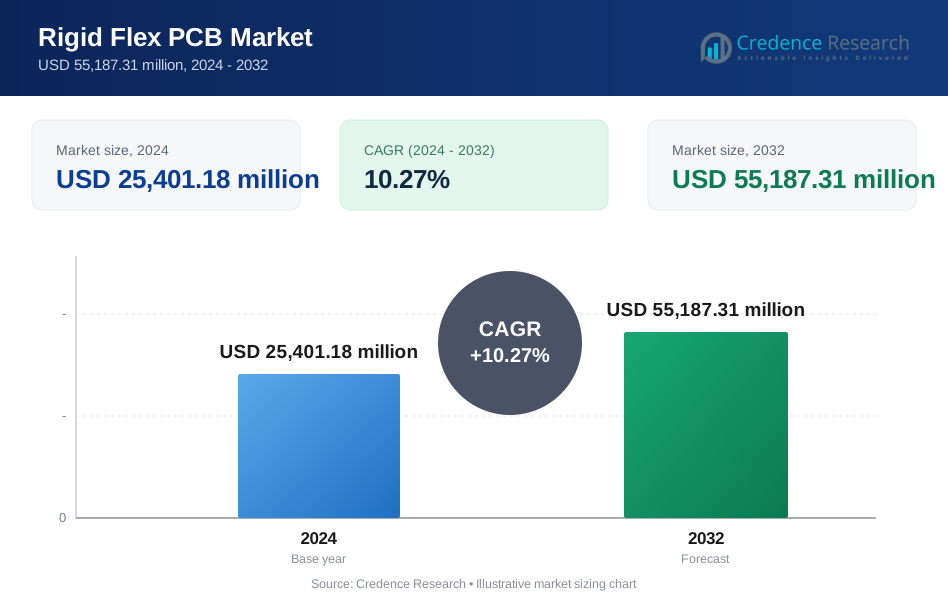
The Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 18,200.00 million in 2018 to USD 25,401.18 million in 2024 and is anticipated to reach USD 55,187.31 million by 2032, at a CAGR of 10.27% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rigid Flex PCB Market Size 2024 | USD 25,401.18 Million |
| Rigid Flex PCB Market, CAGR | 10.27% |
| Rigid Flex PCB Market Size 2032 | USD 55,187.31 Million |
The market is growing due to rising demand for compact, high-performance electronics across consumer, automotive, aerospace, and medical sectors. Rigid-flex PCBs offer design flexibility, space savings, and improved signal reliability, making them suitable for advanced applications. The shift toward electric vehicles, wearable technology, and smart medical devices has increased adoption. OEMs prefer these PCBs for reducing connectors, improving durability, and enabling complex 3D assembly. Their ability to handle mechanical stress and heat makes them ideal for harsh environments and mission-critical systems.
Asia Pacific dominates the global market due to its large-scale electronics manufacturing and supply chain strength in countries like China, South Korea, and Taiwan. North America follows, driven by aerospace, defense, and medical technology innovation. Europe contributes through its strong automotive electronics demand. Emerging markets in Southeast Asia and Latin America are gaining traction with expanding local assembly and consumer electronics demand. Regional growth is shaped by end-use innovation, policy support, and investment in advanced PCB fabrication.
Market Insights:
- The Rigid-flex Printed Circuit Boards (PCBs) Market was valued at USD 18,200.00 million in 2018, reached USD 25,401.18 million in 2024, and is projected to hit USD 55,187.31 million by 2032, growing at 10.27%.
- North America led with a 33.7% share in 2024, followed by Asia Pacific at 29.5% and Europe at 25.5%, driven by strong demand from aerospace, consumer electronics, and automotive sectors respectively.
- Asia Pacific is the fastest-growing region, fueled by advanced electronics manufacturing in China, South Korea, and Taiwan along with rising demand for mobile and automotive electronics.
- Multi-layer flex accounted for the largest segment share at 36.2% in 2024 due to its suitability in high-density, complex circuit designs across consumer and industrial applications.
- Among layer types, the multi-layer segment held 41.3% share, supported by its usage in compact, high-performance systems across telecom, defense, and EV platforms.
Market Drivers
Miniaturization and Integration Needs Across Consumer Electronics and Portable Devices
Manufacturers are designing compact and lightweight electronic devices that demand space-efficient circuit board designs. Rigid-flex PCBs support three-dimensional configuration and eliminate interconnects, which helps reduce weight and thickness. Smartphones, wearables, and tablets increasingly rely on these boards to enable complex, multi-functional designs. Their ability to integrate rigid and flexible sections allows seamless folding, bending, and component placement. The Rigid-flex Printed Circuit Boards (PCBs) Market benefits directly from this trend across global OEMs. It ensures high reliability under stress and continuous movement, extending product life cycles. Use in foldable smartphones and smartwatches is gaining traction due to space constraints. High-density electronic packaging will continue to drive demand for advanced rigid-flex PCB architectures.
Adoption of Rigid-Flex PCBs in Advanced Automotive Electronics and EV Platforms
The automotive sector increasingly integrates electronics for safety, infotainment, navigation, and battery management systems. Rigid-flex PCBs provide high vibration resistance and better electrical performance in limited spaces. In electric vehicles (EVs), these PCBs offer improved reliability in high-voltage applications with thermal management. Their mechanical stability ensures fewer solder joints and lower failure risks under dynamic conditions. It supports advanced driver-assistance systems (ADAS) and interior electronics. Tier-1 suppliers and automakers now use rigid-flex circuits for dashboard units, LiDAR, and EV controllers. The Rigid-flex Printed Circuit Boards (PCBs) Market continues to grow with the shift to electric and connected vehicles. Electronic component integration in compact automotive spaces accelerates its usage.
- For instance, ZF Friedrichshafen AG develops advanced power electronics for electric vehicles that support 800V architectures in compact module designs. These systems emphasize high reliability, efficient thermal management, and space optimization for modern EV platforms without disclosing internal PCB construction details.
Increased Use in Aerospace, Military, and Medical Applications Requiring Harsh-Environment Reliability
Defense and aerospace electronics need robust PCBs that can withstand high G-forces, temperature extremes, and continuous motion. Rigid-flex PCBs ensure high mechanical endurance and maintain signal integrity in tight enclosures. These boards are crucial in satellites, missiles, avionics, and unmanned aerial vehicles (UAVs). In the medical sector, they serve as reliable components in hearing aids, imaging systems, pacemakers, and surgical tools. The high reliability and long service life of rigid-flex PCBs fit critical mission operations. It helps reduce wiring complexity while meeting strict regulatory standards. Their stable performance in life-saving and defense applications strengthens adoption. Precision and compactness make them indispensable in critical-use electronics.
Growing Preference for Long-Term Cost Efficiency and Reduced Assembly Time
Rigid-flex PCBs reduce overall system costs by eliminating connectors, cables, and separate board assemblies. This helps minimize assembly steps, testing stages, and potential failure points. Manufacturers adopt them to lower production time and enhance design reliability. Although upfront material costs may be higher, the long-term operational cost is reduced. It helps improve yield, reduce maintenance, and support automation-friendly layouts. The Rigid-flex Printed Circuit Boards (PCBs) Market benefits as OEMs prioritize total lifecycle value over initial capital cost. Automated production and smaller component footprints further support cost-effective scalability. These benefits improve competitiveness for manufacturers across industries, supporting continued demand growth.
- For instance, Northrop Grumman deploys high-reliability electronic assemblies in UAV avionics and space systems that meet stringent MIL-STD-810 environmental requirements. These designs support operation under extreme temperature ranges, vibration, and mechanical stress, making them suitable for satellites, missiles, avionics, and unmanned aerial vehicles.
Market Trends
Use of Rigid-Flex PCBs in Foldable Smartphones and Flexible Display Technologies
Consumer electronics OEMs continue exploring foldable smartphones, tablets, and dual-screen laptops with flexible displays. These devices require PCBs that can endure repeated bending without loss of function. Rigid-flex PCBs enable durable, thin, and space-saving layouts that fold or flex along device hinges. It reduces the need for complex interconnects and enables seamless transitions between device segments. Brands focus on optimizing hinge design and internal layouts using these boards. The Rigid-flex Printed Circuit Boards (PCBs) Market gains traction as flexible display tech enters the mainstream. Wearables and e-readers also explore this format for form factor innovation. Growth in next-gen screen technologies will sustain this trend.
- For instance, Samsung Galaxy Z Fold 5 features an advanced Flex Hinge engineered to handle over 200,000 folding and unfolding cycles, according to Samsung’s hinge durability guidance, and the device carries an IPX8 water-resistance rating for everyday protection. This hinge design supports the foldable display and structural flexibility that modern foldables require.
Increased Implementation of High-Speed Signal Transmission in Compact PCB Layouts
High-speed data transfer and signal integrity are critical in 5G, cloud computing, and high-performance computing. Rigid-flex PCBs help reduce electrical noise and improve signal quality in dense, multilayered designs. Controlled impedance and precise routing across rigid and flexible zones improve communication speed. This supports applications in advanced telecom equipment, edge devices, and AI servers. Compact and lightweight layouts also support thermal management in high-frequency systems. The Rigid-flex Printed Circuit Boards (PCBs) Market leverages this shift to meet growing bandwidth demands. It helps improve transmission reliability where traditional PCBs fall short. The need for real-time processing supports its relevance in connected systems.
- For instance, the Samsung Galaxy Z Fold5 supports Wi-Fi 6E with peak speeds up to 9.6 Gbps and weighs about 253 g. The device’s engineering uses advanced PCB assemblies to integrate high-speed wireless modules in a compact foldable form factor without explicitly disclosing detailed rigid-flex PCB internals.
Growing Demand for Sustainable Electronics with Reduced Material and Component Waste
Sustainability goals push manufacturers toward design strategies that minimize waste and resource use. Rigid-flex PCBs eliminate the need for multiple interconnects and connectors, reducing component count. It leads to lighter electronics, lower power use, and more efficient supply chains. Cleaner designs also help reduce error rates, improving device longevity and recycling compatibility. Manufacturers focus on optimizing board layouts to reduce unused area and materials. The Rigid-flex Printed Circuit Boards (PCBs) Market aligns with these environmental objectives. Efficient production and long-term durability support lower environmental impact. The trend favors circular design principles in electronics development.
Adoption of 3D Design Tools and Simulation Software in PCB Development
The industry increasingly uses 3D simulation and design software to improve rigid-flex PCB layouts. These tools help engineers visualize the board in folded and flexed states before production. Accurate modeling of stress points and bend radii ensures fewer failures in prototypes. CAD tools improve routing, reduce signal distortion, and optimize component placement. Simulation helps avoid design rework and speeds up time-to-market. It supports complex multilayer configurations in tight enclosures. The Rigid-flex Printed Circuit Boards (PCBs) Market benefits from this shift toward digital twin design practices. Design-for-manufacturing tools streamline product development workflows, enhancing reliability and precision.
Market Challenges Analysis
Complexity in Design, Prototyping, and Manufacturing Processes Increases Operational Barriers
Rigid-flex PCB production involves advanced design, careful material selection, and complex multilayer fabrication. It requires specialized equipment and technical expertise to manage routing across rigid and flexible layers. Engineers must ensure mechanical durability while preserving electrical performance. Even minor errors in bend radius or component placement can lead to failure. Prototyping costs are higher due to tighter tolerances and longer design cycles. The Rigid-flex Printed Circuit Boards (PCBs) Market faces slow adoption among small and mid-sized manufacturers. Many lack access to tools, skills, or capacity to handle these intricate requirements. This limits widespread penetration across lower-volume applications.
High Upfront Cost and Limited Design Flexibility for Mass Market Applications
Despite long-term savings, rigid-flex PCBs carry high initial tooling and fabrication costs. Low-volume projects or consumer-grade products often cannot justify these expenses. Design constraints like fixed flex zones and limited rework options add to development risk. The complexity also affects supplier selection, with only a few vendors offering full-service capabilities. It limits design freedom and complicates supply chain scaling. Mass production for rapidly changing consumer electronics remains difficult without standardization. The Rigid-flex Printed Circuit Boards (PCBs) Market may face barriers in fast-paced segments where turnaround time and cost sensitivity matter more. Adoption will depend on advancing low-cost fabrication and modular platforms.
Market Opportunities
Expanding Role of Rigid-Flex PCBs in Edge AI Devices, IoT Modules, and Sensor Networks
The growth of edge computing and connected devices creates new demand for compact, reliable PCBs. Rigid-flex PCBs support small form-factor designs with durable performance and efficient routing. It enables integration of sensors, communication modules, and microcontrollers in a single compact structure. Demand for smart wearables, medical patches, and industrial IoT devices is rising. The Rigid-flex Printed Circuit Boards (PCBs) Market can tap into these segments through tailored solutions.
Integration into Next-Generation Medical Devices, Robotics, and Autonomous Systems
Emerging medical technologies require miniaturized and biocompatible electronics with high reliability. Surgical robots, wearable monitors, and implantable systems favor flexible and lightweight PCBs. In robotics and automation, rigid-flex boards allow mobility, precision, and mechanical endurance. It supports dynamic systems where space and stability are critical. Market participants can focus on product customization and regulatory-ready designs to capture this demand.
Market Segmentation Analysis:
The Rigid-flex Printed Circuit Boards (PCBs) Market is segmented by product type, layer count, flexibility type, materials, and end-use industry.
By Product Type
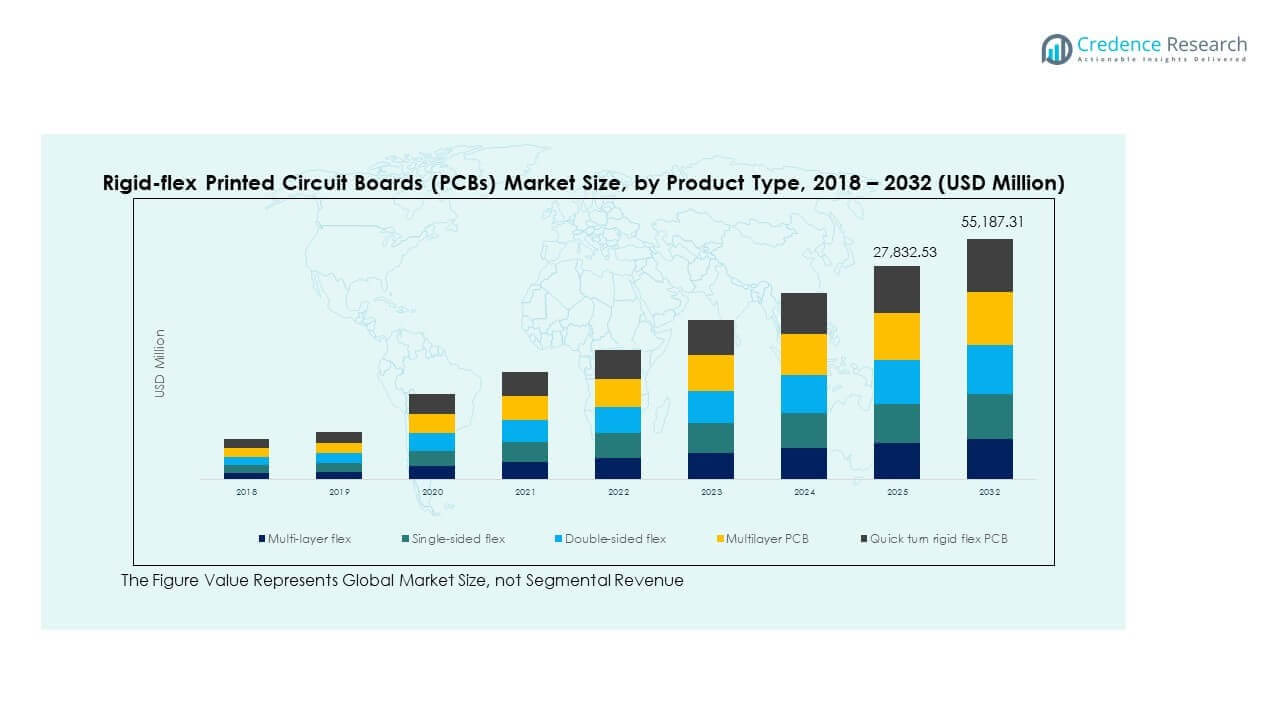
Multi-layer flex holds the largest share due to rising complexity in electronic designs. Single-sided and double-sided flex PCBs serve simpler applications across wearables and low-power devices. Multilayer PCBs and quick-turn rigid-flex variants gain traction in prototyping and time-sensitive development cycles.
By Layer Count
layer count, multi-layer PCBs dominate due to their support for high-density routing in compact devices. Single-layer and double-layer segments cater to basic designs where cost and simplicity are key. In terms of flexibility type, dynamic flex boards lead the market due to use in devices exposed to continuous motion. Static flex boards serve fixed configurations, especially in medical and industrial electronics.
By Materials
Material-wise, FR4 remains the standard base, while Kapton is preferred for thermal resistance in aerospace and defense. Rogers materials address high-frequency signal needs in telecom and advanced computing. Others include polyimide blends used in niche or high-performance cases. The Rigid-flex Printed Circuit Boards (PCBs) Market sees continued material diversification to support durability, conductivity, and miniaturization.
- For instance, IPC-4101/26 high-Tg FR-4 laminates are widely used in multilayer PCBs to reduce Z-axis expansion and thermal stress. These material properties help improve interconnection reliability and durability in high-layer-count circuit board designs.
By End-Use Industry
Consumer electronics form the largest end-use segment due to demand from smartphones, tablets, and wearables. Aerospace and defense rely on these boards for compactness and reliability under stress. Automotive applications grow rapidly with EVs and ADAS integration. IT, telecommunications, industrial, and healthcare sectors also adopt rigid-flex PCBs to meet evolving design and reliability needs. The “Others” category includes energy and transportation systems adopting compact, vibration-resistant PCB solutions.
- For instance, multilayer flex circuits withstand up to 500 million flex cycles before failure, enhancing durability in wearables by eliminating wiring harnesses.
Segmentation:
By Product Type
- Multi-layer flex
- Single-sided flex
- Double-sided flex
- Multilayer PCB
- Quick turn rigid-flex PCB
By Layer Count
- Multi-layer
- Single layer
- Double layer
By Flexibility Type
- Dynamic flex
- Static flex
By Materials
- FR4
- Kapton
- Rogers
- Others
By End-Use Industry
- Consumer electronics
- Aerospace and defense
- Automotive
- Industrial
- IT and telecommunications
- Healthcare
- Others (e.g., Energy, Transportation)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 6,224.40 million in 2018 to USD 8,575.29 million in 2024 and is anticipated to reach USD 18,603.74 million by 2032, at a CAGR of 10.3% during the forecast period. Market share: 33.7% in 2024. North America leads the Rigid-flex Printed Circuit Boards (PCBs) Market due to high demand in defense, aerospace, and medical applications. The region hosts strong players involved in advanced electronics manufacturing and custom PCB design. The U.S. Department of Defense and NASA remain key end-users, with strong preferences for rugged and flexible board configurations. The growing adoption of IoT and miniaturized devices also fuels demand for rigid-flex PCBs. Medical device companies in the U.S. use these boards in diagnostic and implantable tools. It benefits from robust R&D investment and early adoption of advanced manufacturing processes. The rise of electric vehicles and autonomous systems further strengthens regional adoption. North America will maintain its leadership in high-reliability sectors.
Europe
The Europe Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 4,823.00 million in 2018 to USD 6,471.53 million in 2024 and is anticipated to reach USD 13,286.49 million by 2032, at a CAGR of 9.5% during the forecast period. Market share: 25.5% in 2024. Europe holds a strong position in the Rigid-flex Printed Circuit Boards (PCBs) Market due to the automotive and industrial automation sectors. Germany, France, and Italy drive demand through Tier 1 suppliers and OEMs implementing smart electronics in vehicles and factories. Aerospace programs across Western Europe use these boards for mission-critical applications. The region is adopting lightweight, durable PCBs to support EV platforms and autonomous navigation systems. Leading medical electronics manufacturers across Germany and the Netherlands use these boards in imaging and surgical equipment. It benefits from established regulatory compliance and quality assurance frameworks. Europe’s focus on sustainable design and digital industrialization accelerates PCB innovation. Continued investment in robotics and smart infrastructure supports long-term growth.
Asia Pacific
The Asia Pacific Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 5,168.80 million in 2018 to USD 7,489.43 million in 2024 and is anticipated to reach USD 17,731.73 million by 2032, at a CAGR of 11.4% during the forecast period. Market share: 29.5% in 2024.Asia Pacific is the fastest-growing region in the Rigid-flex Printed Circuit Boards (PCBs) Market, led by manufacturing hubs in China, South Korea, Taiwan, and Japan. Consumer electronics giants in the region use these PCBs in smartphones, laptops, and wearables. Low production costs, skilled labor, and advanced fabrication capabilities drive regional expansion. The automotive sector, especially in Japan and South Korea, integrates rigid-flex PCBs in in-vehicle electronics and battery systems. It benefits from continuous investments in 5G, AI, and compact edge computing systems. High-density packaging and vertical integration strategies support efficient supply chains. Asia Pacific’s leadership in both production and consumption enhances its long-term outlook. Regional governments also support electronics exports and local innovation initiatives.
Latin America
The Latin America Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 1,055.60 million in 2018 to USD 1,457.77 million in 2024 and is anticipated to reach USD 2,917.75 million by 2032, at a CAGR of 9.2% during the forecast period. Market share: 5.7% in 2024. Latin America is an emerging market in the Rigid-flex Printed Circuit Boards (PCBs) Market, with growing opportunities in consumer electronics and automotive production. Mexico leads regional demand due to its strong electronics assembly ecosystem and integration with U.S. supply chains. Brazil contributes through medical equipment manufacturing and telecom infrastructure. Regional governments support industrial digitization, boosting local PCB demand. It benefits from a growing middle-class population and increased demand for mobile and connected devices. The expansion of EV production plants across Mexico and Brazil supports new use cases for rigid-flex PCBs. Local OEMs adopt these boards for their durability and space-saving benefits. The region still relies on imports for high-end fabrication, but domestic capability is improving.
Middle East
The Middle East Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 691.60 million in 2018 to USD 904.12 million in 2024 and is anticipated to reach USD 1,771.82 million by 2032, at a CAGR of 8.9% during the forecast period. Market share: 3.6% in 2024. The Middle East market is gradually expanding, driven by investments in defense, aerospace, and telecom sectors. Gulf nations focus on digital transformation and smart city projects that integrate rigid-flex PCBs in surveillance, control systems, and sensor networks. The UAE and Saudi Arabia lead regional adoption due to heavy investments in high-tech infrastructure. Defense programs and satellite initiatives also support demand for reliable, lightweight circuit boards. It benefits from rising demand for rugged electronics in extreme environments. Healthcare modernization initiatives increase demand for compact diagnostic and wearable medical devices. The region relies on imports but shows signs of growing local assembly capabilities. Long-term demand will grow with expanding industrial electronics sectors.
Africa
The Africa Rigid-flex Printed Circuit Boards (PCBs) Market size was valued at USD 236.60 million in 2018 to USD 503.05 million in 2024 and is anticipated to reach USD 875.78 million by 2032, at a CAGR of 6.6% during the forecast period. Market share: 2.0% in 2024. Africa represents a nascent but promising segment of the Rigid-flex Printed Circuit Boards (PCBs) Market. The market is driven by the growing consumer electronics penetration and mobile device usage. Countries like South Africa, Nigeria, and Kenya are seeing higher adoption of telecom infrastructure, which indirectly supports PCB demand. It remains reliant on imported rigid-flex PCBs for now, but local assembly and repair industries are growing. Regional healthcare modernization projects create new use cases for compact, flexible electronics. Educational institutions and startups explore prototyping applications using imported boards. Africa’s slow but steady digital expansion will offer long-term potential. Investments in smart agriculture and energy also open up niche opportunities.
Key Player Analysis:
- Zhen Ding Technology Holding Limited
- Nippon Mektron, Ltd.
- Sumitomo Electric Industries, Ltd.
- Unimicron Technology Corporation
- Interflex Co., Ltd.
- Young Poong Electronics Co., Ltd.
- TTM Technologies, Inc.
- Multek (a Flex Company)
- Shengyi Technology Co., Ltd.
- AT&S Austria Technologie & Systemtechnik AG
- Meiko Electronics Co., Ltd.
- Kinwong Electronic Co., Ltd.
- Jabil Circuit, Inc.
- Samsung Electro-Mechanics
- Würth Elektronik GmbH & Co. KG
- Shenzhen Kinwong Electronic Co., Ltd.
Competitive Analysis:
The Rigid-flex Printed Circuit Boards (PCBs) Market is characterized by the presence of both global leaders and specialized regional manufacturers. Key players include Zhen Ding Technology, Nippon Mektron, Sumitomo Electric, Unimicron, and TTM Technologies, all of which maintain strong technological capabilities and production scale. Companies focus on miniaturization, multi-layer design, and high-reliability performance to meet evolving customer demands. It remains highly competitive due to continuous innovation in materials, layer count, and automation processes. Strategic mergers, capacity expansions, and targeted R&D investments shape the competitive edge. Asian manufacturers dominate high-volume production, while U.S. and European firms lead in military, aerospace, and medical-grade PCBs. Partnerships with OEMs in automotive, telecom, and consumer electronics sectors further drive competition. Market share continues to shift with growing demand for compact, high-speed, and flexible board solutions.
Recent Developments:
- In July 2025, OKI Circuit Technology launched advanced rigid-flex PCBs with embedded copper coins. These PCBs target the growing New Space market, addressing heat management for high-heat components while enabling space savings, weight reductions, and connector-less designs to cut mounting time.
- In October 2024, Zhen Ding Technology Holding Limited signed a strategic cooperation agreement with DuPont to advance high-end printed circuit board technology, focusing on R&D, material performance, and sustainable smart manufacturing for the electronics industry. This partnership enhances their capabilities in Rigid-flex PCBs amid growing demand in automotive and consumer sectors
Report Coverage:
The research report offers an in-depth analysis based on product type, layer count, flexibility type, materials, and end-use industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for lightweight, compact, and foldable electronics will expand use across mobile and wearable devices.
- Automotive OEMs will accelerate adoption of rigid-flex PCBs in electric vehicles, especially for battery control and infotainment systems.
- Growth in aerospace and defense contracts will support rugged, mission-critical rigid-flex applications.
- Rising integration of AI and edge computing will drive high-density, multilayer rigid-flex board production.
- Medical device innovation, particularly in implants and diagnostic tools, will fuel demand for miniaturized PCB layouts.
- Asia Pacific will continue leading production, but reshoring and regional manufacturing diversification will reshape global supply chains.
- Advancements in flexible materials like polyimide and low-loss laminates will enable better performance in high-frequency devices.
- Strategic collaborations between OEMs and PCB fabricators will become key for next-gen product development.
- Rapid prototyping and quick-turn services will gain importance in consumer and industrial electronics segments.
- Sustainability goals will push manufacturers toward material efficiency, reduced waste, and recyclable PCB solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Rigid-flex Printed Circuit Boards (PCBs) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rigid-flex Printed Circuit Boards (PCBs) Market projected to grow between 2024 and 2032?
Which Rigid-flex Printed Circuit Boards (PCBs) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rigid-flex Printed Circuit Boards (PCBs) Market?
Who are the leading companies in the Rigid-flex Printed Circuit Boards (PCBs) Market?
Which region commanded the largest share of the Rigid-flex Printed Circuit Boards (PCBs) Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Rigid Flex PCB Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Rigid Flex PCB Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 25,401.18 million → 2032: USD 55,187.31 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Rigid Flex PCB Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Rigid Flex PCB Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Rigid Flex PCB Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Rigid Flex PCB Market Drivers
- 3.3 Rigid Flex PCB Market Restraints & Challenges
- 3.4 Rigid Flex PCB Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Rigid Flex PCB Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Rigid Flex PCB Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Rigid Flex PCB category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Rigid Flex PCB Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Rigid Flex PCB Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Rigid Flex PCB. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Rigid Flex PCB Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Rigid Flex PCB Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Rigid Flex PCB Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Rigid Flex PCB (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Rigid Flex PCB
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Rigid Flex PCB Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Rigid Flex PCB Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Rigid Flex PCB Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Rigid Flex PCB Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Rigid Flex PCB Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Rigid Flex PCB Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Rigid Flex PCB Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Rigid Flex PCB Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
