
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| PACS (Picture Archiving and Communication Systems) and RIS (Radiology Information Systems) Market Size 2024 | USD 3,646.5 Million |
| PACS (Picture Archiving and Communication Systems) and RIS (Radiology Information Systems) Market , CAGR | 6.30% |
| PACS (Picture Archiving and Communication Systems) and RIS (Radiology Information Systems) Market Size 2032 | USD 5,944.86 Million |
Market Overview
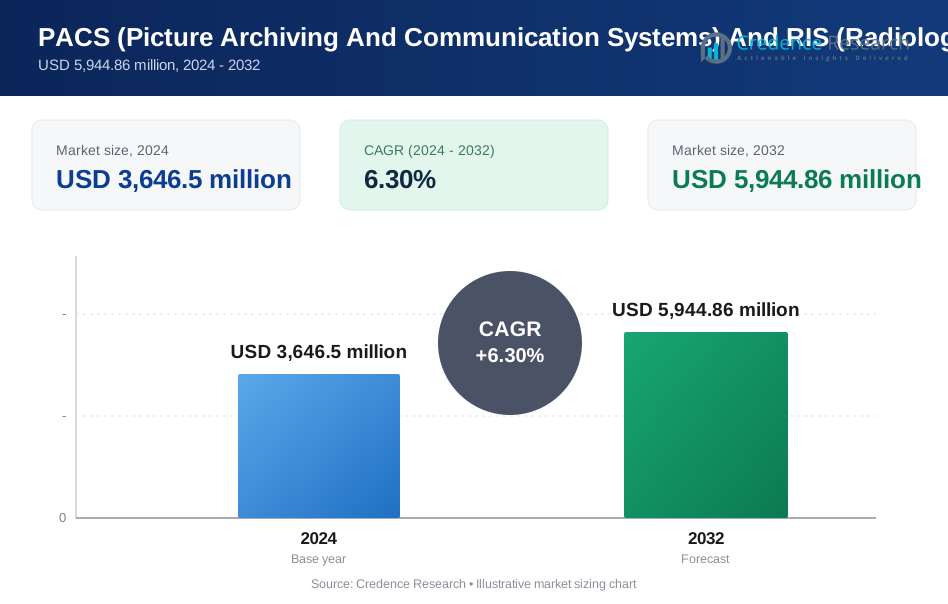
The PACS (Picture Archiving and Communication Systems) and RIS (Radiology Information Systems) Market is projected to grow from USD 3,646.5 million in 2024 to USD 5,944.86 million by 2032, at a compound annual growth rate (CAGR) of 6.30%.
The PACS (Picture Archiving and Communication Systems) and RIS (Radiology Information Systems) market is primarily driven by the increasing demand for efficient imaging solutions, enhanced workflow automation, and the rising adoption of digital healthcare technologies. The growing emphasis on patient-centric care and the need for streamlined radiology processes further propel market growth. Additionally, technological advancements, such as the integration of artificial intelligence and cloud-based solutions, are transforming the landscape of medical imaging. The shift towards telemedicine and remote diagnostics also contributes to the demand for robust PACS and RIS, ensuring accessibility and improving healthcare delivery.
North America holds a significant share of the PACS and RIS market, driven by advanced healthcare infrastructure and the adoption of cutting-edge technologies. Europe follows closely due to rising demand for efficient diagnostic tools. Key players such as GE Healthcare, Siemens Healthineers, Philips Healthcare, and FujiFilm Holdings Corporation dominate the market with innovative solutions. Other prominent companies, including McKesson Corporation, Cerner Corporation, Merge Healthcare, and Agfa, are also influential, continuously enhancing their offerings to meet growing demands for seamless data management and improved diagnostic accuracy across healthcare facilities worldwide.
Market Drivers
Improved Efficiency and Workflow
PACS (Picture Archiving and Communication Systems) significantly enhances operational efficiency by centralizing and digitizing medical images, which eliminates the need for physical storage and retrieval. This streamlined image management not only saves valuable time but also reduces the potential for errors associated with manual handling. For instance, a study by Healthlink Advisors found that PACS solutions are critical in managing medical imaging, allowing radiologists to access patient imaging records and conduct detailed image analysis efficiently. Additionally, RIS (Radiology Information Systems) facilitates enhanced communication and collaboration among healthcare providers, allowing for faster and more accurate diagnoses. By automating routine tasks, both PACS and RIS significantly reduce turnaround time, ensuring that imaging results are processed and delivered promptly, thereby improving patient care.
Enhanced Diagnostic Accuracy
The integration of PACS systems leads to improved diagnostic accuracy through advanced processing techniques that enhance image quality, aiding in the detection of subtle abnormalities. For instance, PACS provides advanced viewing capabilities, allowing radiologists to examine images for a more detailed analysis, which is crucial for identifying subtle abnormalities. Access to historical images is another crucial advantage, as PACS allows healthcare professionals to easily review a patient's previous imaging studies, providing essential context for diagnosis and treatment planning. Furthermore, the integration of RIS with other healthcare systems, such as electronic health records (EHRs), creates a comprehensive view of a patient's medical history, enabling more informed clinical decisions and better patient outcomes.
Cost Reduction
PACS and RIS contribute to significant cost reduction in healthcare facilities. By eliminating the need for physical storage space, PACS leads to substantial savings on storage costs. The improved workflow efficiency achieved through these systems not only reduces operational costs but also enhances overall productivity. Moreover, RIS aids in enhancing revenue cycle management by automating billing and insurance processes, thus further optimizing financial performance.
Regulatory Compliance and Technological Advancements
PACS and RIS systems support healthcare organizations in maintaining regulatory compliance, particularly concerning patient data privacy. By providing secure storage and access controls, these systems help organizations adhere to regulations such as HIPAA. Additionally, advancements in technology, including cloud-based solutions, have made PACS and RIS more accessible and affordable for smaller healthcare providers. The integration of artificial intelligence (AI) into these systems also enhances image analysis capabilities, improves abnormality detection, and supports clinical decision-making, further revolutionizing medical imaging practices.
Market Trends
Cloud-Based Solutions and Integration with EHRs
The adoption of cloud-based solutions for PACS and RIS has revolutionized healthcare infrastructure by offering remarkable scalability and flexibility. Healthcare providers can now adjust their systems based on fluctuating demand without incurring substantial upfront costs associated with traditional hardware and software investments. For instance, many healthcare providers are moving toward cloud-based PACS solutions, allowing for easier access to medical images from different locations, facilitating collaboration among healthcare professionals, and reducing the need for on-premises infrastructure. This cloud-based approach not only improves accessibility, allowing remote access to medical images and data, but also facilitates better collaboration among healthcare professionals, ultimately enhancing patient care. Furthermore, the integration of PACS and RIS with Electronic Health Records (EHRs) allows for a comprehensive view of a patient's medical history, leading to improved accuracy in diagnoses and treatment plans. By streamlining workflows through this integration, healthcare providers can eliminate the need for manual data entry, thereby reducing the risk of errors and increasing overall operational efficiency.
Advancements in AI, Mobile Access, and Cybersecurity
Artificial Intelligence (AI) and machine learning are increasingly being incorporated into PACS and RIS systems, resulting in enhanced image analysis capabilities. These advanced technologies facilitate the efficient and accurate detection of abnormalities that may be overlooked by human radiologists. AI can also automate routine tasks, such as image classification and segmentation, allowing radiologists to devote more time to complex cases that require their expertise. Additionally, mobile and remote access to PACS and RIS systems has transformed the landscape of medical imaging by enabling radiologists to review images and consult with colleagues from virtually any location. This capability not only improves patient care by reducing turnaround times but also fosters enhanced collaboration among healthcare providers. As the volume of medical data stored in PACS and RIS systems continues to rise, there is an increasing emphasis on cybersecurity and data privacy. Healthcare organizations are prioritizing the implementation of robust security measures to protect sensitive patient data from unauthorized access. Compliance with data privacy regulations, such as HIPAA, is crucial to maintaining the trust of patients and stakeholders alike. Moreover, the emergence of advanced imaging modalities, including PET/CT and molecular imaging, is driving demand for PACS and RIS systems capable of handling and analyzing these complex datasets, further highlighting the importance of technological advancements in the field.
Market Challenges Analysis
High Initial Investment and Ongoing Maintenance Costs
Implementing a PACS (Picture Archiving and Communication System) and RIS (Radiology Information System) requires a substantial initial investment in hardware, software, and infrastructure. For instance, a typical PACS system for a radiology practice generating 1,000 studies a month can cost around $40,000 for the total cost of ownership, including software, storage, and maintenance. These systems demand not only significant financial resources for installation but also ongoing maintenance expenses, which can accumulate over time. For example, annual maintenance and support for a PACS system can add another $7,500 to $10,000 to the five-year total cost of ownership. Healthcare organizations must budget for regular updates, hardware replacements, and technical support to ensure that the systems remain efficient and effective. This high financial burden can deter some healthcare providers, particularly smaller organizations, from adopting these advanced technologies. As a result, they may miss out on the benefits that PACS and RIS can offer in terms of improved workflow and patient care. Additionally, the complexity associated with integrating these systems with existing healthcare technologies, such as Electronic Health Records (EHRs) and Laboratory Information Systems (LIS), can exacerbate financial constraints and operational challenges.
Data Security, Privacy Challenges, and Resistance to Change
PACS and RIS systems inherently store sensitive patient information, making them prime targets for cyberattacks. As such, healthcare providers face the dual challenge of safeguarding this data while complying with strict regulations, such as the Health Insurance Portability and Accountability Act (HIPAA). The costs associated with achieving compliance and enhancing cybersecurity measures can be substantial, adding to the financial burden of implementing these systems. Furthermore, resistance to change among healthcare staff can hinder the successful deployment of PACS and RIS. Many employees may be accustomed to traditional workflows and may find it challenging to adapt to new technologies. Overcoming this resistance requires a dedicated approach to user adoption, including comprehensive training programs and ongoing support to ensure staff members feel confident using the new systems. Additionally, scalability challenges may arise as the volume of medical imaging data continues to grow, placing further strain on existing infrastructure and necessitating additional investments in storage and processing capacity. Together, these challenges underscore the complexities healthcare organizations must navigate when adopting PACS and RIS technologies.
Market Segmentation Analysis:
By Product:
The Picture Archiving and Communication Systems (PACS) and Radiology Information Systems (RIS) market is primarily segmented by product and component. In terms of product segmentation, PACS holds a significant share due to its role in centralizing and digitizing medical images, facilitating improved access and collaboration among healthcare professionals. With the rise in medical imaging needs, PACS systems are increasingly adopted across various healthcare settings. Meanwhile, RIS plays a crucial role in managing radiological data, improving workflow efficiency, and supporting patient care, which further drives its adoption in hospitals and diagnostic centers.
By Component:
Segmenting by components, the market comprises hardware, software, and services. The hardware segment includes servers, storage devices, and imaging equipment, which are essential for effective system implementation. The software segment, encompassing the PACS and RIS applications, is rapidly evolving with advancements in artificial intelligence and cloud computing. Finally, the services segment includes implementation, maintenance, and support, which are vital for ensuring optimal performance and compliance with regulatory standards. Collectively, these segments contribute to the growth and development of the PACS and RIS market, addressing the increasing demand for efficient and effective medical imaging solutions.
Segments:
Based on Product
- PACS (Picture Archiving and Communication Systems)
- RIS (Radiology Information Systems)
Based on Component
- Hardware
- Software
- Services
Based on Mode of Delivery
- On-Premise
- Cloud-Based
- Web-Based
Based on End User
- Hospitals
- Diagnostic Centers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share in the PACS and RIS market, accounting for over 40% of the global revenue. This dominance is driven by the region's advanced healthcare infrastructure, high adoption of medical imaging technologies, and robust government support for healthcare digitization. The United States, in particular, leads the market due to its well-established healthcare IT systems and the presence of key industry players. Additionally, the integration of PACS and RIS with electronic health records (EHRs) enhances workflow efficiency and diagnostic accuracy, contributing to higher demand for these systems. The growing focus on improving patient care and the early adoption of cloud-based solutions also play a crucial role in sustaining North America's leadership in this market.
Asia-Pacific
In contrast, Asia-Pacific is experiencing rapid growth and is expected to capture a significant share, currently contributing around 25% of the global market. This surge is fueled by the increasing adoption of healthcare IT solutions in emerging economies like China, India, and Japan. Government initiatives to modernize healthcare infrastructure, coupled with rising investments in diagnostic centers and hospitals, drive demand for PACS and RIS systems in the region. Furthermore, the shift toward cloud-based and AI-powered imaging solutions is accelerating the growth of the market in Asia-Pacific, making it a key region for future expansion.
Key Player Analysis
- FujiFilm Holdings Corporation
- GE Healthcare
- Merge Healthcare
- Siemens Healthineers
- Philips Healthcare
- Cerner Corporation
- McKesson Corporation
- Agfa
Competitive Analysis
The PACS and RIS market is highly competitive, with key players such as GE Healthcare, Siemens Healthineers, Philips Healthcare, FujiFilm Holdings Corporation, McKesson Corporation, Agfa, Merge Healthcare, and Cerner Corporation leading the industry. These companies dominate the market by offering comprehensive solutions that enhance diagnostic accuracy, improve workflow efficiency, and ensure seamless integration with other healthcare systems like EHRs. The competitive landscape is characterized by continuous innovation, with players focusing on cloud-based solutions, artificial intelligence, and advanced imaging technologies. These innovations help them cater to the growing demand for efficient data management and improved patient care, securing their strong market positions.
Recent Developments
- In October 2024, GE HealthCare integrated AI-enabled application orchestration feature into True PACS and Centricity PACS in collaboration with Blackford.
- In October 2024, McKesson launched InspiroGene, a dedicated business to guide and support the commercialization of cell and gene therapies.
- In September 2024, Siemens Healthineers acquired Novartis’s molecular imaging business for $223 million.
- In November 2023, Philips launched HealthSuite Imaging, a cloud-based next generation of Vue PACS, with new AI-enabled clinical and operational workflows at RSNA23.
- In January 2023, Manipal Hospitals collaborated with FUJIFILM India to provide digitized solutions for patient diagnosis, including a large-scale PACS.
Market Concentration & Characteristics
The PACS and RIS market is moderately concentrated, with a few major players such as GE Healthcare, Siemens Healthineers, Philips Healthcare, and FujiFilm Holdings Corporation holding a significant share. These companies have established dominance through advanced technology offerings, broad product portfolios, and strategic partnerships. Market concentration is also driven by high barriers to entry, including the need for substantial capital investment, regulatory compliance, and integration complexities with existing healthcare systems. Despite this concentration, the market exhibits dynamic characteristics, with increasing adoption of cloud-based solutions, artificial intelligence, and mobile access driving competition. Smaller firms focus on niche solutions, adding diversity to the competitive landscape.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Product, Component, Mode of Delivery, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The PACS and RIS market is expected to witness steady growth due to increasing demand for efficient healthcare workflows.
- Advancements in artificial intelligence and machine learning will enhance image analysis and decision-making capabilities.
- Cloud-based solutions will gain more traction, offering scalability and remote access to healthcare providers.
- Integration with electronic health records (EHRs) will streamline data management and improve diagnostic accuracy.
- Growing focus on cybersecurity will drive investment in secure PACS and RIS systems to protect sensitive patient data.
- Mobile access to PACS and RIS systems will improve collaboration among healthcare professionals and enhance patient care.
- Regulatory compliance will remain a key challenge, especially in terms of data privacy and security standards.
- Emerging markets will present significant growth opportunities as healthcare infrastructure improves in these regions.
- Ongoing technological advancements in imaging modalities will require PACS and RIS systems to handle more complex datasets.
- Increased demand for teleradiology services will further boost the adoption of PACS and RIS in remote areas.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the PACS (Picture Archiving And Communication Systems) and RIS (Radiology Information Systems) market?
What factors are driving the growth of the PACS (Picture Archiving And Communication Systems) and RIS (Radiology Information Systems) market?
What are the key segments within the PACS (Picture Archiving And Communication Systems) and RIS (Radiology Information Systems) market?
What are some challenges faced by the PACS (Picture Archiving And Communication Systems) and RIS (Radiology Information Systems) market?
Who are the major players in the PACS (Picture Archiving And Communication Systems) and RIS (Radiology Information Systems) market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,646.5 million → 2032: USD 5,944.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,646.5 million → 2032: USD 5,944.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global PACS (Picture Archiving And Communication Systems) And RIS (Radiology Information Systems) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
