
Market Overview
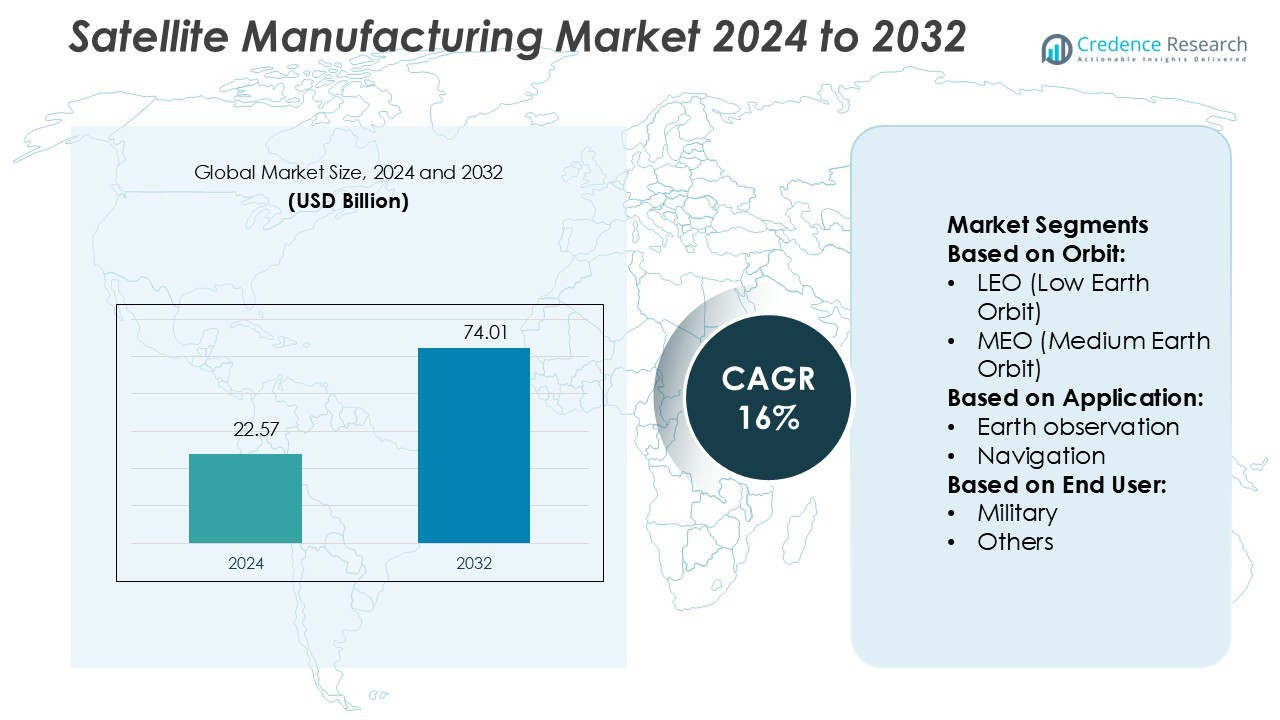
Satellite Manufacturing Market size was valued USD 22.57 billion in 2024 and is anticipated to reach USD 74.01 billion by 2032, at a CAGR of 16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite Manufacturing Market Size 2024 | USD 22.57 Billion |
| Satellite Manufacturing Market, CAGR | 16% |
| Satellite Manufacturing Market Size 2032 | USD 74.01 Billion |
The satellite manufacturing market is shaped by leading players including Airbus, Boeing, Lockheed Martin, BAE Systems, Blue Canyon Technologies, Dhruva Space, EnduroSat, INVAP, Beijing Smart Satellite, and the Indian Space Research Organisation. These companies compete through technological innovation, large-scale production, and partnerships across commercial, government, and defense sectors. Established global leaders maintain dominance with advanced manufacturing capabilities, while emerging firms strengthen their presence through small satellite solutions and cost-efficient platforms. Regionally, North America leads the market with a 40% share, driven by strong government contracts, defense investments, and robust private sector initiatives supporting satellite constellations and communication programs.
Market Insights
- The Satellite Manufacturing Market was valued at USD 22.57 billion in 2024 and will reach USD 74.01 billion by 2032, growing at a CAGR of 16%.
- Rising demand for broadband connectivity, Earth observation, and navigation services is driving market expansion, supported by increasing government and defense investments worldwide.
- The market is witnessing a trend toward small satellite constellations, cost-efficient manufacturing, and advanced technologies such as electric propulsion, AI integration, and software-defined payloads.
- Competition remains intense, with established players leveraging advanced capabilities while emerging firms focus on affordable, scalable solutions; however, high manufacturing and launch costs continue to restrain smaller participants.
- North America leads with 40% share due to strong defense contracts and private sector initiatives, while Europe holds 25% with programs like Galileo; Asia Pacific accounts for 22% driven by China, India, and Japan, and communication satellites remain the dominant segment with over 45% share globally.
Market Segmentation Analysis:
By Orbit
Low Earth Orbit (LEO) satellites dominate the market with over 60% share, driven by growing demand for Earth observation, broadband connectivity, and small satellite constellations. Their lower launch costs and shorter latency make them highly attractive for commercial and defense applications. Medium Earth Orbit (MEO) satellites are mainly used for navigation services, while Geostationary Earth Orbit (GEO) satellites serve large-scale communication and broadcasting needs. However, the shift toward flexible, high-capacity LEO constellations continues to push investment and innovation, strengthening their lead in global satellite manufacturing.
- For instance, Boeing’s O3b mPOWER satellites use fully software-defined payloads that can dynamically allocate power among beams; Boeing delivered its 9th and 10th O3b mPOWER units featuring this flexibility.
By Application
Communication satellites account for the largest share, exceeding 45% of the market, supported by rising demand for broadband internet and global connectivity. Telecom operators and space tech companies are investing heavily in high-throughput communication satellites to reduce latency and expand coverage. Earth observation follows closely, driven by its use in weather monitoring, agriculture, and defense. Navigation satellites remain critical for GPS and global positioning systems, while other applications, such as scientific research, also contribute to steady growth. Increasing commercial reliance on space-based communication ensures communication remains the dominant segment.
- For instance, Dhruva Space offers the BOLT module, a hybrid connectivity solution designed for satellite applications.The module is capable of switching between terrestrial 4G/5G mobile networks and Dhruva Space's satellite network to ensure continuous coverage.
By End User
The commercial segment leads the market with over 50% share, fueled by private sector investments in communication constellations, Earth observation services, and broadband deployment. Companies like SpaceX and OneWeb drive strong growth through satellite internet projects, creating a robust commercial demand base. Government agencies continue to play a significant role, particularly in funding space exploration and scientific missions. Military users drive demand for secure communication and reconnaissance satellites. However, expanding commercial applications in telecommunication and imaging make commercial players the key growth engine in satellite manufacturing.
Key Growth Drivers
Rising Demand for Broadband Connectivity
The surge in global internet demand, particularly in underserved regions, is a major driver of satellite manufacturing. Companies are deploying large-scale low Earth orbit (LEO) constellations to deliver high-speed broadband with low latency. Increasing adoption of smart devices, digital services, and e-commerce is further fueling demand for improved connectivity. Governments and private players are investing in satellite internet projects to bridge digital divides, positioning broadband-focused satellite manufacturing as a critical growth enabler in both developed and emerging economies.
- For instance, Lockheed Martin is contracted to build 36 Transport Layer (T2TL) small data-comms satellites under the Space Development Agency, each supporting software-defined payloads and mesh network interconnects.
Government and Defense Investments
Government agencies and defense organizations continue to drive significant investments in satellite manufacturing. Defense demand includes secure communication, surveillance, reconnaissance, and navigation systems, while governments prioritize weather forecasting, disaster monitoring, and space exploration. National space programs are expanding, with countries like the U.S., China, and India leading satellite launches. These initiatives support domestic manufacturing capabilities and encourage collaboration with private players. As national security and scientific research remain critical, sustained government and defense expenditure creates a strong growth pillar for the satellite manufacturing industry.
- For instance, INVAP developed a series of secondary monopulse surveillance radars for civil air traffic control, which were deployed across Argentine airfields in compliance with ICAO standards. In defense systems, INVAP created the RPA-240T primary radar, featuring an instrumented detection range of 240 nautical miles, with units produced for national deployment.
Advancements in Satellite Technology
Technological innovation is reshaping the satellite manufacturing landscape. The development of small, lightweight satellites with higher efficiency and improved payload capacity reduces costs and increases deployment speed. Advancements such as electric propulsion, miniaturized components, and software-defined payloads enhance satellite flexibility and lifecycle performance. These improvements allow manufacturers to meet diverse requirements across communication, Earth observation, and navigation applications. Growing integration with emerging technologies, including artificial intelligence (AI) and 5G, further strengthens the value proposition, making innovation a core driver of market expansion.
Key Trends & Opportunities
Growth of Small Satellite Constellations
The increasing use of small satellite constellations is a prominent trend creating new opportunities. These satellites offer cost efficiency, faster production cycles, and scalable deployment, making them ideal for Earth observation, scientific research, and commercial communication. Companies are capitalizing on this trend to build global coverage networks. The rising interest of startups and private players further accelerates innovation, lowering barriers to entry. As demand for flexible and frequent launches rises, small satellite manufacturing provides a lucrative opportunity for both established and emerging industry participants.
- For instance, ISRO’s Small Satellite Launch Vehicle (SSLV) accommodates payloads from 10 kg up to 500 kg into a 500 km LEO orbit, enabling rapid deployment of small satellites.
Integration with Emerging Technologies
Satellite manufacturing is benefiting from integration with advanced technologies like artificial intelligence, machine learning, and 5G. AI-powered data analytics improves Earth observation efficiency, while 5G-enabled satellites enhance communication speed and connectivity. The use of digital twins and advanced simulation tools streamlines design and production processes, reducing development costs. These innovations create opportunities for manufacturers to deliver smarter, adaptable satellites that align with modern connectivity requirements. The synergy between satellites and terrestrial networks also strengthens long-term opportunities in commercial communication and data-driven industries.
- For instance, Saturn-400, scales power and payload for smarter missions it accommodates payloads up to 600 kg and supports scalable power up to 2 kW, with optional built-in Control Moment Gyroscope (CMG) for finer attitude agility.
Key Challenges
High Manufacturing and Launch Costs
Satellite manufacturing and deployment involve significant capital expenditure, posing a major challenge for market growth. High costs of advanced materials, testing facilities, and integration processes limit accessibility for smaller players and startups. Launch costs, though declining due to reusable rockets, still represent a substantial investment for satellite operators. This financial barrier slows innovation adoption and restricts participation to well-funded companies. Managing affordability while delivering advanced capabilities remains a pressing challenge for the industry.
Regulatory and Space Debris Concerns
The rapid increase in satellite launches raises regulatory and environmental challenges. Congested orbital paths heighten the risk of collisions and space debris, threatening both new and existing satellites. Regulatory frameworks differ across countries, creating complexities for global operators. Compliance with spectrum allocation, orbital slots, and international agreements adds to operational burdens. Without effective regulations and debris mitigation strategies, satellite sustainability faces risks. Addressing these challenges is critical for maintaining safe, reliable satellite manufacturing and deployment in the future.
Regional Analysis
North America
North America dominates the satellite manufacturing market with over 40% share, supported by strong government, defense, and commercial investments. The U.S. leads with its advanced space programs, spearheaded by NASA, the Department of Defense, and private firms such as SpaceX, Northrop Grumman, and Lockheed Martin. Growing demand for communication satellites, Earth observation systems, and national security applications drives the region’s leadership. Rising investments in broadband connectivity through low Earth orbit (LEO) constellations further strengthen market expansion. Canada also contributes with advancements in robotics and satellite imaging, reinforcing North America’s global leadership position.
Europe
Europe holds a market share of around 25%, driven by robust programs led by the European Space Agency (ESA) and national agencies. The region emphasizes scientific research, Earth observation, and sustainable satellite technologies. Countries such as France, Germany, and the UK lead manufacturing activities through key players like Airbus Defence and Space and Thales Alenia Space. Investments in navigation systems, including Galileo, enhance regional positioning. Growing demand for climate monitoring satellites aligns with Europe’s sustainability goals. The region also benefits from collaborative international projects, enabling steady growth across both governmental and commercial segments.
Asia Pacific
Asia Pacific accounts for nearly 22% share of the satellite manufacturing market, fueled by rapid advancements in China, India, and Japan. China leads with strong government-backed programs, large-scale LEO constellation projects, and investments in defense satellites. India’s ISRO continues to expand capabilities in cost-efficient satellite launches and Earth observation. Japan focuses on advanced imaging and communication systems, supported by Mitsubishi Electric and NEC. Rising demand for navigation and communication satellites in Southeast Asia further boosts growth. Urbanization, digital connectivity initiatives, and defense modernization make Asia Pacific the fastest-growing region in satellite manufacturing.
Latin America
Latin America captures a modest share of around 7%, with steady growth driven by increasing communication and Earth observation needs. Brazil leads the region with satellite programs focused on telecommunication, defense, and agricultural monitoring. Partnerships with global manufacturers and agencies support technology transfer and capacity building. Mexico, Argentina, and Chile also show growing interest in satellite-based services to improve connectivity and disaster management. Despite limited domestic manufacturing capabilities, the region benefits from rising demand for broadband expansion and environmental monitoring, creating opportunities for collaborations with established global players.
Middle East & Africa
The Middle East & Africa region holds approximately 6% share of the satellite manufacturing market, with growth supported by national security, telecommunication, and space exploration initiatives. Countries such as the UAE and Saudi Arabia are investing in indigenous satellite programs to enhance defense and commercial communication capacity. South Africa remains a key player in Africa, contributing through research and Earth observation projects. The growing demand for broadband connectivity in remote areas, coupled with increasing government-led space investments, is driving market expansion. Strategic collaborations with international manufacturers further accelerate technological adoption in the region.
Market Segmentations:
By Orbit:
- LEO (Low Earth Orbit)
- MEO (Medium Earth Orbit)
By Application:
- Earth observation
- Navigation
By End User:
- Military
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the satellite manufacturing market features key players such as EnduroSat, Boeing, Dhruva Space, BAE Systems, Lockheed Martin, INVAP, Beijing Smart Satellite, Airbus, Indian Space Research Organisation, and Blue Canyon Technologies. The satellite manufacturing market is highly competitive, driven by technological advancements, government investments, and growing commercial demand. Companies focus on developing cost-efficient, lightweight, and high-performance satellites to address the rising need for broadband connectivity, Earth observation, and navigation services. Increasing adoption of small satellite constellations and software-defined payloads intensifies competition, as players strive to offer flexible and scalable solutions. Strategic collaborations, mergers, and partnerships with space agencies and private operators are central to gaining market presence. The competitive environment continues to evolve with innovations in propulsion, miniaturization, and integration of artificial intelligence.
Key Player Analysis
- EnduroSat
- Boeing
- Dhruva Space
- BAE Systems
- Lockheed Martin
- INVAP
- Beijing Smart Satellite
- Airbus
- Indian Space Research Organisation
- Blue Canyon Technologies
Recent Developments
- In Oct 2024, SpaceX collaborated with OneWeb and launched 20 satellites for Eutelsat Group as a part of their first mission. The launch highlights a significant step for Eutelsat to expand its low earth orbit satellite communications network, which offers service for different telecommunication and broadcasting clients.
- In August 2024, Northrop Grumman launched the constellation of Arctic satellite broadband mission which is developed for space Norway. This signifies a historic partnership between the U.S. space force and space Norway. It's the first operational U.S. military payload worked on an international commercial space mission.
- In April 2024, Airbus SE announced that the EUTELSAT 36D telecommunications satellite built by the company was launched via a Falcon 9 rocket from the Kennedy Space Center in Florida, U.S. The satellite, part of the Eurostar Neo family, aimed to provide TV broadcasting and government services across Africa, Europe, and Eastern countries, with a planned operational lifetime exceeding 15 years.
- In December 2023, Thales Alenia Space and PT Len Industri signed a contract to deliver an advanced Earth observation system for the Indonesian Ministry of Defence. This system will combine radar and optical sensors in a satellite constellation. The two companies will work together to create a complete end-to-end solution, including both space and ground components in Indonesia.
Report Coverage
The research report offers an in-depth analysis based on Orbit, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for low Earth orbit constellations.
- Communication satellites will remain the dominant application segment.
- Governments will continue to invest heavily in defense and scientific missions.
- Commercial players will drive growth through broadband and imaging services.
- Small satellite manufacturing will increase due to cost and time efficiency.
- Advancements in propulsion and payload systems will enhance satellite performance.
- Integration with 5G and AI will strengthen future satellite applications.
- Regional players will emerge through national space programs and collaborations.
- Space sustainability measures will shape satellite design and deployment.
- Strategic partnerships will accelerate innovation and competitive positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Broadband Connectivity
The deployment of large-scale LEO satellite constellations is enabling high-speed, low-latency internet access in underserved and remote regions, driving significant investment and growth in satellite manufacturing.
Government and Defense Investments
National space programs and defense agencies are increasing funding for secure communications, surveillance, and navigation satellites, supporting domestic manufacturing and fostering public-private partnerships.
Advancements in Satellite Technology
Innovations such as electric propulsion, miniaturized components, and software-defined payloads are reducing costs, increasing satellite flexibility, and enabling faster deployment cycles, making satellite manufacturing more attractive and scalable.
Growth of Small Satellite Constellations
The trend toward small, cost-efficient satellites allows for rapid, scalable deployment and global coverage, attracting both established players and new entrants to invest in manufacturing capabilities.
Integration with Emerging Technologies
The adoption of AI, machine learning, and 5G in satellite systems is enhancing data processing, connectivity, and operational efficiency, creating new applications and expanding the market’s value proposition.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Satellite Manufacturing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Satellite Manufacturing Market projected to grow between 2025 and 2032?
Which Satellite Manufacturing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Satellite Manufacturing Market?
Who are the leading companies in the Satellite Manufacturing Market?
Which region commanded the largest share of the Satellite Manufacturing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Orbit
- 1.2.1 Low Earth Orbit (LEO)
- 1.2.2 Medium Earth Orbit (MEO)
- 1.2.3 Geostationary Earth Orbit (GEO)
- 1.3 By End User
- 1.3.1 Commercial
- 1.3.2 Government
- 1.3.3 Military
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Communication
- 1.4.2 Earth Observation
- 1.4.3 Navigation
- 1.4.4 Scientific Research
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 22.57 billion → 2032: USD 74.01 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Satellite Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Satellite Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Satellite Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Satellite Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Satellite Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Satellite Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Satellite Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Satellite Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 22.57 billion → 2032: USD 74.01 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Satellite Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Orbit - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Low Earth Orbit (LEO)
- 12.3.7.2 Medium Earth Orbit (MEO)
- 12.3.7.3 Geostationary Earth Orbit (GEO)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial
- 12.4.7.2 Government
- 12.4.7.3 Military
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Communication
- 12.5.7.2 Earth Observation
- 12.5.7.3 Navigation
- 12.5.7.4 Scientific Research
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Satellite Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Satellite Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Satellite Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Satellite Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Airbus
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Boeing
- 18.4 Lockheed Martin
- 18.5 BAE Systems
- 18.6 Blue Canyon Technologies
- 18.7 Dhruva Space
- 18.8 EnduroSat
- 18.9 INVAP
- 18.10 Beijing Smart Satellite
- 18.11 Indian Space Research Organisation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

