
Market Overview:
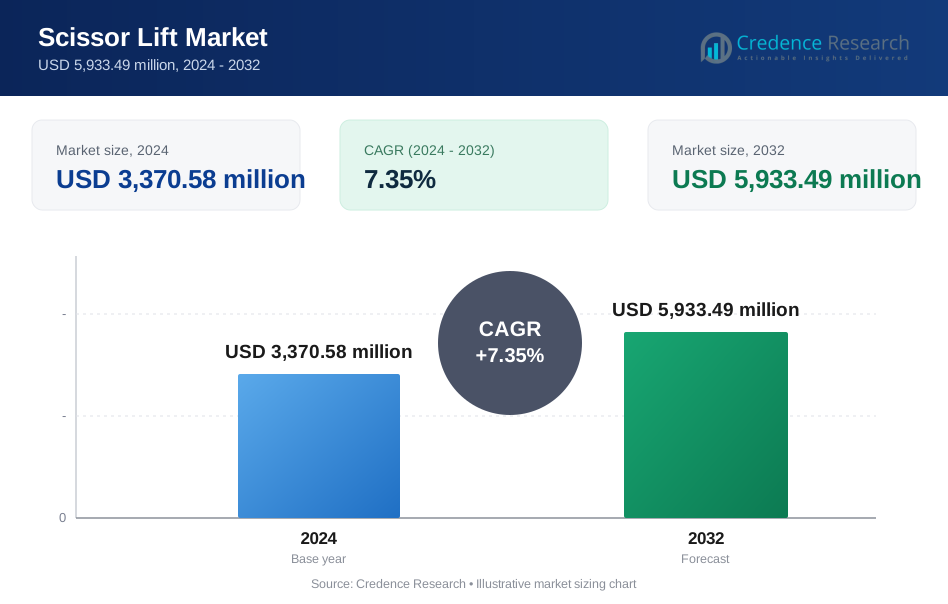
The Scissor Lift Market size was valued at USD 2,600.00 million in 2018 to USD 3,370.58 million in 2024 and is anticipated to reach USD 5,933.49 million by 2032, at a CAGR of 7.35% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Scissor Lift Market Size 2024 | USD 3,370.58 Million |
| Scissor Lift Market, CAGR | 7.35% |
| Scissor Lift Market Size 2032 | USD 5,933.49 Million |
Rising demand for safe and efficient aerial access solutions drives market growth across industrial and commercial sectors. Scissor lifts are increasingly used in construction, warehousing, logistics, and facility maintenance due to their stability and vertical reach. Electric-powered models gain popularity for indoor applications, supporting emission regulations and compact operational needs. Growing infrastructure projects, rising worker safety regulations, and rental fleet expansion contribute to rising adoption. Manufacturers focus on lightweight, maneuverable models to meet varied site requirements.
North America leads the global scissor lift market due to widespread rental adoption, strict safety norms, and strong construction activity. Europe follows with stable demand from renovation projects and eco-friendly equipment preference. Asia Pacific emerges as the fastest-growing region, driven by rapid urbanization, infrastructure development, and industrial automation. China, India, and Southeast Asia contribute significantly due to expanding logistics, warehousing, and smart city projects. Latin America, the Middle East, and Africa show early growth potential supported by public investment and improving safety awareness.

Market Insights:
- The Scissor Lift Market was valued at USD 2,600.00 million in 2018, USD 3,370.58 million in 2024, and is projected to reach USD 5,933.49 million by 2032, growing at 7.35% during the forecast period.
- In 2024, North America led with a 35.35% share, followed by Asia Pacific at 29.83% and Europe at 23.30%, driven by construction activity, rental fleet penetration, and safety regulations.
- Asia Pacific is the fastest-growing region with a 29.83% share, supported by rapid urbanization, infrastructure development, and industrial expansion across China, India, and Southeast Asia.
- The 10–20m lift height segment captured the largest market share in 2024 due to its versatile application in commercial and industrial zones.
- Electric engine type accounted for over 60% of the market in 2024, driven by indoor usage, emission compliance, and increasing demand from warehousing and retail sectors.
Market Drivers
Rising Construction and Infrastructure Development Activities Across Urban and Industrial Zones
Rapid growth in real estate and infrastructure boosts the demand for aerial access equipment. Urban construction requires vertical lifting solutions for façade work, glass installation, and electrical setups. Scissor lifts offer stable platforms for height-based tasks in compact city sites. Contractors prefer electric models in low-emission zones. Industrial zones use them for facility upgrades, safety checks, and maintenance. The Scissor Lift Market benefits from growing smart city projects and warehouse automation. Developers favor scissor lifts for time-saving and reduced labor risk. Rental firms expand inventories to meet rising site demands. Investment in public and private infrastructure supports long-term growth.
- For instance, Genie’s GS-3246 E-Drive electric scissor lift delivers a 38 ft 1 in (11.78 m) working height and a 700 lb (318 kg) platform capacity, offering efficient two-person access for elevated tasks in space-constrained urban job sites.
Stringent Worker Safety Regulations Driving Equipment Upgrades and Fleet Compliance
Governments and industry regulators mandate safe working-at-height solutions. Employers choose scissor lifts to reduce fall risks and meet occupational safety codes. Regular inspections, certifications, and training promote compliant equipment usage. Insurance firms require certified platforms for high-risk zones. Legacy machines face replacement to meet evolving safety norms. Newer scissor lifts feature safety interlocks, tilt sensors, and overload cut-offs. The Scissor Lift Market grows as companies adopt safety-centric equipment. Construction, aviation, and utilities sectors lead compliance-driven purchases. Manufacturers focus on regulatory alignment to sustain demand.
Growing Adoption of Electric and Battery-Powered Models for Indoor and Eco-Zone Usage
Electrification trends reshape preferences in aerial work platforms. Battery-powered scissor lifts replace diesel variants in warehouses, hospitals, and retail stores. Low noise and zero emissions support use in populated zones. Charging convenience and lower operational costs enhance fleet adoption. Models with lithium-ion batteries provide longer cycles and fast recharge. Users value smooth operations in noise-sensitive environments. The Scissor Lift Market witnesses higher demand for compact electric variants. Rental providers prefer battery-powered lifts to access indoor projects. Sustainability commitments drive purchase decisions across multiple sectors.
- For instance, Skyjack’s SJIII 3219 electric scissor lift delivers a 25 ft 6 in working height with a 272 kg platform capacity, commonly used in indoor applications like warehousing and maintenance, supported by lead-acid batteries for standard-duty cycles.
Increased Use in Maintenance, Repair, and Overhaul (MRO) Applications Across Industries
Scissor lifts find expanding use beyond construction sites. Manufacturing units use them for lighting, duct, and conveyor maintenance. Airports, malls, and public buildings rely on them for interior access. Scheduled maintenance in telecom and utility poles requires safe elevation. Railways and metro networks deploy scissor lifts for structural checks. Regular facility upkeep supports year-round deployment across industries. The Scissor Lift Market gains from non-seasonal demand across MRO sectors. Compact, mobile units with precise elevation control suit indoor servicing. Long-term service contracts drive repeat procurement and upgrades.
Market Trends
Integration of Smart Control Systems and Remote Diagnostics in Modern Lift Platforms
Manufacturers equip scissor lifts with digital control systems for safer and smarter operation. Remote monitoring tools track machine usage, battery levels, and fault alerts. Fleet managers use telematics to schedule servicing and prevent downtime. Touchscreen dashboards improve operator feedback and efficiency. Predictive maintenance tools reduce breakdowns and improve asset life. OEMs partner with software firms to offer IoT-enabled systems. The Scissor Lift Market benefits from rising demand for intelligent fleet oversight. Connected platforms enhance performance, reduce accidents, and lower ownership cost. End-users prefer digital-ready units for better lifecycle management.
- For instance, Genie Industries' GS-4046 scissor lift features Smart Link dual-zone controls, enabling indoor and outdoor use with a 25% gradeability and travel speed up to 1.9 mph for enhanced maneuverability.
Rental Market Expansion Fueling Shift Toward Short-Term Equipment Access Over Ownership
Rising project-based work encourages firms to lease equipment rather than own fleets. Rental players maintain large inventories of scissor lifts with regular maintenance. Contractors prefer rentals to avoid capital lock-in and maintenance hassles. Seasonal projects like stadium setups or event stages also support rental demand. OEMs supply rental fleets with rugged and low-maintenance models. The Scissor Lift Market expands through rental growth in Asia, Europe, and North America. Digital rental platforms simplify booking, tracking, and usage monitoring. Rental flexibility allows businesses to scale resources based on project needs. Fleet renewal cycles stay active through rental-based procurement.
Demand for Compact and Narrow-Aisle Scissor Lifts Suited for Confined Urban and Indoor Spaces
Urban job sites face access restrictions and height constraints. Compact scissor lifts fit into elevators, corridors, and narrow service spaces. Retail chains, hospitals, and museums need quiet and space-saving lifts. Lightweight models reduce floor load risks in multi-level structures. Operators seek portable options with quick setup features. Small platform lifts support low-height applications under 20 feet. The Scissor Lift Market sees higher demand for indoor-use scissor lifts. OEMs design compact chassis with tight turning radii for agile movement. Narrow-body lifts support growing use in maintenance and light construction.
- For instance, JLG’s ES1930M narrow-aisle electric scissor lift offers a 30-inch width, 18.6-foot platform height, and zero inside turning radius, enabling precise maneuverability in congested indoor environments such as warehouses and retail spaces.
Emerging Use of Hybrid Power Systems for Dual Indoor-Outdoor Applications Across Sites
Hybrid scissor lifts combine electric drive with optional engine-based charging. They operate in indoor settings on battery and switch to diesel in open sites. Dual mode offers flexibility across project zones without switching equipment. Construction firms benefit from reduced machine transfers between phases. Power source selection improves compliance and operational cost control. OEMs offer hybrid lines with regenerative braking and charge monitoring. The Scissor Lift Market gains traction for dual-use platforms in complex sites. Customers seek flexibility without compromising safety or runtime. Hybrid models reduce rental downtime and improve fleet utilization.
Market Challenges Analysis
High Initial Investment and Cost of Ownership Restricting Adoption Among Small Contractors and SMEs
Many small businesses hesitate to adopt scissor lifts due to high purchase costs. Capital investment for electric or hybrid models exceeds manual lifting tools. Budget-constrained contractors favor rentals, limiting direct equipment sales. Maintenance costs and battery replacements further increase ownership burden. Lack of trained operators adds hiring and training expenses. SMEs often delay modernization due to uncertain project pipelines. The Scissor Lift Market faces slower penetration in small-scale construction. OEMs address this gap by offering entry-level models and flexible financing. Cost-effective ownership remains a key adoption barrier in price-sensitive regions.
Supply Chain Delays and Component Shortages Affecting Production and Delivery Schedules
Raw material price volatility and component shortages disrupt manufacturing timelines. Battery cells, sensors, and electronic controls face frequent delays. Global shipping congestion slows international supply of key subassemblies. Lead times stretch across OEMs and rental fleets alike. Delivery gaps affect project planning and seasonal equipment availability. The Scissor Lift Market experiences fluctuation in new unit rollouts. Distributors manage inventories cautiously due to supply uncertainty. Inflation in logistics and components raises product pricing. Stabilizing procurement cycles remains critical to meeting rising demand.

Market Opportunities
Rising Infrastructure Investments in Emerging Economies Creating Demand for Vertical Access Solutions
Urbanization and industrial expansion in Asia-Pacific, Latin America, and Africa boost lift demand. Governments fund airport upgrades, housing, and smart city programs. New logistics parks and manufacturing units require height access platforms. The Scissor Lift Market benefits from low equipment penetration in emerging regions. OEMs expand into Tier 2 cities through dealer networks. Local assembly hubs improve product availability and cost competitiveness. Growing construction momentum supports multi-year demand visibility.
Technological Advancements in Lightweight Materials and Design Optimization for Indoor Use
OEMs innovate using aluminum alloys and modular chassis to reduce weight. Compact lifts with high lift-to-weight ratios improve indoor usability. Foldable guardrails and low stowed heights support storage in tight spaces. The Scissor Lift Market sees faster adoption of user-friendly designs. Improved portability expands use in hospitals, schools, and data centers. Design focus shifts toward operator safety, agility, and low emissions. These advancements help broaden end-user base across indoor service sectors.
Market Segmentation Analysis:
By engine type, electric scissor lifts dominate due to rising indoor applications, low noise, and zero emissions. Warehouses, retail outlets, and healthcare facilities prefer battery-powered lifts for safe, clean environments. Engine-powered lifts remain essential for outdoor construction and rugged terrain, offering higher power and mobility in open job sites. The Scissor Lift Market benefits from parallel demand across both segments, driven by varying operational needs.
- For example, JLG 4069LE achieves 14.02 m (46 ft) working height and 363 kg (800 lb) platform capacity, confirmed across JLG spec sheets and dealer sites. Engine-powered: Skyjack 6832 offers 50% gradeability and 454 kg capacity, matching official rough-terrain diesel specs.
By type, the 10–20m segment leads due to its flexibility across industrial and commercial use. It fits well in multi-story buildings and large warehouses. Units under 10m suit indoor facilities with height limitations, such as showrooms and retail spaces. Lifts above 20m support complex infrastructure projects requiring extended vertical reach. Manufacturers focus on expanding the 10–20m range due to balanced demand across sectors.
By end-use, construction is the largest segment due to the sector's consistent height-access needs. It drives high demand for both electric and engine-powered units. Retail, storage, and warehouse applications follow closely, with e-commerce growth pushing adoption of compact models. Transportation and logistics use lifts for equipment handling and facility maintenance. Other sectors, including public infrastructure and utilities, contribute through repair, inspection, and facility operations. The Scissor Lift Market sees robust growth across all segments, supported by varied operational requirements and site-specific preferences.
- For example, Genie GS-5390 RT reaches 18.15 m working height and 680 kg capacity for construction, verified in rental specifications. Skyjack SJIII 3215 supports 272 kg (600 lb) at full height drive for warehouses. Haulotte HS21 E attains 21 m height with 750 kg load for infrastructure.
Segmentation:
By Engine Type
- Electric
- Engine-Powered
By Type
- <10m
- 10–20m
- 20m
By End-Use
- Construction
- Retail, Storage and Warehouses
- Transportation and Logistics
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Scissor Lift Market size was valued at USD 930.80 million in 2018 to USD 1,191.82 million in 2024 and is anticipated to reach USD 2,095.13 million by 2032, at a CAGR of 7.4% during the forecast period. It holds the largest regional share of 35.35% in 2024. High construction activity, stringent safety norms, and widespread adoption of rental models support market growth. The U.S. leads with demand from urban infrastructure, industrial maintenance, and logistics facilities. Canada contributes through rising construction investments and energy projects. Equipment rental firms expand fleets with electric and hybrid models. Regulatory agencies push adoption of low-emission lifts in indoor and public zones. High penetration across retail and warehousing also drives repeat demand. Strong aftermarket and service infrastructure further strengthen growth momentum.
Europe
The Europe Scissor Lift Market size was valued at USD 632.32 million in 2018 to USD 785.25 million in 2024 and is anticipated to reach USD 1,299.15 million by 2032, at a CAGR of 6.5% during the forecast period. It accounts for 23.30% of the global market share in 2024. Market expansion is supported by retrofitting of buildings, airport upgrades, and smart city projects. Countries such as Germany, the UK, and France drive adoption through strict worker safety laws. Demand rises for low-noise, battery-powered models for use in urban spaces and historical structures. Rental operators modernize fleets with digital control systems and compact platforms. Strong presence of OEMs and suppliers supports fast availability and servicing. Sustainability goals push for energy-efficient lift variants. Growing logistics and e-commerce warehouses create new demand pockets.
Asia Pacific
The Asia Pacific Scissor Lift Market size was valued at USD 747.76 million in 2018 to USD 1,005.94 million in 2024 and is anticipated to reach USD 1,927.80 million by 2032, at a CAGR of 8.5% during the forecast period. It holds a 29.83% market share in 2024. Rapid urban development, infrastructure upgrades, and industrial automation fuel demand. China leads the region with government-backed real estate and manufacturing projects. India follows with growth in airports, metros, and commercial construction. Southeast Asia emerges through demand from logistics hubs and retail growth. OEMs localize manufacturing to offer cost-effective models. Rising labor safety awareness in emerging economies supports adoption. Fleet rental models gain popularity among contractors with short-term needs. Overall, the Scissor Lift Market in the region shows robust long-term prospects.
Latin America
The Latin America Scissor Lift Market size was valued at USD 176.80 million in 2018 to USD 227.14 million in 2024 and is anticipated to reach USD 373.04 million by 2032, at a CAGR of 6.4% during the forecast period. It contributes 6.73% of the global market share in 2024. Brazil and Mexico are the key growth drivers with expanding logistics networks and commercial zones. Infrastructure modernization and public sector investments stimulate demand. Engine-powered lifts dominate in outdoor, rugged environments. Urban safety regulations in select cities drive electric lift demand for indoor use. Import dependency challenges local availability and pricing. Rental market expansion supports equipment access for small contractors. OEM partnerships with local distributors improve reach and after-sales support.
Middle East
The Middle East Scissor Lift Market size was valued at USD 80.60 million in 2018 to USD 96.38 million in 2024 and is anticipated to reach USD 148.96 million by 2032, at a CAGR of 5.6% during the forecast period. It holds 2.86% of the global market share in 2024. Construction megaprojects in Saudi Arabia, UAE, and Qatar boost demand. Scissor lifts are used in stadiums, commercial buildings, and urban redevelopment zones. Preference rises for rugged engine-powered models suited to harsh outdoor conditions. Indoor projects in malls, airports, and healthcare demand compact electric variants. The region sees increasing interest in fleet rental and digital-enabled access platforms. OEMs partner with regional rental players to address demand spikes. Regulatory shifts toward safer construction practices improve adoption.
Africa
The Africa Scissor Lift Market size was valued at USD 31.72 million in 2018 to USD 64.05 million in 2024 and is anticipated to reach USD 89.41 million by 2032, at a CAGR of 3.6% during the forecast period. It accounts for 1.90% of the global market share in 2024. Infrastructure development in South Africa, Nigeria, and Kenya drives early-stage adoption. Growth remains limited by high equipment costs and limited financing options. Local demand focuses on durable, engine-powered lifts for construction and mining. Indoor lift demand is rising in airports, malls, and logistics parks. Awareness of worker safety regulations grows slowly but steadily. Import reliance and low rental penetration constrain wider market reach. Multinational OEMs test pilot projects through aid-funded infrastructure zones. The Scissor Lift Market in Africa shows gradual expansion with potential for long-term scaling.
Key Player Analysis:
- Terex Corporation
- Manitou Group
- JLG Industries
- Galmon (S) Pte Ltd
- Aichi Corporation
- EdmoLift AB
- Haulotte Group
- Wiese USA
- Linamar Corporation
- Advance Lifts, Inc.
- LGMG North America, Inc.
- Shandong Qiyun Group Co., Ltd.
Competitive Analysis:
The Scissor Lift Market shows strong competition among global OEMs and regional manufacturers. Large players compete through broad product portfolios, rental partnerships, and strong dealer networks. Companies focus on electric and hybrid models to meet safety and emission rules. Product reliability, platform stability, and lifecycle cost shape buyer decisions. Innovation centers on smart controls, telematics, and battery performance. It supports fleet efficiency and uptime for rental operators. Price competition remains high in entry-level segments, especially in emerging regions. Established brands protect share through aftersales service and parts availability. Regional players compete on cost and customization for local needs. Strategic moves include capacity expansion, regional assembly, and new model launches. Partnerships with rental firms strengthen recurring demand. Competitive intensity remains moderate to high across developed and developing markets.

Recent Developments:
- In April 2025, JLG Industries launched the ES1930M micro-sized electric scissor lift, designed for compact maneuverability in congested job sites with lightweight structure.
- In March 2025, Aichi Corporation formed a capital and business alliance with ITOCHU Corporation, where ITOCHU acquired a 27% stake to expand Aichi's aerial work platforms, including scissor lifts, through new maintenance, leasing, and global market strategies.
- In February 2025, Manitou Group entered the North American scissor lift market by launching two electric models with 24- and 32-foot platform heights, built in India for indoor/outdoor use in construction and maintenance.
Report Coverage:
The research report offers an in-depth analysis based on Engine Type, Type and End-Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Urban infrastructure expansion will sustain demand for compact and mid-height scissor lifts across commercial and residential construction projects.
- Warehouse automation and e-commerce facility growth will increase use of electric scissor lifts for indoor material handling operations.
- Rental penetration will rise as contractors prefer flexible access to equipment without long-term ownership commitments.
- Product development will focus on lightweight designs that improve mobility, transport efficiency, and indoor usability.
- Battery technology improvements will enhance runtime, charging speed, and overall productivity of electric scissor lifts.
- Safety-focused features such as load sensors and smart controls will gain importance across regulated job sites.
- Asia Pacific will remain a key growth engine due to infrastructure spending and manufacturing expansion.
- OEMs will expand regional assembly and distribution to reduce costs and improve delivery timelines.
- Digital fleet management tools will support predictive maintenance and higher equipment utilization rates.
- Diverse end-use adoption will stabilize demand cycles and reduce dependency on single industry segments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Scissor Lift Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Scissor Lift Market projected to grow between 2024 and 2032?
Which Scissor Lift Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Scissor Lift Market?
Who are the leading companies in the Scissor Lift Market?
Which region commanded the largest share of the Scissor Lift Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Scissor Lift Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Scissor Lift Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,370.58 million → 2032: USD 5,933.49 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Scissor Lift Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Scissor Lift Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Scissor Lift Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Scissor Lift Market Drivers
- 3.3 Scissor Lift Market Restraints & Challenges
- 3.4 Scissor Lift Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Scissor Lift Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Scissor Lift Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Scissor Lift category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Scissor Lift Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Scissor Lift Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Scissor Lift market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Scissor Lift Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Scissor Lift Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Scissor Lift Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Scissor Lift (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Scissor Lift Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Scissor Lift Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Scissor Lift Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Scissor Lift Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Scissor Lift Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Scissor Lift Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Scissor Lift Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Scissor Lift Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Scissor Lift Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
