
Market Overview
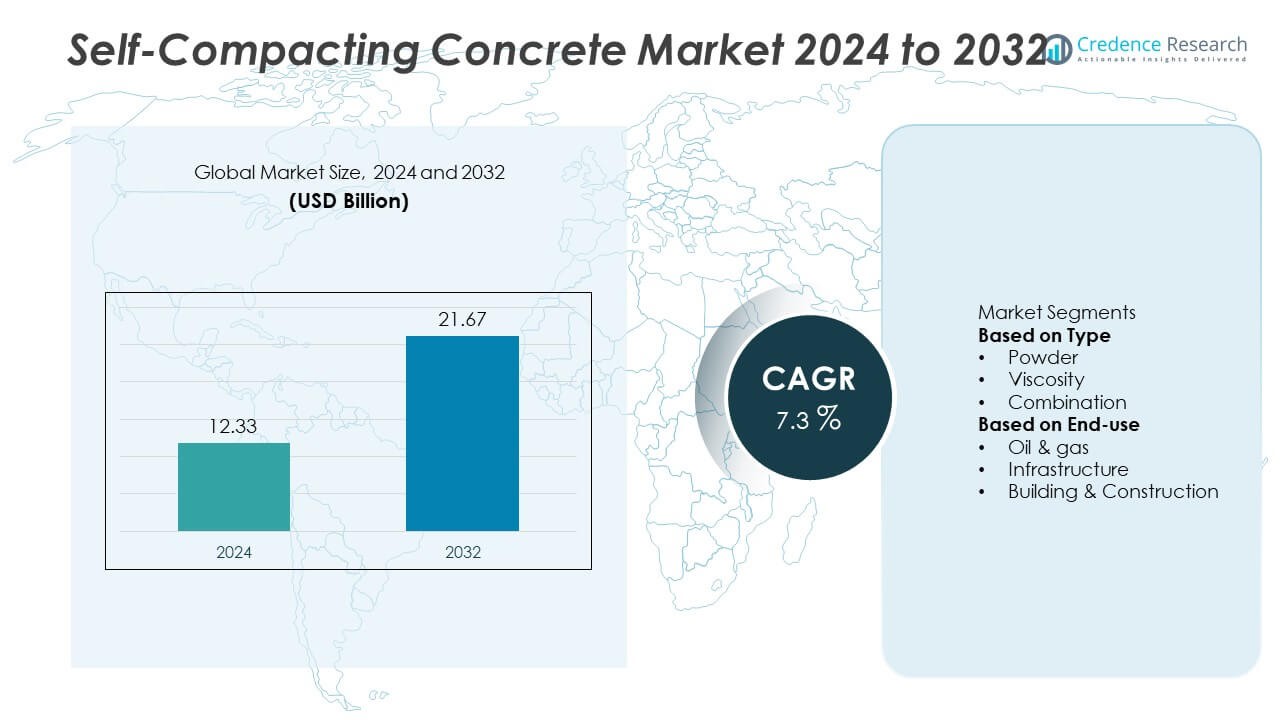
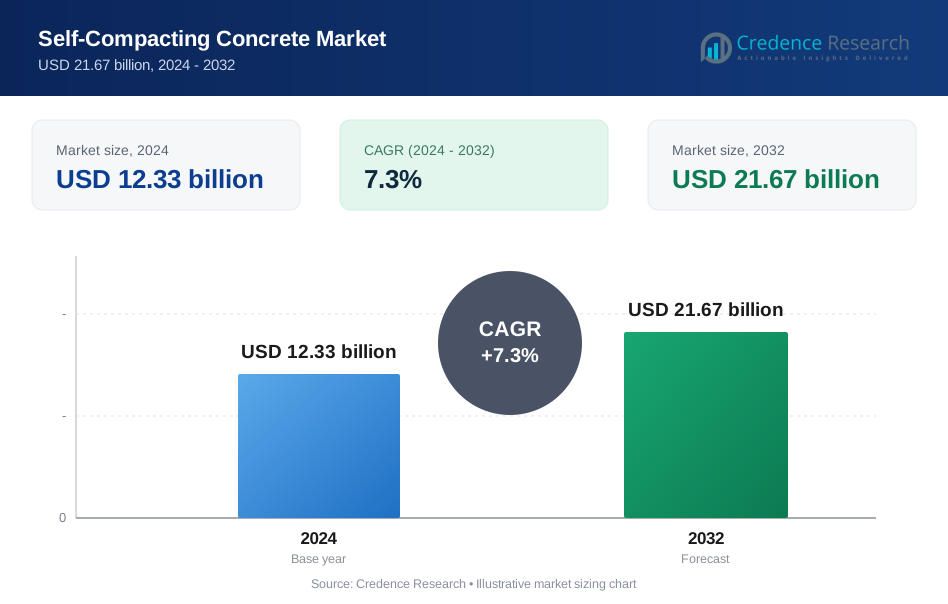
The Self-Compacting Concrete market was valued at USD 12.33 billion in 2024 and is projected to reach USD 21.67 billion by 2032, growing at a CAGR of 7.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Self-Compacting Concrete Market Size 2024 | USD 12.33 Billion |
| Self-Compacting Concrete Market, CAGR | 7.3% |
| Self-Compacting Concrete Market Size 2032 | USD 21.67 Billion |
The top players in the Self‑Compacting Concrete market-BASF SE, CEMEX S.A.B. de C.V., ACC Limited, SIKA AG, and LafargeHolcim-sharpen their competitive edge through advanced admixture solutions, global production reach, and tailored mix designs. Meanwhile, the Asia Pacific region leads the market with a 45.8% share in 2024, propelled by large-scale urbanization and infrastructure growth in China, India and Southeast Asia. These companies leverage regional strengths, such as efficient supply chains and local standards compliance, to reinforce their leadership and drive sustained growth in the high-performance concrete sector.
Market Insights
- The global self‑compacting concrete market stood at USD 12.33 billion in 2024 and is expected to grow at a CAGR of 7.3%.
- Rising demand for high‑efficiency and high‑quality concrete solutions in urban infrastructure drives market growth, especially in high‑rise and complex structures.
- Increased adoption of automatic placement technologies and improved mix designs supports growth; the combination type holds about 60% of the Type segment, while the Building & Construction end‑use segment holds 45%.
- Competitive dynamics feature major players such as BASF SE, CEMEX S.A.B. de C.V., ACC Limited and SIKA AG, leveraging global networks and innovation to gain advantage, while smaller local firms focus on cost‑led strategies.
- Regionally, Asia Pacific commands a 45.8% share of the global market, followed by North America at 24% and Europe at 18%, driven by strong infrastructure development and urbanization trends.
Market Segmentation Analysis:
By Type
In the Self-Compacting Concrete market, the Combination type leads with a 60% market share due to its balanced mix of powder and viscosity-modifying agents that enhance flowability and stability. This type is preferred in projects with dense reinforcement and complex formwork because it eliminates the need for vibration and improves placement quality. The Powder type holds 25%, supported by strong demand in applications requiring high strength and smooth finishes. The Viscosity type accounts for the remaining 15%, mainly serving specialized projects. Growth is driven by the rising focus on labor efficiency and durable structural performance.
- For instance, the Sika ViscoFlow® series is tailored for projects requiring enhanced workability and extended slump retention in varying environmental conditions, including both hot and cold weather, and is recommended for use in high-precision applications such as tunnel linings and precast elements.
By End-Use
The Building & Construction segment dominates with a 45% market share, driven by rapid urban development, high-rise construction, and the need for superior concrete finishes. SCC is widely used in slabs, walls, and foundations due to its ease of placement and reduced labor requirements. The Infrastructure segment follows with 35%, supported by extensive use of SCC in bridges, tunnels, and metro systems where complex formwork and durability are essential. The Oil & Gas segment holds 20%, using SCC for offshore platforms and heavy-duty foundations. Growth across all segments is fueled by stricter standards for structural quality and faster construction timelines.
- For instance, Saudi Aramco utilizes nonmetallic materials, such as Glass Fiber Reinforced Polymer (GFRP) rebars and Reinforced Thermoplastic Pipes (RTP), in its construction projects, including in building and construction applications and pipelines in offshore and high-humidity areas, to ensure enhanced durability and corrosion resistance.
Key Growth Drivers
Growing Demand for Sustainable Construction
The increasing emphasis on sustainable construction practices is a significant driver for the Self-Compacting Concrete market. SCC reduces the need for vibration, resulting in less energy consumption and reduced labor costs. Its use in high-rise buildings and infrastructure projects contributes to higher construction quality and fewer defects, which aligns with the global push for more efficient and eco-friendly construction practices. The growing trend of using low-carbon concrete and the adoption of sustainable building materials are further fueling demand for SCC.
- For instance, the Holcim Group (formerly LafargeHolcim) supplied its Agilia Light Weight self-compacting concrete during the extensive renovation of the Mandarin Oriental Ritz hotel in Madrid, Spain. This project achieved a high-quality finish using advanced concrete solutions promoted for their efficiency and performance.
Technological Advancements in Concrete Production
Advancements in concrete production technologies have played a crucial role in the growth of the Self-Compacting Concrete market. Innovations in mix design and the integration of advanced additives have improved SCC’s workability, durability, and performance, making it a preferred choice in challenging construction environments. These technological improvements enable SCC to be used in a broader range of applications, including complex structures, which has accelerated its adoption in infrastructure, residential, and commercial projects.
- For instance, SIKA’s use of advanced polycarboxylate ether-based admixtures has enhanced SCC’s durability, resulting in fewer repairs and longer service life for buildings exposed to harsh weather conditions.
Urbanization and Infrastructure Development
Rapid urbanization and ongoing infrastructure development are key factors driving the demand for Self-Compacting Concrete. As cities grow, the need for high-quality, durable, and efficient construction materials becomes more critical. SCC, with its ability to be used in densely reinforced structures, urban housing, and complex forms, has gained widespread acceptance. Additionally, infrastructure projects such as bridges, highways, and tunnels require materials that offer long-term strength and ease of use, boosting the demand for SCC in these sectors.
Key Trends & Opportunities
Rise in Smart Construction Practices
The rise of smart construction practices and the integration of automation in building processes present an opportunity for the Self-Compacting Concrete market. As construction methods evolve, there is a growing shift towards minimizing manual labor while ensuring high precision. SCC, being a self-leveling and self-compacting material, fits perfectly with the increasing adoption of automated and robotic construction technologies. The trend towards smart construction is likely to further boost SCC’s demand, especially in large-scale infrastructure and residential projects.
- For instance, researchers and construction tech companies are actively developing automated robotic systems for highly accurate concrete placement in various construction scenarios, from 3D printed facades to flat floor finishing. These innovations aim to reduce labor costs, increase construction speed, and improve precision in the overall building process.
Adoption of Green Building Certifications
The growing focus on green building certifications, such as LEED (Leadership in Energy and Environmental Design), presents a significant opportunity for the Self-Compacting Concrete market. As sustainability becomes a key priority in construction, the use of environmentally friendly materials like SCC, which reduces energy consumption and waste during construction, becomes more desirable. The adoption of green building standards by governments and private developers is driving the shift towards using sustainable materials, offering substantial growth prospects for SCC.
- For instance, Turner Construction's use of innovative low-carbon concrete solutions in the development of energy-efficient commercial buildings has contributed to meeting LEED Platinum standards, ensuring reduced carbon footprints throughout the building's life cycle.
Key Challenges
High Cost of Self-Compacting Concrete
Despite its advantages, the high cost of Self-Compacting Concrete remains a key challenge in its widespread adoption. The production of SCC requires advanced raw materials, additives, and specialized mixing processes, which makes it more expensive than traditional concrete. This cost barrier limits its adoption, particularly in price-sensitive markets and small-scale projects. However, as production processes improve and economies of scale come into play, the cost of SCC may become more competitive in the future.
Lack of Skilled Workforce
Another challenge for the Self-Compacting Concrete market is the lack of skilled workforce capable of handling the advanced production, application, and finishing techniques associated with SCC. Properly mixing and placing SCC requires technical expertise to ensure its optimal performance. The shortage of trained professionals in construction and concrete-related fields can hinder the effective use of SCC, especially in regions with limited access to specialized training programs. This gap in skill development could slow the adoption of SCC in certain markets.
Regional Analysis
Asia Pacific
The Asia Pacific region commanded a market share of 45.8% in the self‑compacting concrete market in 2024. Rapid urbanization and robust infrastructure development in countries such as China, India, and Southeast Asian economies drove demand for high‑quality, labour‑efficient concrete solutions. The presence of large residential and commercial construction projects and government investment in transport and industrial facilities further boosted uptake. Growing preference for materials that simplify complex formwork and reduce vibration requirements supported the region’s dominance and established it as the primary growth engine.
North America
North America held a market share of 24% in 2024 for self‑compacting concrete. Mature construction markets in the US and Canada, combined with the rise of modular and precast building techniques, fostered strong demand. Stringent building codes and a focus on sustainability encouraged use of SCC in commercial and heavy‑civil applications. Manufacturers and contractors increasingly incorporated SCC to reduce labour input and improve finish quality, supporting steady expansion in this region’s market.
Europe
Europe represented a 18% share of the global self‑compacting concrete market in 2024. The region’s long‑standing emphasis on durable infrastructure, high‑rise buildings, and green construction standards supported adoption. Countries like Germany, France, Italy and the UK leveraged SCC for premium architectural projects and densely reinforced structures. Regulatory focus on construction quality and efficiency further incentivised use of SCC, enabling Europe to maintain its strong position despite competition from emerging markets.
Latin America
Latin America accounted for 9% of the self‑compacting concrete market in 2024. Countries such as Brazil, Mexico and Chile drove demand through growing residential and commercial construction as well as export‑oriented horticulture and infrastructure projects. Challenges like varying industrial capacity and investment levels influenced growth, yet the region offered tangible potential as contractors shifted toward higher‑efficiency materials and sought lower‑labour, quality‑enhancing solutions.
Middle East & Africa
The Middle East & Africa region captured a market share of 8% in 2024 for self‑compacting concrete. Arid climates and infrastructure‑intensive economies such as Saudi Arabia, UAE and South Africa adopted SCC to cope with complex formwork and large‑scale construction demands. Public investment in urban development and industrial hubs propelled uptake. Despite regional disparities in infrastructure and construction expertise, the push for sustainable and high‑end materials created notable growth opportunities in the region.
Market Segmentations:
By Type
- Powder
- Viscosity
- Combination
By End-use
- Oil & gas
- Infrastructure
- Building & Construction
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the self‑compacting concrete market features major players such as BASF SE, CEMEX S.A.B. de C.V., ACC Limited, SIKA AG, LafargeHolcim, Kilsaran, HeidelbergCement AG, Tarmac, Unibeton Ready Mix and UltraTech Concrete. These companies maintain strong positions by leveraging extensive product portfolios, global supply chains and strategic partnerships to meet demand for high‑performance concrete solutions. They focus on developing admixtures and formulations tailored for self‑compacting applications, investing in research and innovation to enhance flowability, strength and sustainability. Regional manufacturers compete by offering cost‑effective local solutions, while global firms benefit from scale and brand credibility. With adoption growing in infrastructure and high‑rise construction, differentiation increasingly relies on sustainability credentials and product performance rather than price alone.
Key Player Analysis
- LafargeHolcim
- BASF SE
- ACC Limited
- Ultratech Concrete
- SIKA AG
- HEIDELBERGCEMENT AG
- Unibeton Ready Mix
- Tarmac
- CEMEX S.A.B. de C.V
- Kilsaran
Recent Developments
- In July 2025, HEIDELBERGCEMENT AG (operating as Heidelberg Materials) launched an industrial‑scale facility in Poland for enforced carbonation of concrete, supporting performance enhancements in SCC mixes through carbon‑cured concrete technology.
- In May 2025, BASF SE introduced Pluriol® A 2400 I in Europe, a reactive polyethylene glycol designed for third‑generation superplasticisers used in concrete including SCC applications.
Report Coverage
The research report offers an in-depth analysis based on Type, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing urbanization will drive greater use of self‑compacting concrete in high‑rise and dense‑build environments.
- Stricter building codes and sustainability regulations will elevate demand for advanced self‑compacting mixes.
- Technological improvements in admixtures and mix design will enhance performance and reduce cost of SCC.
- Growth in infrastructure investment will accelerate adoption of self‑compacting concrete in bridges, tunnels and airports.
- Rising demand for retrofit and refurbishment projects will push use of self‑compacting concrete for faster placement and reduced disruption.
- Expansion into emerging markets in Asia‑Pacific, Latin America and Middle East will create new growth corridors for self‑compacting concrete.
- Integration of self‑compacting concrete in 3D printing of concrete structures will present novel applications.
- Development of low‑carbon and eco‑friendly self‑compacting concrete variants will align with sustainability goals and drive uptake.
- Collaboration between material producers and construction firms will foster customized self‑compacting concrete solutions for niche projects.
- Training and workforce upskilling in placing and curing self‑compacting concrete will support higher adoption rates among contractors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Sustainable Construction
Self-compacting concrete (SCC) reduces energy consumption and labor costs by eliminating the need for vibration, aligning with global sustainability goals and increasing adoption in green building projects.
Technological Advancements in Concrete Production
Innovations in admixtures and mix design have improved SCC’s workability and durability, enabling its use in complex structures and expanding its application across infrastructure, residential, and commercial projects.
Urbanization and Infrastructure Development
Rapid urbanization and large-scale infrastructure projects, especially in Asia Pacific, are driving demand for SCC due to its efficiency in high-rise, densely reinforced, and complex formwork construction.
Rise in Smart Construction Practices
The integration of automation and robotics in construction favors SCC for its self-leveling and self-compacting properties, supporting faster, more precise, and less labor-intensive building processes.
Adoption of Green Building Certifications
Increasing pursuit of certifications like LEED is encouraging the use of SCC, as its eco-friendly properties and reduced construction waste help meet stringent environmental standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Self-Compacting Concrete market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Self-Compacting Concrete market projected to grow between 2025 and 2032?
Which Self-Compacting Concrete market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Self-Compacting Concrete market?
Who are the leading companies in the Self-Compacting Concrete market?
Which region commanded the largest share of the Self-Compacting Concrete market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Powder
- 1.2.2 Viscosity
- 1.2.3 Combination
- 1.3 By End-use
- 1.3.1 Oil & gas
- 1.3.2 Infrastructure
- 1.3.3 Building & Construction
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.33 billion → 2032: USD 21.67 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Self-Compacting Concrete Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Self-Compacting Concrete Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Self-Compacting Concrete Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Self-Compacting Concrete Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Self-Compacting Concrete Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Self-Compacting Concrete Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Self-Compacting Concrete Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Self-Compacting Concrete Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.33 billion → 2032: USD 21.67 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Self-Compacting Concrete Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powder
- 12.3.7.2 Viscosity
- 12.3.7.3 Combination
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil & gas
- 12.4.7.2 Infrastructure
- 12.4.7.3 Building & Construction
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Self-Compacting Concrete End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Self-Compacting Concrete Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Self-Compacting Concrete Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Self-Compacting Concrete Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CEMEX S.A.B. de C.V.
- 18.4 ACC Limited
- 18.5 SIKA AG
- 18.6 LafargeHolcim
- 18.7 HeidelbergCement AG
- 18.8 Tarmac
- 18.9 Unibeton Ready Mix
- 18.10 UltraTech Concrete
- 18.11 Kilsaran
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

