
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Shopping Tourism Market Size 2024 | USD 267.2 Million |
| Shopping Tourism Market, CAGR | 9.3% |
| Shopping Tourism Market Size 2032 | USD 544.3 Million |
Market Overview
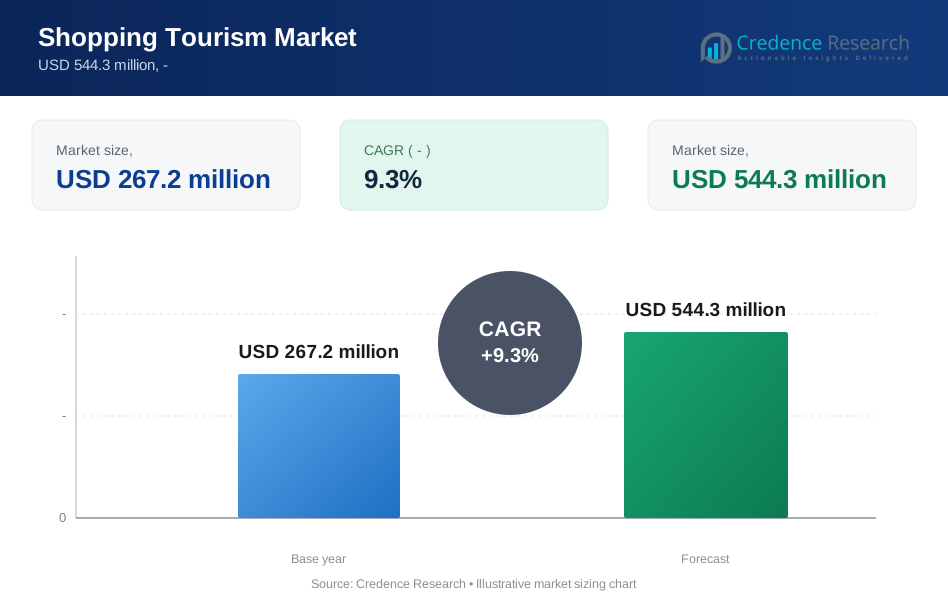
The Shopping Tourism Market is experiencing robust growth, fueled by the rising trend of travel combined with shopping experiences. As of 2024, the global Shopping Tourism Market is valued at approximately USD 267.2 million and is projected to grow at a compound annual growth rate (CAGR) of 9.3%, reaching around USD 544.3 million by 2032. This dynamic growth reflects the increasing consumer preference for travel destinations that offer unique shopping opportunities, luxury goods, and cultural experiences.
Several key factors are driving the expansion of this market. The globalization of retail brands and the rise of e-commerce have led to an increased interest in international shopping experiences, encouraging tourists to seek out destinations known for their shopping offerings. Additionally, the growth of disposable income and the expansion of the middle class in emerging economies are enabling more consumers to travel for leisure and shopping purposes.
Regionally, Europe remains a dominant player in the Shopping Tourism Market, primarily due to its rich cultural heritage and a wide variety of luxury shopping options. North America follows closely, with cities like New York and Los Angeles attracting millions of shopping tourists annually. The Asia-Pacific region is expected to see significant growth in the coming years, driven by increasing tourism flows, particularly in countries like China and Japan, where shopping experiences are a major draw for international travellers. Emerging markets in this region are poised to present substantial growth opportunities as they enhance their retail offerings and improve tourism infrastructure.
Market Drivers:
Growing Disposable Income:
The rise in disposable income among consumers worldwide is a significant driver of the Shopping Tourism Market. As more individuals experience an increase in their financial resources, they are more likely to allocate funds towards travel and leisure activities, including shopping. According to the World Bank, global GDP per capita has seen a steady increase, rising by approximately 2.5% annually over the last decade. This growth in income is particularly pronounced in emerging economies, where the burgeoning middle class is increasingly seeking travel experiences that incorporate shopping. For instance, a survey by the IMF indicated that in Southeast Asia, household consumption is expected to increase by around 6% annually, significantly boosting demand for shopping tourism as families look to combine travel with unique retail experiences.
Globalization of Retail Brands:
The globalization of retail brands has expanded shopping tourism opportunities across various markets. Major retail chains and luxury brands are now present in numerous countries, making it easier for tourists to shop for their favorite products while traveling. This trend is supported by the OECD, which reported that global cross-border retail sales have grown by approximately 10% year-on-year, reflecting the increasing accessibility of international brands to consumers worldwide. For instance, the expansion of flagship stores in cities like Paris and New York not only enhances local tourism but also attracts international shoppers seeking unique items. A study from the World Bank highlights that tourism-dependent economies see a marked increase in retail sales when global brands establish a presence, illustrating the symbiotic relationship between tourism and shopping.
Enhanced Travel Accessibility:
Improvements in travel accessibility are another crucial factor contributing to the growth of the Shopping Tourism Market. The expansion of low-cost airlines and increased international flight routes have made travel more affordable and convenient for many consumers. The International Air Transport Association (IATA) reported a consistent increase in global passenger traffic, with growth rates around 5.2% per year. This increased connectivity encourages consumers to explore new destinations, many of which offer distinctive shopping experiences. Additionally, government initiatives aimed at promoting tourism-such as visa facilitation programs-are further boosting travel. For instance, several countries, including India and Kenya, have introduced e-visas or visa-on-arrival policies, streamlining the process for tourists and encouraging shopping tourism.
Experience-Oriented Travel Trends:
A shift towards experience-oriented travel is transforming consumer preferences, with shopping now often intertwined with cultural and recreational experiences. Tourists are increasingly seeking destinations that offer more than just shopping; they want to engage in local culture, food, and entertainment. The United Nations World Tourism Organization (UNWTO) notes that experience-driven travel is expected to grow by approximately 8% annually, underscoring the demand for shopping experiences that incorporate local flavor and cultural significance. For instance, artisan markets and local craft fairs are becoming major attractions for tourists eager to purchase unique items while enjoying immersive cultural experiences. This trend encourages destinations to develop integrated tourism strategies that blend shopping with local experiences, enhancing the overall appeal of shopping tourism.
Market Trends:
Rise of Eco-Friendly Shopping Tourism:
As global awareness of environmental issues grows, eco-friendly shopping tourism is emerging as a significant trend. Consumers are increasingly seeking sustainable travel experiences, and this includes shopping at stores that prioritize ethical practices and environmentally friendly products. The World Tourism Organization (UNWTO) reports that eco-tourism is expected to grow by around 20% over the next decade, reflecting a shift in consumer preferences towards sustainability. For instance, the government of Canada has implemented initiatives to promote local artisans who create handmade goods from sustainable materials, appealing to environmentally conscious tourists. Additionally, the European Union has launched programs to support green businesses in the retail sector, further enhancing the appeal of shopping tourism that aligns with consumers' values.
Digital Transformation in Shopping Experiences:
The digital transformation of shopping experiences is another prominent trend shaping the Shopping Tourism Market. Advances in technology are enabling retailers to provide seamless online and offline shopping experiences for tourists. According to the International Monetary Fund (IMF), the digital retail market has seen exponential growth, with e-commerce sales projected to increase by approximately 15% annually. This trend is particularly relevant in the context of shopping tourism, where consumers are using mobile apps for location-based promotions, digital coupons, and augmented reality experiences that enhance their shopping journeys. For instance, the Singapore Tourism Board has leveraged technology to create interactive shopping maps and mobile payment options, making it easier for tourists to navigate local shopping scenes. Moreover, the Australian government has invested in digital infrastructure to support these innovations, recognizing the importance of technology in attracting and retaining shoppers.
Market Challenges Analysis:
Economic Instability and Currency Fluctuations:
One of the significant challenges facing the Shopping Tourism Market is economic instability, which can adversely affect consumer spending and travel behaviors. Economic downturns, whether local or global, often lead to reduced disposable income for consumers, making them less likely to travel for shopping purposes. For instance, during economic recessions, individuals tend to prioritize essential expenditures over luxury or leisure activities, including travel and shopping. Moreover, currency fluctuations can create uncertainty for international travelers. When the value of a tourist’s home currency declines against the currency of the destination country, the perceived cost of shopping and travel increases. According to the World Bank, regions with high volatility in currency exchange rates can see a decline in tourism revenue, as travelers may opt for destinations where their purchasing power remains stable. This unpredictability can deter potential tourists, impacting overall sales in the retail sector.
Increasing Competition from E-Commerce:
Another significant challenge for the Shopping Tourism Market is the rise of e-commerce, which has transformed consumer shopping behaviors. As online shopping becomes more convenient and accessible, many consumers are opting to purchase goods from the comfort of their homes rather than traveling to physical stores. The International Monetary Fund (IMF) has highlighted that global e-commerce sales have surged, leading to increased competition for traditional retail and shopping tourism. Many consumers now prioritize the convenience of online shopping, which offers a wider variety of products and often better prices due to lower overhead costs for online retailers. This shift in consumer preference can undermine the attractiveness of shopping destinations, as tourists may question the value of traveling when they can find similar products online. Furthermore, retail businesses in tourist-heavy areas are being pressured to adapt quickly to this shift, investing in digital strategies to complement their physical storefronts. Failure to innovate and embrace e-commerce strategies can result in a decline in foot traffic and sales, posing a significant threat to the viability of shopping tourism.
Market Segmentation Analysis:
By Type
The Shopping Tourism Market can be segmented by type into several categories, including luxury shopping, local markets, and branded retail outlets. Luxury shopping attracts high-income tourists seeking exclusive brands and unique products, often found in high-end malls and designer boutiques. This segment benefits from affluent travelers who are willing to spend significantly on luxury items. Local markets, on the other hand, appeal to tourists looking for authentic cultural experiences and locally crafted goods. These markets often offer unique souvenirs and traditional products, making them a popular choice for travelers interested in local culture. Branded retail outlets cater to both local and international tourists seeking well-known retail chains and franchises, providing a familiar shopping experience in foreign destinations. Each of these segments addresses different consumer preferences and spending behaviors, contributing to the overall diversity of the shopping tourism landscape.
By Technology
In terms of technology, the Shopping Tourism Market is influenced by several key factors, including mobile applications, augmented reality (AR), and online platforms. Mobile applications enhance the shopping experience by providing tourists with information on nearby stores, promotions, and digital payment options, facilitating seamless transactions while traveling. Augmented reality technology is increasingly being integrated into shopping experiences, allowing customers to visualize products in real-time, which can enhance engagement and drive sales. Online platforms, such as e-commerce websites and travel booking sites, play a crucial role in shaping consumer behavior, enabling shoppers to browse and purchase items before or during their trips. The integration of these technologies not only improves the shopping experience but also helps retailers attract tech-savvy tourists who prioritize convenience and innovation during their travels.
By End-User
The segmentation by end-user in the Shopping Tourism Market includes categories such as leisure travelers, business travelers, and expatriates. Leisure travelers constitute the largest segment, driven by the desire to explore new cultures, enjoy experiences, and shop for unique items during vacations. This group often seeks destinations known for their shopping offerings, combining travel with retail experiences. Business travelers may also engage in shopping during their trips, but their primary focus is usually on work-related activities. However, they may take advantage of shopping opportunities as a form of leisure. Expatriates, living away from their home countries, represent another significant segment, as they often seek familiar brands and products from their home countries while exploring their host locations. Understanding these diverse end-user segments allows retailers and tourism operators to tailor their offerings and marketing strategies to meet varying consumer needs.
Segmentations:
Based on Product Type:
- Luxury Shopping
- Local Markets
- Branded Retail Outlets
- Online Shopping Experiences
- Experiential Shopping
Based on Technology:
- Mobile Applications
- Augmented Reality (AR) Solutions
- E-commerce Platforms
- Digital Payment Systems
- Location-Based Services
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is a leading region in the Shopping Tourism Market, holding approximately 30% of the global market share. The United States, in particular, is a major hub for shopping tourism, attracting millions of international visitors each year. Cities like New York, Los Angeles, and Miami are renowned for their luxury shopping experiences, high-end retail outlets, and unique local markets. The region benefits from a well-developed infrastructure, with extensive transportation networks and a wide range of accommodations catering to diverse traveler needs. Furthermore, promotional efforts by tourism boards and retail associations enhance the appeal of shopping destinations through marketing campaigns and events. The rising trend of experiential shopping, where consumers seek not just products but immersive experiences, is also shaping the market. Retailers are increasingly adapting their strategies to create engaging environments that attract both local and international tourists.
Europe
Europe holds a significant share of the Shopping Tourism Market, accounting for around 35%. Countries such as the United Kingdom, France, and Italy are at the forefront, known for their luxury brands and iconic shopping districts. Cities like Paris, London, and Milan attract fashion enthusiasts and high-end shoppers from around the globe, making Europe a prime destination for luxury shopping tourism. Additionally, local markets and artisan shops in various European cities provide tourists with unique cultural experiences, enhancing the overall shopping journey. The region's historical significance, diverse retail offerings, and strong emphasis on customer service contribute to its robust market presence. Furthermore, European governments actively promote shopping tourism through initiatives that encourage cross-border shopping, highlighting tax refund schemes for international tourists and special shopping events. This approach not only boosts retail sales but also strengthens the overall economy.
Asia-Pacific
The Asia-Pacific region is witnessing rapid growth in the Shopping Tourism Market, currently holding approximately 25% of the global market share. Countries such as China, Japan, and Australia are leading this trend, driven by increasing disposable income and a burgeoning middle class. Chinese tourists, in particular, are known for their significant spending on shopping while abroad, making them a key demographic for many global retailers. Cities like Tokyo, Hong Kong, and Sydney offer a diverse range of shopping experiences, from luxury brands to local crafts, appealing to both international and domestic travelers. Additionally, the rise of digital technologies and e-commerce is reshaping the shopping landscape in the region, with many retailers integrating online platforms to enhance customer engagement and streamline the shopping experience. Governments are also investing in infrastructure and tourism initiatives to promote the region as a shopping destination, making it increasingly accessible to global travelers.
Key Players:
- LVMH Moët Hennessy Louis Vuitton
- Alibaba Group
- Walmart Inc.
- Kering SA
- Nike, Inc.
- com, Inc.
- Inditex (Zara)
- Chanel S.A.
- Richemont Group
- Target Corporation
Competitive Analysis:
The competitive landscape of the Shopping Tourism Market is characterized by a blend of luxury brands, retail giants, and e-commerce platforms, each vying for a share of the lucrative traveler segment. Major players like LVMH and Alibaba leverage their extensive brand portfolios and global reach to attract high-spending tourists, particularly in iconic shopping destinations. Retail giants such as Walmart and Target are expanding their presence in tourist-heavy areas, capitalizing on foot traffic and the demand for convenience. Meanwhile, the rise of digital shopping has intensified competition from e-commerce platforms like Amazon, which offer seamless online experiences and often better prices. Companies are increasingly focusing on creating unique shopping experiences that blend retail with cultural elements, responding to the trend of experiential travel. Furthermore, brands are investing in technology, such as augmented reality and mobile applications, to enhance customer engagement and streamline the shopping process. As consumer preferences shift towards sustainability, retailers that prioritize eco-friendly practices and local artisans are also gaining traction. The competitive dynamics are further influenced by regional tourism policies and promotional efforts by governments, which aim to attract international shoppers. Overall, the Shopping Tourism Market is highly competitive, with players continually adapting their strategies to meet evolving consumer expectations and capitalize on emerging trends.
Recent Developments:
- In February 2024, MakeMyTrip and the Goa Government collaborated to revive tourism in the region.
- In March 2024, the Tourism Authority of Thailand announced its inaugural collaboration with Tourism Cares.
- In 2023, Risposte Turismo and ENIT joined forces to promote shopping tourism in Italy.
- In 2023, the Singapore Tourism Board positioned itself as a shopping destination, featuring three brands at Nykaaland.
Market Concentration & Characteristics
The Shopping Tourism Market exhibits moderate concentration, characterized by a mix of established global brands and local retailers. Major players, such as LVMH and Alibaba, dominate the luxury and online retail segments, leveraging their extensive resources and brand recognition to capture significant market shares. However, the presence of a diverse range of smaller, niche retailers and local artisans contributes to the market's fragmented nature, particularly in regions known for unique shopping experiences, such as local markets and boutique shops. This diversity allows consumers to engage in a variety of shopping experiences that cater to different tastes and preferences. The market is also characterized by a growing emphasis on sustainability, with many brands adopting eco-friendly practices to attract environmentally conscious consumers. Additionally, technological advancements are reshaping the landscape, as retailers increasingly implement digital solutions, such as mobile apps and augmented reality, to enhance customer engagement and streamline the shopping experience. The convergence of these characteristics creates a dynamic environment where both large and small players can thrive, each offering distinct value propositions. As the market continues to evolve, the interplay between global brands and local retailers will shape its future trajectory, driving innovation and competition in the shopping tourism space.
Report Coverage:
This report provides a comprehensive analysis of the Shopping Tourism Market, covering key trends, growth drivers, challenges, and regional dynamics. It explores the market's segmentation based on product type, technology, and end-users, offering insights into consumer preferences and behaviors. The report delves into the competitive landscape, highlighting major players and their strategies to capture market share, including the integration of digital technologies and the emphasis on sustainability. Regional analysis encompasses key markets such as North America, Europe, and Asia-Pacific, detailing their respective contributions to the overall market and the unique characteristics that drive shopping tourism in each area. Additionally, the report examines market concentration and characteristics, providing an understanding of the interplay between global brands and local retailers. By leveraging data from reputable sources like the World Bank and IMF, this report aims to equip stakeholders with valuable insights for informed decision-making. It serves as a strategic resource for retailers, tourism boards, and investors seeking to navigate the evolving landscape of shopping tourism, identify emerging opportunities, and develop effective strategies to engage consumers in a competitive environment. Through a detailed examination of current trends and future projections, this report is designed to be an essential tool for anyone looking to understand and capitalize on the growing shopping tourism sector.
Future Outlook:
- Anticipate a surge in international travel as restrictions ease, boosting shopping tourism.
- Expect a growing emphasis on eco-friendly practices among retailers, appealing to environmentally conscious consumers.
- Anticipate enhanced shopping experiences through the adoption of augmented reality and mobile applications.
- Prepare for a shift towards personalized marketing strategies that leverage consumer data to improve engagement.
- Anticipate a rise in interest for local markets and artisan products, offering unique shopping experiences.
- Expect continued support from governments promoting tourism, including tax incentives and marketing campaigns.
- Prepare for an increase in omnichannel shopping experiences, combining online and in-store interactions.
- Expect a growing trend towards experiential shopping that integrates cultural activities with retail.
- Retailers will adapt to shifting consumer preferences, offering diverse product ranges that cater to various demographics.
- Anticipate increased investment in transportation and tourism infrastructure to enhance accessibility for shoppers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Disposable Income
Rising disposable incomes, especially in emerging economies, are enabling more consumers to travel internationally and allocate greater budgets to shopping, directly fueling the growth of shopping tourism.
Globalization of Retail Brands
The expansion of international retail and luxury brands into new markets makes it easier for tourists to access their favorite products abroad, increasing the appeal of travel for shopping purposes.
Enhanced Travel Accessibility
Improvements in air connectivity, the proliferation of low-cost carriers, and streamlined visa processes are making it more convenient and affordable for consumers to travel to shopping destinations.
Experience-Oriented Travel Trends
Tourists are increasingly seeking destinations that offer immersive shopping experiences combined with local culture, food, and entertainment, driving demand for integrated shopping tourism offerings.
Digital Transformation in Shopping
The adoption of mobile apps, digital payment systems, and augmented reality is enhancing the shopping experience for tourists, making it easier to discover, navigate, and purchase products while traveling.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the Shopping Tourism Market?
2What is the projected market value of the Shopping Tourism Market by 2032?
Which regions are leading in the Shopping Tourism Market?
How does the middle class contribute to the Shopping Tourism Market?
What types of shopping experiences attract tourists?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Leisure Travelers
- 1.2.2 Business Travelers
- 1.2.3 Expatriates
- 1.3 By Technology
- 1.3.1 Mobile Applications
- 1.3.2 Augmented Reality (AR) Solutions
- 1.3.3 E-commerce Platforms
- 1.3.4 Digital Payment Systems
- 1.3.5 Location-Based Services
- 1.4 By Product Type
- 1.4.1 Luxury Shopping
- 1.4.2 Local Markets
- 1.4.3 Branded Retail Outlets
- 1.4.4 Online Shopping Experiences
- 1.4.5 Experiential Shopping
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 267.2 million → Forecast year: USD 544.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Shopping Tourism Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Shopping Tourism Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Shopping Tourism Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Shopping Tourism Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Shopping Tourism Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Shopping Tourism Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Shopping Tourism Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Shopping Tourism Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 267.2 million → Forecast year: USD 544.3 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Shopping Tourism Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Base-Year Market Share, 2032
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Leisure Travelers
- 12.3.6.2 Business Travelers
- 12.3.6.3 Expatriates
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Base-Year Market Share, 2032
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Mobile Applications
- 12.4.6.2 Augmented Reality (AR) Solutions
- 12.4.6.3 E-commerce Platforms
- 12.4.6.4 Digital Payment Systems
- 12.4.6.5 Location-Based Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Base-Year Market Share, 2032
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Luxury Shopping
- 12.5.6.2 Local Markets
- 12.5.6.3 Branded Retail Outlets
- 12.5.6.4 Online Shopping Experiences
- 12.5.6.5 Experiential Shopping
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Shopping Tourism End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Shopping Tourism Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Shopping Tourism Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Shopping Tourism Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 LVMH Moët Hennessy Louis Vuitton
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Alibaba Group
- 18.4 Walmart Inc.
- 18.5 Kering SA
- 18.6 Nike, Inc.
- 18.7 Amazon.com, Inc.
- 18.8 Inditex (Zara)
- 18.9 Chanel S.A.
- 18.10 Richemont Group
- 18.11 Target Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

