
Market overview
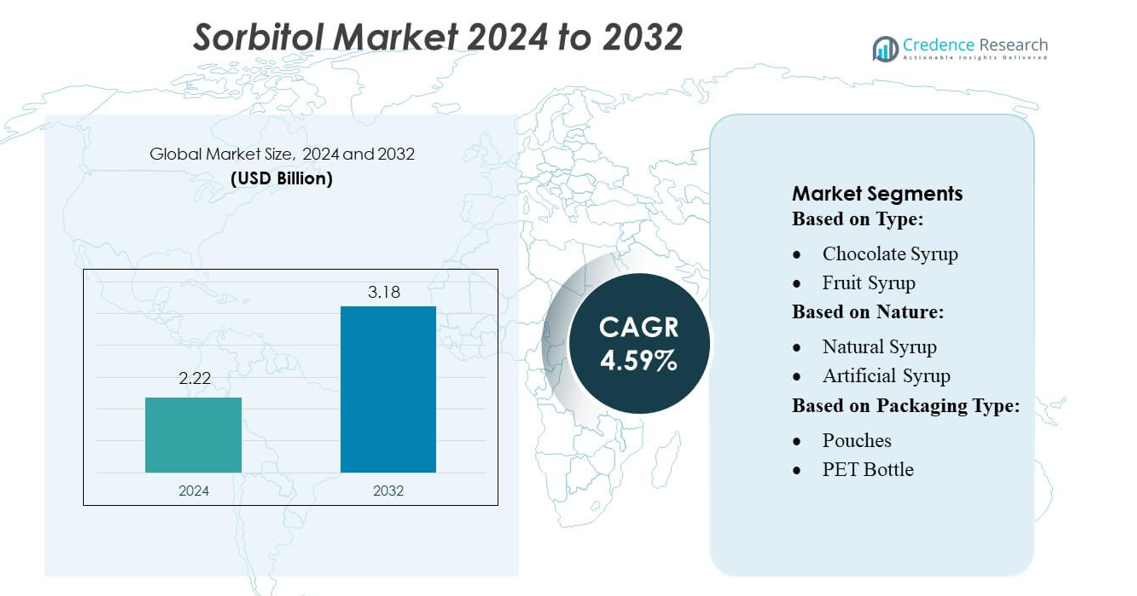
Sorbitol Market size was valued USD 2.22 billion in 2024 and is anticipated to reach USD 3.18 billion by 2032, at a CAGR of 4.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sorbitol Market Size 2024 | USD 2.22 billion |
| Sorbitol Market, CAGR | 4.59% |
| Sorbitol Market Size 2032 | USD 3.18 billion |
The sorbitol market features strong competition among leading global manufacturers, including Roquette Frères, ADM, Cargill Incorporated, Gulshan Polyols Ltd., Ecogreen Oleochemicals GmbH, DuPont, Merck KGaA, SPI Pharma, American International Foods, Inc., and Qinhuangdao Lihua Starch Co., Ltd., each expanding capabilities across food, pharmaceutical, and personal care applications. Asia-Pacific stands as the leading region, accounting for approximately 42–45% of total market share, supported by large-scale production capacity, abundant raw material availability, and rapidly growing consumption in end-use industries. Continuous investments in technology, sustainability initiatives, and product innovation further reinforce the leadership of these companies in the global sorbitol landscape.
Market Insights
- The Sorbitol Market was valued at USD 2.22 billion in 2024 and is projected to reach USD 3.18 billion by 2032, registering a CAGR of 4.59% during the forecast period.
- Rising demand for low-calorie sweeteners in food, pharmaceutical, and personal care applications continues to drive market expansion, supported by increasing consumer preference for healthier formulations.
- The market is witnessing notable trends such as advancements in bio-based production, growing use of sorbitol in oral care, and sustained innovation by leading players to enhance purity and application versatility.
- Challenges emerge from fluctuating raw material prices and stringent regulatory frameworks, which may limit operational flexibility for manufacturers across key markets.
- Asia-Pacific leads the global landscape with 42–45% market share, while liquid sorbitol remains the dominant segment with the highest consumption; growth is reinforced by strong industrial capacity, expanding end-use sectors, and competitive pricing across major regional producers.
Market Segmentation Analysis:
By Type
The sorbitol market demonstrates strong adoption across type categories, with fruit syrup emerging as the dominant sub-segment, accounting for the largest market share due to its extensive use in confectionery, bakery, and beverage applications. Manufacturers prefer fruit syrup-based sorbitol for its higher stability, natural sweetness profile, and compatibility with clean-label product formulations. Demand is further driven by its role as a low-calorie sugar substitute and humectant in processed foods. Chocolate syrup and maple syrup variants continue to grow steadily, supported by rising utilization in dessert toppings and premium food products.
- For instance, Roquette Frères operates more than 30 manufacturing sites globally and produces sorbitol at its Lestrem facility, which is recognized as one of the world’s largest polyol production complexes, supporting large-scale supply for fruit syrup applications.
By Nature
Within the nature-based segmentation, natural syrup leads the market with a major share, supported by strong consumer preference for plant-derived sweeteners and increasing regulatory encouragement for clean-label formulations. Food and beverage producers increasingly adopt natural sorbitol to replace synthetic ingredients, leveraging its reduced glycemic response and multifunctional properties such as moisture retention and texture enhancement. Artificial syrup sorbitol maintains relevance due to cost efficiency and consistent quality, but its growth remains comparatively moderate as brands shift toward more sustainable and health-supportive alternatives in product development.
- For instance, ADM processes more than 2.4 million bushels of corn per day across its global wet-milling network, supplying the carbohydrate feedstocks required for large-scale sorbitol production, and operates 47 innovation centers worldwide where teams develop advanced carbohydrate-conversion technologies.
By Packaging Type
In packaging type segmentation, PET bottles hold the dominant market share, driven by their durability, lightweight structure, and superior barrier properties that maintain sorbitol stability during storage and transport. Manufacturers prefer PET due to cost-effectiveness, recyclability, and compatibility with bulk distribution channels. Pouches are gaining traction for their convenience and suitability for single-use or small-portion formats, particularly in foodservice applications. Glass bottles retain a niche presence, primarily in premium and pharmaceutical-grade sorbitol products where product purity, chemical resistance, and premium branding are prioritized.
Key Growth Drivers
Expanding Applications Across Food & Beverage Formulations
The sorbitol market grows as manufacturers increasingly use the ingredient in reduced-sugar and sugar-free products due to its sweetness profile, humectant functionality, and caloric advantage over sucrose. Food producers strengthen product stability and texture by leveraging sorbitol in confectionery, bakery, and beverage formulations. Rising consumer demand for healthier sweetening agents accelerates its penetration in fortified and functional foods. Regulatory support for polyol-based sweeteners across major economies further reinforces adoption, especially as brands diversify their low-calorie product portfolios.
- For instance, SPI Pharma offers Sorbogem SD 250 and SD 500, spray-dried crystalline sorbitol grades with nominal particle sizes of 250 µm and 500 µm, respectively, which deliver excellent flow and superior compactibility for direct-compression tablets.
Rising Demand from Pharmaceutical & Personal Care Industries
Pharmaceutical manufacturers drive demand as sorbitol serves as a stabilizer, excipient, and sweetener in syrups, tablets, and nutraceuticals. Its non-cariogenic, moisture-retaining, and solubility-enhancing properties position it as an essential ingredient in oral care and dermatology products. Cosmetic brands incorporate sorbitol into lotions, creams, gels, and toothpaste to enhance texture and hydration. The continued shift toward gentle, skin-friendly formulations in personal care and expanding OTC medication consumption globally significantly boost sorbitol uptake across these high-volume industries.
- For instance, Ecogreen Oleochemicals’ Sorbitol TF grade is spray-dried to 98% purity, remains stable to 180 °C, and resists Maillard browning even at low and high pH, making it ideal for oral-care and dermatology formulations.
Increasing Use of Sorbitol as a Biomass-Derived Chemical Intermediate
Sorbitol’s role as a platform chemical for producing bio-based derivatives-such as isosorbide, propylene glycol, and vitamin C intermediates-fuels long-term market expansion. The global focus on decarbonization and sustainable chemical production encourages manufacturers to adopt sorbitol as a renewable feedstock. Its cost-effective conversion and compatibility with green chemistry processes position it as a preferred input for polymer, resin, and specialty chemical producers. Growing investment in bio-refineries and renewable raw material value chains supports rising industrial demand globally.
Key Trends & Opportunities
Transition Toward Bio-Based and Non-GMO Sorbitol
Manufacturers capitalize on rising demand for naturally sourced, non-GMO, and clean-label sweetening agents. Production strategies increasingly focus on maize-, wheat-, and cassava-based feedstock certified for sustainability. Investment in green processing technologies and enzymatic conversion methods enhances yield efficiency, reducing environmental footprint. The clean-label movement across food, nutraceuticals, and cosmetics creates an opportunity for producers offering verified eco-friendly sorbitol grades that meet stringent consumer and regulatory expectations.
- For instance, its Parteck® SI 400 LEX sorbitol grade is directly-compressible and meets Ph. Eur., BP, NF, and JP standards, offering a melting point of 94–96 °C and a solubility of 2,350 g/L in water.
Growing Adoption in Bioplastics and Sustainable Polymers
A key market opportunity emerges as sorbitol-derived isosorbide gains traction in bioplastics, particularly in bio-polyethylene terephthalate (bio-PET) and polycarbonates. Brands increasingly evaluate renewable polymers to meet circular-economy targets. Sorbitol serves as a cost-efficient pathway to high-performance, bio-based monomers that enhance transparency, thermal stability, and mechanical properties. The expansion of sustainable packaging, automotive lightweighting initiatives, and green construction materials creates a strong demand outlook for sorbitol-based chemical intermediates.
- For instance, Gulshan Polyols Ltd. produces sorbitol at its integrated corn-to-sorbitol facility in Jhagadia, Gujarat, with a nameplate capacity of 72,000 MTPA, according to its annual report.
Expansion of Sorbitol in Oral Care and Dermatology Innovations
Opportunities grow as global oral-care and skincare manufacturers develop high-hydration and sensitive-skin formulations. Sorbitol enhances moisture retention, improves product aesthetics, and supports compatibility with active ingredients used in toothpaste, mouthwashes, gels, and serums. Rising consumer interest in premium and dermatologically tested products drives stronger use of polyols for texture optimization. As companies expand portfolios into sulfate-free, alcohol-free, and mild-care formulations, sorbitol becomes a critical ingredient for performance enhancement.
Key Challenges
Volatility in Raw Material Prices and Supply Chain Constraints
Sorbitol production heavily depends on agricultural feedstock such as corn, wheat, and cassava, making the market vulnerable to fluctuations caused by weather disruptions, crop disease, and geopolitical trade issues. Unpredictable price movements in raw materials directly elevate production costs for manufacturers. Additionally, supply chain disruptions-especially in major producing regions-affect the consistency of sorbitol availability, limiting the ability of downstream industries to maintain stable procurement and long-term pricing strategies.
Availability of Alternative Sweeteners and Polyols
The market faces competitive pressure from alternative low-calorie sweeteners and polyols such as xylitol, maltitol, and erythritol, which offer similar functional advantages. Food and beverage manufacturers often evaluate substitutes based on cost, flavor profile, digestion tolerance, and formulation performance. The increasing R&D investment in next-generation sweeteners with improved taste and reduced digestive side effects intensifies competition. As consumers seek natural sweetness with fewer gastrointestinal concerns, these alternatives can limit wider sorbitol adoption.
Regional Analysis
North America
North America holds a significant position in the global sorbitol market, capturing approximately 18–20% of total share, driven by strong penetration of pharmaceutical excipients and sugar-free food and beverage formulations. The region benefits from advanced manufacturing capabilities, stringent quality standards, and rising consumer preference for low-calorie sweeteners. Increasing adoption of sorbitol in oral care, particularly toothpaste and mouthwash, further strengthens demand. Moreover, innovation in personal care formulations by leading manufacturers supports steady market expansion. Growth remains reinforced by rising health awareness and the availability of well-established distribution channels across the United States and Canada.
Europe
Europe accounts for around 22–24% of the global sorbitol market, supported by robust demand from food processing, personal care, and pharmaceutical industries. The region’s regulatory focus on reducing sugar intake has accelerated the adoption of sorbitol in confectionery, bakery, and diet-friendly beverages. Strong presence of multinational cosmetic brands further enhances consumption in skincare and haircare products. Additionally, expansion of bio-based chemical production across Germany, France, and the Netherlands fosters steady market growth. Europe’s well-developed manufacturing infrastructure and rising consumer interest in clean-label ingredients continue to sustain its prominent market share and long-term growth outlook.
Asia-Pacific
Asia-Pacific dominates the global sorbitol market with the largest share of 42–45%, driven by expanding food and beverage industries, increasing diabetic population, and cost-effective manufacturing capabilities. China and India serve as major production hubs due to abundant raw material availability and large-scale industrial output. Rising demand for personal care products, growing awareness of sugar substitutes, and rapid urbanization further propel regional consumption. Pharmaceutical applications continue to accelerate, supported by expanding generic drug production. The region’s dynamic economic environment and increasing investments in bioprocessing technologies reinforce Asia-Pacific’s leadership in the global sorbitol landscape.
Latin America
Latin America holds around 8–10% of the global sorbitol market, with growth supported by increasing use in confectionery, beverages, and personal care formulations. Brazil and Mexico lead regional consumption due to a growing middle-class population and rising demand for low-calorie sweeteners. Expanding usage in oral care and cosmetics further boosts adoption across major brands operating in the region. Additionally, the region’s gradual shift toward healthier diets is encouraging manufacturers to incorporate sorbitol into processed foods. Although production capacity remains limited, improving industrial infrastructure and trade partnerships support steady market expansion.
Middle East & Africa
The Middle East & Africa region represents approximately 6–8% of the global sorbitol market, driven by increasing demand for processed foods, confectionery products, and affordable personal care items. Growing urbanization and changing consumer lifestyles contribute to higher adoption of sugar substitutes, including sorbitol. Pharmaceutical applications continue to expand, particularly in countries with developing healthcare infrastructure. While domestic production remains limited, rising imports and strategic partnerships with global suppliers sustain market availability. Additionally, increasing investments in food processing and retail modernization support a gradual upward trend in sorbitol consumption across key MEA economies.
Market Segmentations:
By Type:
- Chocolate Syrup
- Fruit Syrup
By Nature:
- Natural Syrup
- Artificial Syrup
By Packaging Type:
- Pouches
- PET Bottle
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the sorbitol market remains moderately consolidated, with key players such as Roquette Frères, ADM, SPI Pharma, Ecogreen Oleochemicals GmbH, Cargill Incorporated, Merck KGaA, American International Foods, Inc., Gulshan Polyols Ltd., DuPont, and Qinhuangdao Lihua Starch Co., Ltd. The sorbitol market remains moderately consolidated, shaped by continuous advancements in production technologies, expanding application scope, and increasing focus on sustainable ingredient development. Manufacturers are prioritizing high-purity grades to meet stringent requirements across pharmaceuticals, food and beverages, and personal care formulations. The market is witnessing growing investments in efficient starch conversion processes, capacity expansion in cost-effective production regions, and product innovation aimed at improving stability and performance. Strategic collaborations, long-term supply agreements, and diversification of end-use portfolios further support competitive positioning. Companies are also strengthening distribution networks and enhancing regulatory compliance to maintain global competitiveness and address rising consumer demand for low-calorie, clean-label solutions.
Key Player Analysis
- Roquette Frères
- ADM
- SPI Pharma
- Ecogreen Oleochemicals GmbH
- Cargill Incorporated
- Merck KGaA
- American International Foods, Inc.
- Gulshan Polyols Ltd.
- DuPont
- Qinhuangdao Lihua Starch Co., Ltd.
Recent Developments
- In January 2024, Sanstar Limited announced its capacity expansion at the Dhule facility by an additional 1,000 tons per day for maize-based specialty products, including sorbitol, to meet rising global demand for plant-based ingredients.
- In November 2023, Valeo Foods launched a new maple syrup range called Maple Crest Maple Syrup in the UK. This new product is a dark, robust-flavored syrup priced at for a 330g package, aimed at helping the company sell Canadian syrups to UK consumers.
- In November 2023, the Canadian Maple Company launched a new digital platform to improve its export business by enabling direct-to-consumer sales and ensuring product authenticity. This move leverages digital innovation to expand its market reach and connect with global consumers more efficiently
Report Coverage
The research report offers an in-depth analysis based on Type, Nature, Packaging Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience rising demand as food and beverage manufacturers increasingly adopt sorbitol as a preferred low-calorie sweetener.
- Pharmaceutical applications will expand due to growing utilization of sorbitol in formulations such as syrups, tablets, and oral care products.
- Personal care and cosmetics will drive steady growth as brands prioritize humectants that enhance texture and moisture retention.
- Manufacturing capacity will increase across Asia-Pacific as producers invest in cost-efficient starch processing technologies.
- Innovation in bio-based and sustainable production methods will strengthen the market’s environmental positioning.
- Regulatory support for sugar reduction in packaged foods will accelerate adoption across global markets.
- Product diversification will intensify as companies introduce high-purity and application-specific sorbitol grades.
- Supply chain integration will improve as manufacturers optimize raw material sourcing and distribution networks.
- Strategic partnerships and mergers will rise as companies aim to strengthen geographic presence and technology capabilities.
- Market competitiveness will heighten as players focus on quality certification, consistency, and adherence to global standards.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Applications in Food & Beverage
Sorbitol is increasingly used as a low-calorie sweetener and humectant in confectionery, bakery, and beverage products, driven by consumer demand for healthier, sugar-reduced formulations and regulatory support for sugar reduction.
Rising Demand from Pharmaceutical & Personal Care Industries
Pharmaceutical and personal care manufacturers utilize sorbitol for its stabilizing, moisture-retaining, and non-cariogenic properties in syrups, tablets, oral care, and skincare products, fueling steady market growth.
Advancements in Bio-Based and Sustainable Production
The shift toward bio-based, non-GMO, and clean-label ingredients is prompting manufacturers to invest in green processing technologies and sustainable feedstocks, enhancing the market’s environmental profile and appeal to health-conscious consumers.
Growth in Industrial and Chemical Applications
Sorbitol’s role as a renewable platform chemical for producing bio-based derivatives such as isosorbide and vitamin C intermediates is expanding, supported by global decarbonization efforts and investments in sustainable chemical production.
Innovation in Packaging and Distribution
The adoption of PET bottles and convenient pouches for sorbitol packaging improves product stability, cost efficiency, and accessibility, supporting broader distribution and increased consumption across diverse end-use sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Sorbitol Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Sorbitol Market projected to grow between 2025 and 2032?
What are the key drivers for the growth of the sorbitol market?
Which is the major segment in the sorbitol market by Application?
Which is the major segment in the Sorbitol market by end-use channel?
Who are the leading companies in the Sorbitol Market?
Which region commanded the largest share of the Sorbitol Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Fruit Syrup
- 1.2.2 Chocolate Syrup
- 1.2.3 Maple Syrup
- 1.3 By Nature
- 1.3.1 Natural Syrup
- 1.3.2 Artificial Syrup
- 1.4 By Application
- 1.4.1 Food & Beverage
- 1.4.2 Pharmaceuticals
- 1.4.3 Personal Care & Cosmetics
- 1.4.4 Industrial/Bio-based Chemicals
- 1.5 By Packaging Type
- 1.5.1 PET Bottle
- 1.5.2 Pouches
- 1.5.3 Glass Bottle
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.22 billion → 2032: USD 3.18 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sorbitol Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sorbitol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sorbitol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sorbitol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sorbitol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sorbitol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sorbitol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sorbitol Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.22 billion → 2032: USD 3.18 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sorbitol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fruit Syrup
- 12.3.7.2 Chocolate Syrup
- 12.3.7.3 Maple Syrup
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Nature - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Natural Syrup
- 12.4.7.2 Artificial Syrup
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food & Beverage
- 12.5.7.2 Pharmaceuticals
- 12.5.7.3 Personal Care & Cosmetics
- 12.5.7.4 Industrial/Bio-based Chemicals
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 PET Bottle
- 12.6.7.2 Pouches
- 12.6.7.3 Glass Bottle
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sorbitol End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sorbitol Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sorbitol Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sorbitol Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Roquette Frères
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ADM
- 18.4 Cargill Incorporated
- 18.5 Gulshan Polyols Ltd.
- 18.6 Ecogreen Oleochemicals GmbH
- 18.7 DuPont
- 18.8 Merck KGaA
- 18.9 SPI Pharma
- 18.10 American International Foods, Inc.
- 18.11 Qinhuangdao Lihua Starch Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

