
Market overview
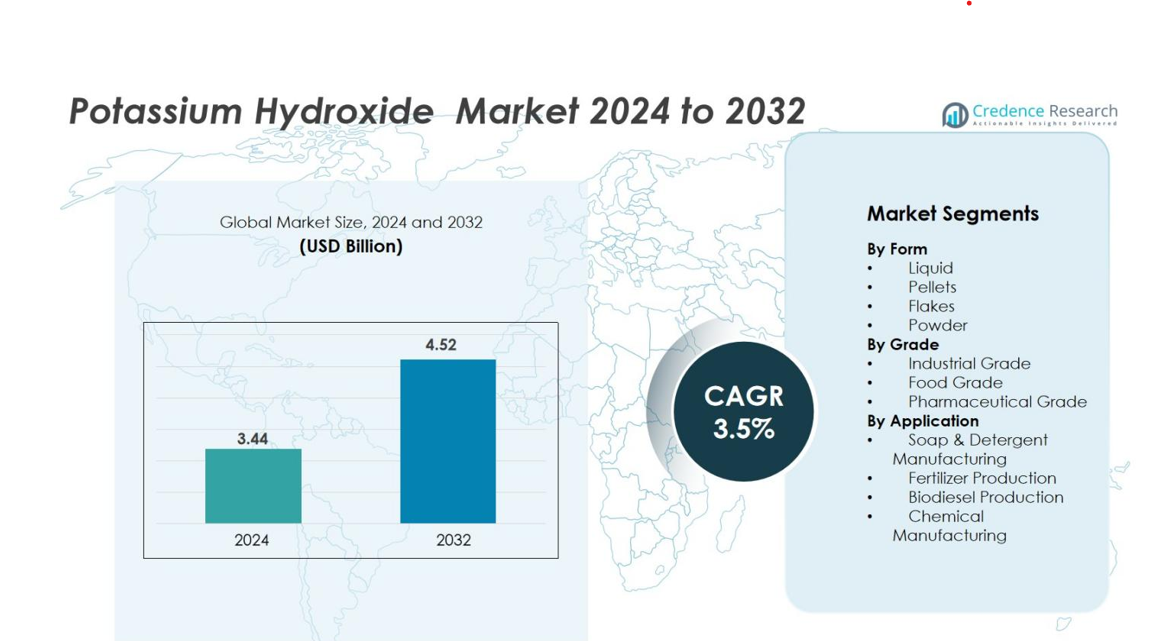
The Potassium Hydroxide market size was valued at USD 3.44 billion in 2024 and is anticipated to reach USD 4.52 billion by 2032, at a CAGR of 3.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Potassium Hydroxide Market Size 2024 | USD 3.44 billion |
| Potassium Hydroxide Market, CAGR | 3.5% |
| Potassium Hydroxide Market Size 2032 | USD 4.52 billion |
The global Potassium Hydroxide market features prominent players including Solvay S.A., BASF SE, Dow Inc., Occidental Petroleum Corporation (OxyChem), Olin Corporation, UNID Co., Ltd., Merck KGaA, Airedale Chemical Company Limited, American Elements and Altair Chemical S.r.l.. These firms dominate through integrated production, broad geographic reach and diverse grade portfolios. Regionally, Asia‑Pacific leads the market with a 39.8% share, North America holds about 29.9%, and Europe captures roughly 25% of global revenue. Their strategic investments in high‑purity grades, sustainable manufacturing and regional expansion drive competitive strength.
Market Insights
- The Potassium Hydroxide market was valued at USD 3.44 billion in 2024 and is projected to reach USD 4.52 billion by 2032, growing at a CAGR of 3.5% during the forecast period.
- Rising demand for fertilizers, biodiesel production, and detergent manufacturing are key drivers for market growth, with agricultural expansion being the major contributing factor.
- The market is witnessing a trend toward higher-grade KOH for pharmaceutical and food applications, alongside the adoption of sustainable production technologies.
- Competitive landscape includes key players like Solvay, BASF, Dow, and Occidental Petroleum, with Asia-Pacific leading the market share at 39.8%, followed by North America at 29.9% and Europe at 25%.
- Key restraints include regulatory challenges, raw material price fluctuations, and competition from substitutes like Sodium Hydroxide, which may limit market potential.
Market Segmentation Analysis
By Form
The liquid form dominates the Potassium Hydroxide market with an estimated 55.6% share in 2024. Its strong performance stems from ease of handling, high solubility, and suitability for large‑scale chemical, biodiesel and water‑treatment operations. Pellets, flakes and powder forms are growing, but liquid remains preferred for high‑volume industrial applications given its operational advantages and process adaptability.
- For instance, sodium hydroxide is available in pellets, flakes, or as a liquid solution. The solid forms (pellets and flakes) are often preferred for applications requiring high purity and specific dosing, like in pharmaceuticals and laboratories.
By Grade
In 2024 the industrial‑grade segment held around 66.7% of the market. This grade sees vast usage across detergent manufacture, fertilizers, chemical processing and petroleum refining because of its cost efficiency and suitability for bulk applications. Food and pharmaceutical grades are growing faster, yet industrial grade continues to dominate thanks to its broad base of end‑use industries and established supply chains.
- For instance, BASF SE utilizes industrial-grade ammonia in fertilizer synthesis (e.g., to produce urea and ammonium nitrate) and a wide range of chemical manufacturing applications, capitalizing on its integrated production (Verbund) system to ensure a reliable supply chain and consistent performance.
By Application
The fertilizer‑production segment led the market in 2024 with an estimated 34.6% share, driven by rising agriculture demand and the essential role of potassium hydroxide in potassium‑based fertilizers. Soap & detergent manufacturing holds a strong position as well and biodiesel production is projected to grow fastest. Chemical manufacturing remains a key contributor, underlining the compound’s importance across industrial value chains.
Key Growth Drivers
Rising Demand in Agriculture
The global population growth and increasing need for higher crop yields drive strong demand for fertilizers, where Potassium Hydroxide (KOH) plays a critical role in producing potassium‑based compounds. Manufacturers leverage KOH’s alkaline properties to formulate efficient and soil‑enhancing fertilizer blends. As intensive agricultural practices expand in regions such as Asia‑Pacific, KOH use in fertilizers becomes a consistent and growing contributor to market volume and value.
- For instance, Vynova produces liquid potassium hydroxide used in complex fertilizers to help plants grow stronger and larger, highlighting KOH's direct contribution to agricultural productivity.
Expansion of Chemical Manufacturing
An accelerating chemical processing industry drives KOH consumption across soaps, detergents, biodiesel, and specialty chemicals. With chemical manufacturers seeking strong alkalis for synthesis, pH regulation, and cleaning agent production, KOH becomes a preferred base material. The growth of industrial infrastructure, especially in developing economies, supports increasing volumes of KOH use and ultimately market expansion.
- For instance, industrial-grade KOH accounted for 67.4% of the market revenue share in 2024, driven by its widespread use in soap and detergent manufacturing, where precise alkali control is imperative for product quality.
Shift Toward Sustainable Energy and Products
The transition to cleaner energy solutions and eco‑friendly formulations presents an opportunity for KOH in biodiesel, alkaline batteries, and green cleaning agents. As regulations and consumer demand push toward lower‑impact chemicals, manufacturers turn to KOH for its versatility and lower environmental footprint compared to some alternatives. This shift strengthens KOH’s role in emerging applications and boosts its market potential.
Key Trends & Opportunities
High Purity Grades for Specialty Applications
A notable trend in the KOH market is the increasing demand for high-purity and specialty grades suited for pharmaceutical, food, and battery industries. As more end-use segments require tighter specifications, suppliers invest in purification and quality control enhancements to meet the growing standards. This trend is not only driven by stricter regulatory requirements but also by the demand for more reliable and efficient products. This creates opportunities for premium pricing, new product launches, and market differentiation, ultimately helping companies capture value in a more competitive marketplace.
- For instance, pharmaceutical companies, including major ones like Pfizer and Novartis, use extremely high-purity chemicals that meet stringent regulatory standards, such as those set by the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), in synthesizing active pharmaceutical ingredients (APIs), where minimizing impurities is critical to ensuring drug safety and efficacy.
Growth of Emerging Markets and Distribution Reach
Emerging economies in Asia-Pacific, Latin America, and Africa are expanding their industrial base and agricultural sectors, offering a strong opportunity for KOH suppliers to tap into previously under-explored regions. By extending distribution networks, establishing local production facilities, or forming strategic partnerships, companies can gain a foothold in these rapidly growing markets. The rise of middle-class consumers, as well as the growth of regional manufacturing hubs, further supports such strategic expansions. Moreover, governments are often incentivizing local production, which helps boost profitability in these regions.
- For instance, China dominates Asia Pacific with nearly 50% of the region’s KOH output, supported by large-scale chlor-alkali plants and government incentives for green chemical manufacturing.
Key Challenges
Stringent Environmental & Safety Regulations
The production and handling of KOH face strict environmental and safety regulations due to its caustic nature and potential hazards. Meeting chemical-handling standards, waste disposal regulations, and emission rules increases operational costs and complicates near-term capacity expansion, often leading to delays and added investments in compliance measures. These regulatory pressures pose a challenge, especially for new entrants and smaller producers who may lack the resources to invest in costly infrastructure. As such, companies need to stay proactive in maintaining regulatory compliance to avoid penalties or supply disruptions.
Raw Material Price Volatility and Substitutes
Volatility in raw material prices especially potassium salts, natural gas, and energy costs directly impacts manufacturing costs for KOH. Additionally, competition from substitutes such as Sodium Hydroxide (NaOH) can reduce demand or pressure pricing, especially in industries where cost efficiency is a priority. This cost unpredictability, along with substitution risk, constrains margin potential and requires producers to manage supply chains carefully to avoid production interruptions. To mitigate these challenges, some manufacturers are exploring long-term contracts or vertical integration, allowing for more control over raw material sourcing and cost stability.
Regional Analysis
Asia‑Pacific
The Asia‑Pacific region held the largest share of the global KOH market at 39.8% in 2024. Industries in China, India and South Korea drive consumption via chemicals, fertilisers, soaps and detergents. Rapid industrialisation and strong agricultural expansion underpin the demand, while low‑cost production facilities and integrated value chains reinforce regional dominance. In addition, government infrastructure initiatives and supportive policies accelerate adoption of KOH‑based applications across manufacturing and water treatment.
North America
North America accounted for 29.9% of the KOH market in 2024. A solid chemicals sector, advanced detergent and personal‑care manufacturing, and rising demand for alkaline batteries and biodiesel contribute to regional consumption. Mature production infrastructure in the U.S. and Canada supports large‑scale output, while stringent environmental standards encourage higher‑grade KOH use. Market growth is steady and driven by innovation and sustainable chemical processing.
Europe
In Europe, KOH captured 25% of global market share in 2024. The region’s strong chemical and pharmaceutical industries, combined with stringent environmental and sustainability regulations, spur demand for high‑purity grades. Growth is further aided by expanding biodiesel and battery‐electrolyte applications. Western European nations invest in clean manufacturing, which reinforces KOH usage in specialty and industrial segments.
Latin America
Latin America held an estimated 5% share of the KOH market in 2024. Growth is emerging, driven by increasing agricultural fertiliser use in Brazil and Argentina, budding biodiesel production and expansion of chemical manufacturing infrastructure. While the base is smaller compared to developed regions, rising food‑security initiatives and downstream integration of chemical value chains present meaningful upside potential for KOH demand.
Middle East & Africa (MEA)
The Middle East & Africa region accounted for 10% of the global KOH market in 2024. Key demand sources include water desalination, fertilizer blending in arid zones, and petrochemical processing expansions in Gulf states. Population growth, industrialization of petrochemicals and infrastructure investment for wastewater treatment all support KOH uptake. Though smaller in scale than other regions, MEA offers strategic growth opportunities in emerging applications.
Market Segmentations
By Form
- Liquid
- Pellets
- Flakes
- Powder
By Grade
- Industrial Grade
- Food Grade
- Pharmaceutical Grade
By Application
- Soap & Detergent Manufacturing
- Fertilizer Production
- Biodiesel Production
- Chemical Manufacturing
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the global Potassium Hydroxide (KOH) market features several major chemical producers operating on a global scale alongside regionally focused specialists. Key players such as Solvay, BASF SE, Dow Inc., Occidental Petroleum Corporation (through its OxyChem division), Olin Corporation, UNID Co., Ltd., Airedale Chemical Company Limited, American Elements and Altair Chemical S.r.l. all maintain substantial market presence. These firms hold competitive advantages in terms of production capacity, geographic reach, product‑grade diversity and downstream integration. Many invest in manufacturing technologies, sustainability initiatives and specialty grade expansions to differentiate. Smaller regional players compete by focusing on niche grades or local supply chains, leading to a moderately consolidated yet dynamic market structure.
Key Player Analysis
- Dow
- Solvay
- BASF
- Merck KGaA
- Occidental Petroleum Corporation (OxyChem)
- Olin Corporation
- UNID
- Airedale Chemical Company Limited
- American Elements
- Altair Chemical S.r.l.
Recent Developments
- In 2025, South Korean company Unid launched a new potassium hydroxide production plant in Yichang, China, with plans for annual production capacity of 90,000 tons of potassium hydroxide, aiming to become one of the world's largest potassium product bases.
- In July 2024, American Industrial Partners announced it will acquire the sulfuric acid regeneration business of Veolia North America, which includes KOH regeneration as part of its service offering.
- In February 2024, INEOS Inovyn introduced a range of Ultra-Low-Carbon chlor-alkali products, including caustic potash, aimed at significantly lowering the carbon footprint of its products. This initiative utilizes renewable energy at key production sites and is certified under the ISCC PLUS scheme.
Report Coverage
The research report offers an in-depth analysis based on Form, Grade, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Potassium Hydroxide market is set to grow steadily as agriculture and bio‑based sectors increase demand.
- Liquid form will continue dominating while pellets and flakes gain share in mid‑scale and niche applications.
- Industrial grade KOH will maintain its lead, but food and pharmaceutical grades will grow faster due to stricter purity demands.
- Asia‑Pacific will sustain its position as the key region, supported by strong chemical and fertilizer industries and more than 39 % market share.
- North America and Europe will together capture over 50 % of specialty and high‑purity demand in advanced applications.
- New applications in battery electrolytes and green hydrogen will open fresh pathways for KOH usage.
- Sustainable production technologies and energy‑efficient electrolysis will reduce costs and enhance competitiveness.
- Companies will expand in emerging regions like Latin America and MEA to diversify supply and access new demand.
- Raw material cost volatility and strong regulation will keep supplier margins under pressure.
- Substitute chemicals such as sodium hydroxide will remain a competitive restraint for lower‑cost applications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Potassium Hydroxide market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Potassium Hydroxide market projected to grow between 2025 and 2032?
Which Potassium Hydroxide market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Potassium Hydroxide market?
Who are the leading companies in the Potassium Hydroxide market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.44 billion → 2032: USD 4.52 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Potassium Hydroxide Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Potassium Hydroxide Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Potassium Hydroxide Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Potassium Hydroxide Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Potassium Hydroxide Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Potassium Hydroxide Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Potassium Hydroxide Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Potassium Hydroxide Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.44 billion → 2032: USD 4.52 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Potassium Hydroxide Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Potassium Hydroxide Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Potassium Hydroxide Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Potassium Hydroxide Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

