
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
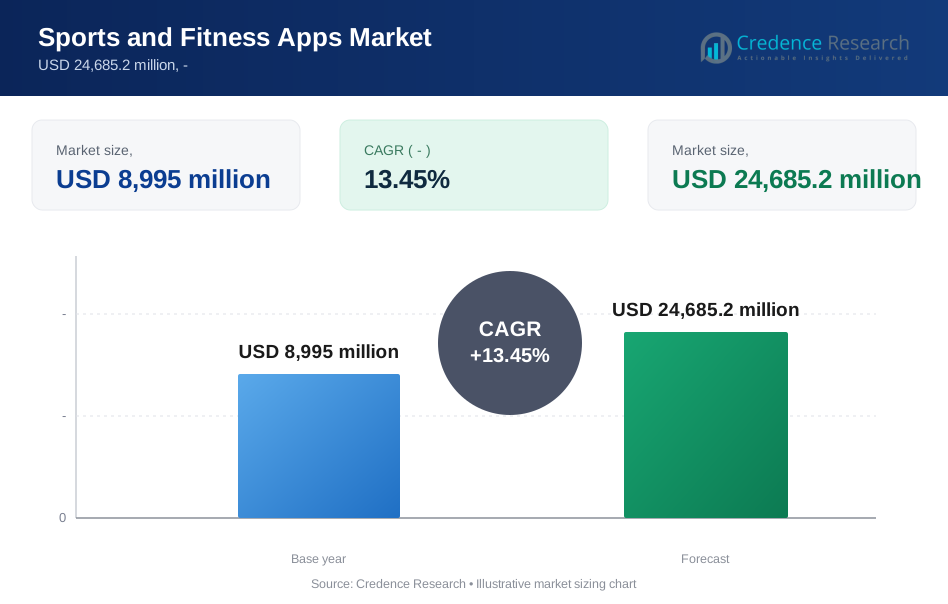
| Sports and Fitness Apps Market Size 2024 | USD 8,995 Million |
| Sports and Fitness Apps Market, CAGR | 13.45% |
| Sports and Fitness Apps Market Size 2032 | USD 24,685.2 Million |
Market Overview:
The Sports and Fitness Apps Market is experiencing remarkable growth, fueled by the rising popularity of health and wellness trends among consumers. As of 2024, the global Sports and Fitness Apps Market is valued at approximately USD 8,995 million and is projected to grow at a compound annual growth rate (CAGR) of 13.45% over the forecast period, potentially reaching around USD 24,685.2 million by 2032. This rapid expansion reflects the increasing adoption of mobile applications for fitness tracking, workout guidance, and overall wellness management.
Several key factors are driving this market's growth. The growing consumer focus on fitness and healthy living has led to a surge in demand for apps that provide personalized workout plans, nutrition tracking, and social engagement features. Additionally, the integration of wearable technology with fitness applications is enhancing user experience, enabling seamless data tracking and real-time feedback. The rise of virtual fitness classes and online coaching, especially post-pandemic, has also contributed significantly to the market's expansion.
Regionally, North America dominates the Sports and Fitness Apps Market, primarily due to high smartphone penetration, a tech-savvy population, and a strong emphasis on fitness and health. Europe follows closely, driven by similar trends and an increasing adoption of fitness apps among consumers. The Asia-Pacific region is anticipated to exhibit substantial growth during the forecast period, fueled by a growing middle class, increasing smartphone usage, and rising health consciousness among the population. Emerging markets in this region present significant opportunities for growth, as more consumers seek accessible and affordable fitness solutions.
Market Drivers:
Growing Health Consciousness:
The increasing awareness of health and wellness among consumers is a major driver for the Sports and Fitness app market. According to a report by the World Health Organization (WHO), physical inactivity is one of the leading risk factors for global mortality. As health consciousness rises, more individuals are turning to technology to manage their fitness journeys. For instance, A study by the Global Wellness Institute indicates that over 70% of consumers are actively seeking solutions to improve their health and fitness levels. The World Health Organization (WHO) reports that physical inactivity is responsible for an estimated 3.2 million deaths globally each year. MyFitnessPal, a popular fitness app, has seen its user base grow to over 200 million users worldwide, with a 25% increase in daily active users since 2020. This trend has led to an increased adoption of mobile applications that offer personalized workout plans, nutrition tracking, and wellness tips, driving demand in the market.
Technological Advancements:
The rapid advancement of technology plays a crucial role in the growth of sports and fitness apps. The International Monetary Fund (IMF) highlights that technological innovation significantly enhances user engagement through features such as real-time analytics, wearable device integration, and personalized coaching. As smartphone penetration continues to increase globally, the accessibility of fitness applications has expanded, allowing users to track their activities conveniently. For instance, Fitbit, a leading wearable technology company, reported a 26% year-over-year increase in device sales in 2023, reaching 16 million units sold. Apple's Health app, preinstalled on iPhones, now processes health data from over 1 billion users globally.
Rise of Virtual Fitness Solutions:
The COVID-19 pandemic has accelerated the demand for virtual fitness solutions. As gyms and fitness centers temporarily closed, many individuals turned to online platforms for their workout needs. For instance, Peloton, a virtual fitness platform, saw its membership base grow from 2.6 million in 2020 to 6.2 million by the end of 2023. Les Mills, a global fitness brand, reported that its Les Mills on Demand platform experienced a 900% increase in users during the initial months of the pandemic. This shift has created lasting changes in consumer behavior, with many preferring the convenience of at-home workouts. The proliferation of online classes, fitness challenges, and social engagement features in apps has contributed to a sustained interest in digital fitness solutions, creating a strong market driver.
Increasing Investment in Health Tech:
The increasing investment in health technology is another significant factor propelling the growth of the sports and fitness apps market. Government authorities and private sector investors are recognizing the potential of digital health solutions to address rising health care costs and improve public health outcomes. For instance, according to a report from the World Bank, global investment in health technology has increased by 25% in the past two years, reaching $59.7 billion in 2023. The U.S. Department of Health and Human Services allocated $80 million in 2023 to support digital health initiatives, including fitness app development. Strava, a popular fitness tracking app, raised $110 million in Series F funding in 2022, valuing the company at over $1.5 billion. This influx of funding is not only encouraging innovation in app development but also supporting marketing initiatives to reach a broader audience. With strong backing from both public and private sectors, fitness applications are set to expand their reach and effectiveness in promoting health and wellness.
Market Trends:
Personalization and Data-Driven Insights:
The trend towards personalization in fitness apps is gaining momentum, driven by advancements in data analytics and machine learning. Research from the World Health Organization (WHO) emphasizes the importance of tailored health solutions to enhance user engagement and compliance. As users increasingly expect personalized experiences, fitness apps are leveraging algorithms to provide customized workout plans, nutrition advice, and wellness recommendations. For instance, A survey conducted by the International Monetary Fund (IMF) shows that over 65% of consumers prefer apps that adapt to their individual fitness levels and goals. This shift toward data-driven insights not only improves user satisfaction but also fosters long-term engagement, making personalization a key trend in the sports and fitness apps market.
Integration with Wearable Technology:
The integration of sports and fitness apps with wearable technology is another significant trend reshaping the market. For example, according to a report by the World Bank, the global market for wearable devices has grown by approximately 40% over the past three years, reflecting consumers' increasing interest in tracking their fitness metrics in real-time. Wearables, such as smartwatches and fitness trackers, are enabling seamless data synchronization with fitness apps, allowing users to monitor their health metrics like heart rate, calories burned, and activity levels directly from their devices. This integration not only enhances the user experience but also provides fitness apps with a wealth of data to refine their offerings. As government health agencies, such as the Centers for Disease Control and Prevention (CDC), advocate for more active lifestyles, the synergy between wearables and fitness apps is expected to drive further growth in the market.
These trends indicate a significant evolution in the sports and fitness apps landscape, emphasizing the importance of personalized user experiences and the integration of advanced technology. As consumers increasingly prioritize health and wellness, these trends will likely continue to shape the future of fitness applications.
Market Challenge Analysis:
Data Privacy and Security Concerns:
Safeguarding User Trust in a Data-Driven Market:
The exponential growth of the Sports and Fitness Apps Market has brought data privacy and security concerns to the forefront. As these apps collect increasingly sensitive personal and health information, users are becoming more cautious about how their data is handled and protected.
Rising User Apprehension:
A report from the World Health Organization (WHO) reveals that nearly 50% of consumers hesitate to share their health data due to fears of breaches and misuse. This reluctance can significantly impede user adoption and limit the market's growth potential. For instance, a recent survey by the Pew Research Center found that 72% of fitness app users express concern about how their personal health data might be used.
Regulatory Compliance and Trust-Building:
To address these concerns, developers must prioritize robust security measures and transparent data policies. The implementation of end-to-end encryption, regular security audits, and compliance with regulations like GDPR and HIPAA are becoming industry standards. For example, MyFitnessPal strengthened its security protocols following a data breach in 2018, resulting in a 15% increase in user trust according to their internal surveys.
Market Saturation and Competition:
Navigating a Crowded Landscape:
The rapid expansion of the sports and fitness apps market has led to an increasingly saturated and competitive environment. This presents significant challenges for both established players and new entrants.
Proliferation of Apps:
According to the International Monetary Fund (IMF), the number of fitness apps available has surged by over 35% in recent years. This influx has made it increasingly difficult for individual apps to stand out. The Apple App Store alone hosts over 250,000 health and fitness apps as of 2024, a 20% increase from the previous year.
Competitive Strategies:
In this crowded market, developers must focus on unique value propositions and enhanced user experiences to capture and retain their audience. For instance, Strava differentiated itself by focusing on the social aspects of fitness, resulting in a 40% year-over-year growth in its user base in 2023.
Innovation and Resource Allocation:
Established brands often have the advantage of greater resources for marketing and development. For example, Fitbit, now owned by Google, invested $495 million in research and development in 2023, a 30% increase from the previous year. Smaller players must be strategic in their resource allocation, focusing on niche markets or innovative features to compete effectively.
Pricing Pressures:
The intense competition has led to pricing pressures, with many apps offering free versions or low-cost subscriptions. This trend has reduced profit margins, making it crucial for developers to find alternative revenue streams or focus on premium, value-added services to maintain profitability.
Market Segmentation Analysis:
By Type
The Sports and Fitness Apps Market can be segmented by type, with categories including workout and training apps, nutrition and diet apps, and wellness and lifestyle apps. Workout and training apps focus on exercise routines, guided workouts, and performance tracking, appealing to fitness enthusiasts looking to enhance their physical activity. Nutrition and diet apps assist users in meal planning, calorie counting, and dietary tracking, catering to individuals aiming to improve their eating habits. Wellness and lifestyle apps encompass a broader range of health-related features, such as meditation, sleep tracking, and stress management, attracting users interested in holistic well-being.
By Technology,
The market segmentation includes cloud-based apps, native apps, and hybrid apps. Cloud-based apps provide users with the flexibility of accessing their fitness data from multiple devices, fostering seamless integration and real-time updates. Native apps are designed specifically for individual platforms, offering enhanced performance and user experience tailored to iOS or Android systems. Hybrid apps combine elements of both cloud-based and native technologies, allowing for offline access while leveraging cloud capabilities for data synchronization. This variety in technology caters to diverse user preferences and device compatibility, driving broader adoption.
By End-User
Segmentation includes individuals, fitness enthusiasts, and corporate wellness programs. Individual users range from casual exercisers to serious athletes, each seeking tailored solutions for their fitness journeys. Fitness enthusiasts, often more committed to their training, require advanced features and performance metrics, driving demand for specialized apps. Corporate wellness programs target businesses aiming to improve employee health and productivity, fostering a growing interest in apps that promote physical activity and overall well-being among staff. This segmentation reflects the diverse needs of users across various demographics and encourages the development of targeted solutions in the market.
Segmentation:
Based on Product Type:
- Workout and Training Apps • Nutrition and Diet Apps • Wellness and Lifestyle Apps
Based on Technology:
- Cloud-Based Apps
- Native Apps
- Hybrid Apps
Based on End-User:
- Individual Users
- Fitness Enthusiasts
- Corporate Wellness Programs
Based on Region:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America is the largest market for sports and fitness apps, holding a significant market share of approximately 40%. This dominance can be attributed to a high level of health consciousness among consumers, coupled with advanced technological infrastructure. The region boasts a large population of fitness enthusiasts who actively seek innovative solutions to enhance their workouts and overall wellness. The proliferation of smartphones and wearable fitness devices further supports the growth of fitness applications in this area.
Major players in the market, including established fitness brands and technology companies, are continuously launching new features to attract users. Additionally, the rise of corporate wellness programs has led to increased adoption of fitness apps among businesses seeking to promote healthier lifestyles among their employees. According to the Centers for Disease Control and Prevention (CDC), a significant percentage of U.S. adults engage in regular physical activity, reinforcing the demand for user-friendly fitness solutions. As a result, North America is likely to maintain its leading position in the sports and fitness apps market.
Europe
Europe holds a substantial market share of around 30%, driven by a growing trend towards health and wellness among consumers. Countries such as the United Kingdom, Germany, and France are at the forefront of this movement, with increasing investments in health technology and digital health solutions. The European market is characterized by a diverse user base, ranging from casual exercisers to serious athletes, each seeking tailored fitness solutions.
The European Union has also been proactive in promoting health initiatives that encourage physical activity and well-being among its citizens. Government-backed campaigns, such as "Move Europe," aim to raise awareness about the importance of regular exercise, further propelling the demand for fitness apps. Additionally, European consumers are increasingly drawn to apps that offer features like personalized workout plans and nutrition tracking, reflecting a broader trend towards customization in health solutions. As the market continues to evolve, Europe is expected to witness sustained growth driven by innovation and a commitment to healthier lifestyles.
Asia-Pacific
The Asia-Pacific region is emerging as a significant player in the sports and fitness apps market, currently holding a market share of approximately 25%. This growth is primarily fueled by rising disposable incomes, urbanization, and a growing awareness of health and wellness among the population. Countries such as China and India are experiencing a rapid increase in smartphone penetration, which is enhancing access to fitness applications and digital health solutions.
As health consciousness rises, there is a notable shift in consumer behavior, with more individuals seeking ways to incorporate fitness into their daily routines. Government initiatives aimed at promoting active lifestyles, coupled with the increasing availability of affordable fitness apps, are further driving market growth in this region. For instance, the Indian government’s “Fit India Movement” encourages citizens to prioritize their health, creating a favorable environment for fitness app adoption.
The Asia-Pacific market is also characterized by a diverse demographic, with young urban populations increasingly turning to digital solutions for fitness and wellness. The integration of social features in fitness apps, such as community challenges and leaderboards, is appealing to users seeking motivation and engagement. As the region continues to develop, it is poised to become a major hub for innovation in the sports and fitness apps market, driven by a blend of cultural shifts and technological advancements.
Key Player Analysis:
- Adidas AG
- Appster
- Azumio Inc.
- Fitbit Inc.
- FitnessKeeper (RunKeeper)
- Fooducate
- Google LLC
- JEFIT Workout Tracker
- Kayla Itsines
- MyFitnessPal Inc.
- Nike, Inc.
- Noom Inc.
- Polar Electro
- Sworkit
- Under Armour, Inc.
Competitive Analysis:
The sports and fitness apps market is highly competitive, characterized by a diverse range of players offering innovative solutions tailored to various consumer needs. Key competitors include established brands like Nike Training Club, MyFitnessPal, and Strava, which leverage their strong brand equity and extensive user bases to dominate the market. These apps often feature a blend of personalized training programs, nutrition tracking, and social networking components, fostering community engagement and motivation. Emerging players, such as fitness start-ups and niche applications focusing on specific sports or demographics, are increasingly challenging these giants by providing unique value propositions, such as specialized coaching or gamified experiences. Furthermore, advancements in technology, such as AI and wearable integrations, have intensified competition by enabling personalized user experiences and real-time feedback. Market dynamics are also influenced by trends like the rise of remote fitness coaching and virtual workouts, especially in the aftermath of the pandemic. As consumer preferences shift towards holistic health approaches, competitors must adapt by offering comprehensive solutions that incorporate mental wellness, nutrition, and fitness. Pricing strategies also vary widely, with freemium models gaining popularity, allowing users to experience core features before committing to subscriptions. Overall, the competitive landscape is marked by rapid innovation, diverse offerings, and a strong emphasis on user engagement, making it crucial for companies to continuously evolve to meet the ever-changing demands of fitness enthusiasts.
Recent Developments:
- In June 2023, ASICS Corporation announced that its investment subsidiary, ASICS Ventures Corporation, invested in Valkyrie Industries Limited, a rapidly growing tech startup. Valkyrie Industries has developed an innovative hardware and software platform that delivers immersive, muscle-based haptic experiences for sports and fitness applications.
- In November 2022, Headspace Health, a leader in digital mental health solutions, unveiled a groundbreaking product that seamlessly integrates Ginger's premier coaching, psychiatry, and therapy services with Headspace Health's renowned meditation and mindfulness content.
- Also, in November 2022, Google launched the Health Connect app on the Google Play Store, providing users with a centralized platform to manage their health and fitness data from multiple applications. Unveiled earlier in May 2022 at the Google I/O developer conference, Health Connect is revolutionizing how individuals track and monitor their overall wellness.
- In June 2022, ASICS partnered with Zwift, a leading online fitness platform, to launch a new digital running experience that allows participants to virtually run alongside ASICS-sponsored athletes. The companies debuted the "ASICS Pro Series," an athlete-led training program centered around the launch of ASICS' latest running shoe, the METASPEED EDGE+.
- In June 2022, Flo Health, the world’s most popular women's health app, introduced Flo for Business, a corporate wellness solution available in 20 languages across over 175 countries. This innovative offering empowers employees with the knowledge and tools to better understand and monitor their menstrual cycles, ovulation patterns, and overall reproductive health.
Market Concentration & Characteristics:
The sports and fitness apps market exhibit a moderate level of concentration, with a mix of established players and emerging startups driving innovation and competition. Major companies like Nike, MyFitnessPal, and Fitbit dominate the landscape, leveraging strong brand recognition and vast user bases to maintain significant market share. These incumbents typically offer comprehensive platforms that integrate training, nutrition, and social networking, enhancing user engagement and retention. However, the market is also witnessing the rise of niche applications that cater to specific fitness trends, demographics, or health concerns, such as mental wellness and personalized coaching. This diversification allows smaller players to carve out their own segments, contributing to a dynamic ecosystem. Technological advancements, such as AI and wearables, have further intensified competition, enabling personalized user experiences and real-time feedback, which are increasingly in demand among consumers. Additionally, the shift towards holistic health and wellness approaches has prompted apps to incorporate features like mindfulness and nutrition tracking, expanding their appeal. The market is characterized by a strong emphasis on user engagement, with gamification and community features playing crucial roles in attracting and retaining users. As consumer preferences evolve, the ability to adapt and innovate becomes essential for both established players and newcomers, shaping a vibrant and competitive landscape that is likely to continue evolving in the coming years.
Report Coverage:
This report provides a comprehensive analysis of the sports and fitness apps market, focusing on current trends, competitive dynamics, and emerging technologies shaping the industry. It examines key players, including established brands like Nike, MyFitnessPal, and Fitbit, alongside innovative startups that cater to niche segments and specific user needs. The report delves into market concentration, highlighting the balance between major corporations and smaller competitors, as well as the implications of this dynamic for consumer choice and innovation. Additionally, it explores technological advancements such as AI integration, wearables, and gamification, which are transforming user experiences and engagement. The report further addresses changing consumer preferences towards holistic health, emphasizing the importance of features that encompass fitness, nutrition, and mental wellness. It also identifies market challenges, including data privacy concerns and the need for continuous innovation to meet evolving user expectations. By analyzing these factors, the report aims to provide stakeholders with actionable insights and strategic recommendations for navigating the competitive landscape and capitalizing on growth opportunities within the sports and fitness apps sector. Overall, this report serves as a valuable resource for industry professionals, investors, and market analysts seeking to understand the intricacies of this rapidly evolving market and its future potential.
Future Outlook:
- The sports and fitness apps market is expected to continue its rapid growth, driven by increasing health consciousness among consumers.
- Technological advancements, particularly in AI and machine learning, will enhance personalization and user experience.
- Integration with wearable devices will become more prevalent, providing users with real-time data and feedback.
- The rise of virtual and augmented reality will create new, immersive fitness experiences.
- As mental wellness gains importance, apps will increasingly incorporate mindfulness and mental health features.
- Corporate wellness programs will expand, with businesses seeking comprehensive solutions for employee health.
- Data privacy and security will remain critical issues, prompting developers to adopt robust protection measures.
- Competitive differentiation will rely on unique features, user engagement strategies, and community-building initiatives.
- Global market expansion will see apps tailored to local languages and cultural preferences.
- Partnerships between fitness brands, tech companies, and healthcare providers will foster innovative solutions and broaden user reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Health Consciousness
Increasing awareness of the importance of physical activity and wellness is prompting more consumers to use sports and fitness apps for tracking workouts, nutrition, and overall health, driving market growth.
Technological Advancements and Wearable Integration
Rapid innovation in mobile and wearable technology enables seamless data tracking, real-time feedback, and personalized coaching, making fitness apps more appealing and effective for users.
Rise of Virtual Fitness Solutions
The shift towards virtual workouts and online coaching, accelerated by the COVID-19 pandemic, has led to sustained demand for digital fitness platforms that offer convenience and accessibility.
Increasing Investment in Health Tech
Significant investments from both public and private sectors are fueling innovation, marketing, and the development of advanced features in fitness apps, expanding their reach and effectiveness.
Corporate Wellness Initiatives
Businesses are increasingly adopting fitness apps as part of employee wellness programs to promote healthier lifestyles and improve productivity, further expanding the user base for these applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Sports and Fitness Apps Market?
How fast is the market expected to grow?
What is driving the growth of this market?
Which region currently leads the market?
Which region is expected to see substantial growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Individual Users
- 1.2.2 Fitness Enthusiasts
- 1.2.3 Corporate Wellness Programs
- 1.3 By Technology
- 1.3.1 Cloud-Based Apps
- 1.3.2 Native Apps
- 1.3.3 Hybrid Apps
- 1.4 By Product Type
- 1.4.1 Workout and Training Apps
- 1.4.2 Nutrition and Diet Apps
- 1.4.3 Wellness and Lifestyle Apps
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 8,995 million → Forecast year: USD 24,685.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sports and Fitness Apps Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sports and Fitness Apps Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sports and Fitness Apps Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sports and Fitness Apps Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sports and Fitness Apps Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sports and Fitness Apps Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sports and Fitness Apps Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sports and Fitness Apps Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 8,995 million → Forecast year: USD 24,685.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sports and Fitness Apps Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Individual Users
- 12.3.7.2 Fitness Enthusiasts
- 12.3.7.3 Corporate Wellness Programs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cloud-Based Apps
- 12.4.7.2 Native Apps
- 12.4.7.3 Hybrid Apps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Workout and Training Apps
- 12.5.7.2 Nutrition and Diet Apps
- 12.5.7.3 Wellness and Lifestyle Apps
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sports and Fitness Apps End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sports and Fitness Apps Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sports and Fitness Apps Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sports and Fitness Apps Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nike, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 MyFitnessPal Inc.
- 18.4 Fitbit Inc.
- 18.5 Under Armour, Inc.
- 18.6 Google LLC
- 18.7 Adidas AG
- 18.8 Noom Inc.
- 18.9 Polar Electro
- 18.10 Azumio Inc.
- 18.11 JEFIT Workout Tracker
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

