
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sports Streaming Platform Market Size 2024 | USD 20,728.00 Million |
| Sports Streaming Platform Market, CAGR | 22.4% |
| Sports Streaming Platform Market Size 2032 | USD 104,426 Million |
Market Overview:
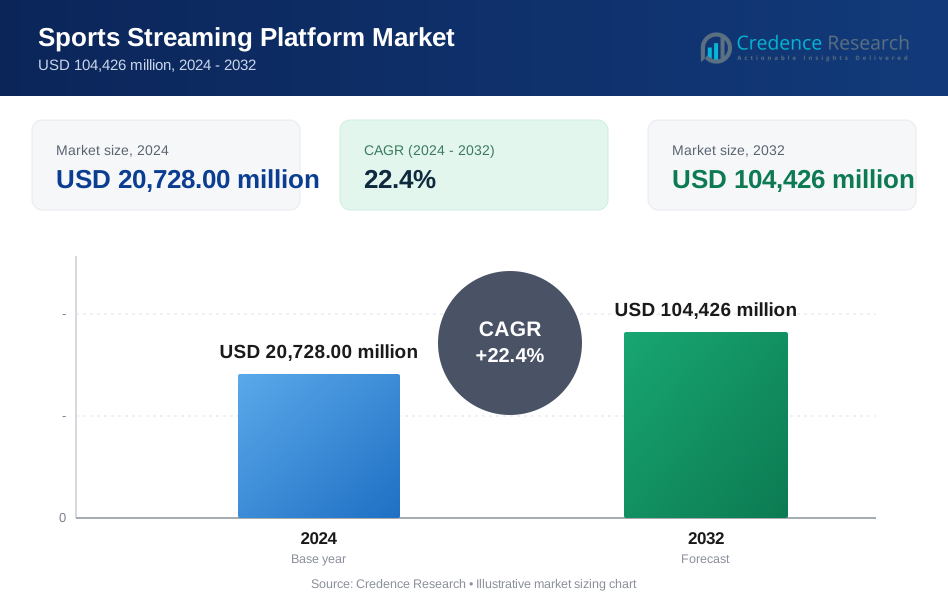
The Sports Streaming Platform Market size was valued at USD 20,728.00 million in 2024 and is anticipated to reach USD 104,426 million by 2032, at a CAGR of 22.4% during the forecast period (2024-2032).
The increasing popularity of live sports streaming is driven by widespread mobile device penetration, improved internet infrastructure, and the rising number of exclusive broadcasting rights secured by streaming platforms. As more consumers shift from traditional cable subscriptions to on-demand digital content, streaming services are leveraging advanced technologies to enhance the viewing experience. Leading sports leagues, such as the NFL, NBA, UEFA Champions League, and IPL, are actively forming partnerships with streaming platforms to tap into a global audience. These collaborations ensure exclusive coverage, multi-platform accessibility, and premium content offerings, making it easier for fans to access their favorite sports anytime and anywhere. Furthermore, advancements in interactive features—including multi-camera viewing options, real-time game analytics, and virtual reality (VR) integration—are significantly enriching audience engagement. Many platforms are also integrating social media-driven interactions, enabling users to share live reactions, participate in polls, and discuss matches in real-time. The availability of subscription-based, freemium, and ad-supported models ensures greater flexibility for consumers, allowing them to choose plans based on their preferences and affordability.
In terms of regional dynamics, North America leads the sports streaming platform market, benefiting from the strong presence of key industry players, high consumer expenditure on digital entertainment, and the widespread adoption of connected devices such as smart TVs, tablets, and gaming consoles. The European market is experiencing rapid expansion, fueled by increasing investments in localized sports streaming services and the rising demand for country-specific sports content. The Asia-Pacific region is anticipated to witness the fastest growth, primarily due to affordable internet access, rising smartphone adoption, and a growing demand for both regional and international sports leagues. Countries such as India, China, and Japan are at the forefront of this growth, with a surge in mobile streaming consumption and partnerships between sports leagues and digital platforms. Meanwhile, Latin America and the Middle East & Africa are gradually gaining traction as streaming platforms localize their offerings, collaborate with regional content providers, and expand multilingual streaming options to cater to diverse audiences.
Market Insights:
- The Sports Streaming Platform Market is projected to grow from USD 20,728.00 million in 2024 to USD 104,426 million by 2032, at a CAGR of 22.4%. Increasing demand for on-demand sports content and digital streaming services is fueling market expansion.
- The shift from traditional cable TV to over-the-top (OTT) streaming services is a key driver, with subscription-based, freemium, and ad-supported models enhancing accessibility.
- Streaming platforms are securing exclusive rights for major sports leagues, such as the NFL, NBA, UEFA Champions League, and IPL, increasing their competitive advantage.
- Bandwidth limitations, high data consumption, and licensing fees pose challenges, restricting smaller players from entering the market.
- The region dominates due to high digital adoption, strong internet infrastructure, and major streaming players.
- Increasing smartphone penetration, affordable data plans, and growing sports viewership are driving demand in countries like India and China.
- Features like multi-camera angles, real-time analytics, VR integration, and social media interactivity are improving user experience and retention.
Market Drivers:
Rising Digital Penetration and OTT Adoption
The rapid expansion of digital infrastructure and high-speed internet connectivity has significantly influenced the growth of sports streaming platforms. For instance, by 2025, the number of US viewers who stream sports events at least once a month is projected to exceed 90 million, a substantial increase from 57 million in 2021. This increasing internet access has facilitated seamless streaming experiences, reducing latency and buffering issues that previously hindered live sports viewership. Companies like Netflix and Amazon Prime Video have demonstrated how high-quality, on-demand content consumption is transforming user behavior, encouraging more sports leagues and broadcasters to shift towards direct-to-consumer (DTC) streaming models.
Exclusive Content and League Partnerships
The growing competition among streaming platforms has led to an aggressive push for exclusive broadcasting rights for major sporting events. For instance, DAZN and the European League of Football (ELF) signed an eight-year partnership in January 2025 to broadcast all 101 games of the 2025 season across 200 markets. This trend extends beyond traditional sports, as streaming platforms diversify their content offerings to attract new audiences.
Advancements in Streaming Technology and AI Integration
Technological innovations have played a critical role in enhancing user engagement and delivering high-definition sports content with minimal lag. Additionally, artificial intelligence (AI) and machine learning are revolutionizing content personalization, with the NFL's partnership with AWS for Next Gen Stats collecting and processing about 500 million data points per season and introducing new stats like "Tackle Probability" in 2024. AI-driven analytics are now powering real-time stats and game highlights in the NFL's official app, creating a more immersive viewing experience.
Government Support and Regulatory Frameworks
Governments worldwide are increasingly supporting the digital transformation of sports broadcasting by reforming media regulations and ensuring fair market competition. Additionally, the Ministry of Information and Broadcasting is expanding broadcasting services by auctioning licenses for 730 new private FM channels across 234 cities. the government is considering allowing private FM radio channels to broadcast news bulletins, diversifying news sources beyond state-run media.
Market Trends
Rise of 5G-Enabled Streaming for Seamless User Experience
The expansion of 5G networks is revolutionizing sports streaming by delivering low-latency, high-definition (HD) content to users globally. For instance, 5G subscriptions are rising in every region worldwide and reached 1.5 billion by the end of 2023, with continued revenue growth in leading markets. This enhanced network infrastructure is significantly improving live-streaming capabilities, reducing buffering times, and enabling ultra-high-definition (UHD) and 8K video quality. In stadiums with 5G, Verizon can offer seven streams of HD video to a smartphone, allowing fans to control viewing angles and access instant replays
Growing Integration of AI and Machine Learning in Content Delivery
Artificial intelligence (AI) and machine learning (ML) are playing a crucial role in optimizing content personalization and enhancing viewer experiences. For instance, machine learning algorithms analyze video frames in real-time, optimizing resolution and frame rate to deliver a seamless viewing experience. Streaming platforms are adopting AI-driven technologies to offer real-time game analytics, automatic highlights, and personalized content recommendations. AI algorithms can upscale lower-resolution videos to higher resolutions, reduce noise, and enhance color accuracy in real-time processing. Furthermore, AI-powered automated camera tracking and motion analysis are enabling platforms to generate insights, with the NFL's partnership with AWS collecting and processing about 500 million data points per season and introducing new stats like "Tackle Probability" in 2024.
Expansion of Cloud-Based Streaming and Subscription Flexibility
The adoption of cloud-based content distribution is reshaping the sports streaming landscape by ensuring scalability, global accessibility, and cost efficiency. Leading cloud providers are partnering with sports broadcasters to deliver high-performance streaming solutions. streaming platforms are offering tiered subscription plans, with one monthly price for access and another more costly monthly price for access without ads. Additionally, the rise of flexible subscription models is gaining traction, with platforms offering pay-per-view (PPV), ad-supported (AVOD), and hybrid subscription tiers.
Emergence of Interactive and Immersive Viewing Experiences
Sports streaming platforms are increasingly integrating virtual reality (VR), augmented reality (AR), and interactive engagement tools to redefine fan experiences. Streaming platforms are enhancing viewer engagement with features like augmented reality overlays, interactive stats, and multi-angle viewing. U.S. viewers who stream sports events at least once a month are projected to exceed 90 million by 2025, up from 57 million in 2021. Additionally, platforms like Tubi have revamped their mobile platforms to offer exclusive experiences, though only about 46% of streaming users choose smartphones as their primary viewing device
Market Challenges Analysis
High Infrastructure and Licensing Costs
The sports streaming industry faces significant financial challenges due to the high costs associated with content licensing, bandwidth consumption, and infrastructure upgrades. Streaming exclusive sports content requires multi-billion-dollar contracts, making it difficult for smaller players to compete. For instance, the National Football League (NFL) signed an 11-year, USD 105 billion deal with broadcasters and digital platforms, significantly increasing the financial burden on streaming providers. Additionally, video delivery costs are rising, with a report from the U.S. Federal Communications Commission (FCC) indicating that streaming platforms spend up to 40% of their revenue on content distribution and bandwidth expansion. The increasing costs of server storage, cloud computing, and network infrastructure further limit the entry of new players, leading to market consolidation.
Governments worldwide are enforcing strict regulatory policies on digital broadcasting and data privacy, posing compliance challenges for streaming platforms. The European Union’s Digital Services Act (DSA) of 2023 mandates greater transparency in digital content distribution, requiring platforms to disclose content licensing agreements and user data management policies.
Piracy and Unauthorized Content Distribution
The rise of illegal streaming websites and content piracy is a major challenge for sports streaming platforms, causing significant revenue losses. A 2023 study by the World Intellectual Property Organization (WIPO) found that over 70 million users globally access unauthorized sports streams each month, leading to an estimated annual revenue loss of USD 28 billion for legitimate broadcasters. Platforms like Sky Sports and ESPN have invested in digital rights management (DRM) technologies, but cybercriminals continuously adapt, making piracy control difficult. The U.S. Department of Justice (DOJ) and Europol have ramped up enforcement efforts, shutting down multiple illegal sports streaming networks, but the demand for free access remains a persistent issue. Despite the global rise in streaming adoption, internet connectivity issues in developing regions hinder market penetration. According to a 2023 report by the International Telecommunication Union (ITU), over 2.7 billion people still lack reliable internet access, particularly in Africa, South Asia, and Latin America.
Market Opportunities
The increasing global demand for on-demand sports content presents a significant growth opportunity for sports streaming platforms. As consumer preferences shift toward digital-first entertainment, the expansion of 5G networks and broadband infrastructure is creating new possibilities for high-quality, real-time sports streaming. According to the International Telecommunication Union (ITU), global 5G adoption is expected to reach 4.6 billion users by 2028, significantly improving streaming speeds and reducing latency. This advancement will enable platforms to enhance their service offerings, including ultra-high-definition (UHD) streaming, multi-angle views, and real-time engagement features. Furthermore, emerging markets in Asia, Africa, and Latin America offer untapped potential, with millions of new digital consumers expected to enter the streaming ecosystem as internet accessibility improves. Companies investing in localized content, regional language broadcasts, and affordable subscription models can capitalize on this expanding user base.
Another major opportunity lies in the integration of immersive technologies and personalized user experiences. Innovations in artificial intelligence (AI), augmented reality (AR), and virtual reality (VR) are transforming how sports fans engage with live content. Meta and Sony Interactive Entertainment are investing heavily in VR-based sports streaming, offering 360-degree stadium views for a more immersive experience. Additionally, the rise of blockchain-powered digital collectibles and fan tokens is creating new revenue streams for streaming providers, as seen with Formula 1 and LaLiga’s NFT-based fan engagement initiatives. As consumer demand for interactive and community-driven sports content grows, streaming platforms that adopt these technologies will gain a competitive edge in the evolving market.
Market Segmentation Analysis:
By Pricing Model
The sports streaming platform market is segmented based on pricing models, including subscription-based (SVOD), advertising-supported (AVOD), pay-per-view (PPV), and hybrid models. Subscription-based streaming dominates the market, with major platforms like ESPN+, DAZN, and Amazon Prime Video offering exclusive sports packages through monthly or annual plans. According to PwC’s 2023 Global Entertainment & Media Outlook, over 60% of sports streaming revenue is generated through SVOD services, as consumers prefer ad-free, premium content. Meanwhile, advertising-supported platforms, such as YouTube and Pluto TV, are gaining traction, particularly in emerging markets, where cost-conscious viewers opt for free content supported by targeted advertisements. The pay-per-view model remains relevant for high-profile sporting events, with boxing, mixed martial arts (MMA), and wrestling promotions leveraging PPV strategies to maximize revenue.
By Platform
Sports streaming platforms cater to users across smartphones, tablets, smart TVs, gaming consoles, and web-based applications. Mobile streaming leads the market, driven by the increasing penetration of 5G networks and affordable data plans, particularly in Asia-Pacific and Latin America. A 2023 report by Ericsson highlights that over 75% of global sports content is consumed on mobile devices, emphasizing the shift toward on-the-go viewing. Smart TV applications and gaming consoles are also gaining popularity, with companies like Sony PlayStation and Microsoft Xbox integrating dedicated sports streaming apps into their ecosystems. The demand for cross-platform accessibility is rising, prompting platforms to optimize content delivery across multiple devices for a seamless user experience.
Segmentations:
By Pricing Model:
- Sports Streaming Platform
- Cloud Based
- On-Premises
- Services
- Professional Services
- Consulting Services
- Training and Education
- Support & Maintenance Services
- Managed Services
- Professional Services
By Platform:
- Web-based
- App-based
- Sports Type
- American Football
- Soccer
- Hockey
- Boxing
- Cricket
- Volleyball
- Rugby
- Baseball
- Motorsport
- Racket Sports
- Others
By Region:
- North America
- Latin America
- Europe
- Asia Pacific
- Middle East & Africa
Regional Analysis:
North America:
North America holds the largest share of the sports streaming platform market, accounting for 40% of the global revenue. The region’s dominance is fueled by high digital adoption rates, strong internet infrastructure, and a tech-savvy consumer base. Additionally, cord-cutting trends are accelerating as consumers shift to digital platforms. a study revealed that 55% of U.S. households had abandoned traditional cable TV by 2023, preferring on-demand sports content from streaming platforms. Major streaming services have capitalized on this transition by securing exclusive broadcasting rights. ESPN+ signed a multi-year deal worth USD 2.7 billion for exclusive NHL streaming rights, while Amazon Prime Video secured a USD 11 billion contract for Thursday Night Football coverage, further strengthening their market dominance.
Europe:
Europe represents 25% of the global sports streaming platform market, driven by the growing localization of sports content and supportive regulatory frameworks. Countries such as Germany, the UK, and France are leading the market as consumers increasingly prefer personalized, region-specific sports content. DAZN secured a USD 2.9 billion deal for Bundesliga rights, while Sky Sports extended its Premier League broadcasting contract to 2028 for USD 8.1 billion. The shift toward AI-driven content personalization is also reshaping the European market. over 70% of UK sports fans prefer AI-recommended content, as per a 2023 Ofcom survey, highlighting the role of machine learning algorithms in enhancing viewer engagement.
Asia-Pacific:
Asia-Pacific accounts for 20% of the global sports streaming market and is the fastest-growing region, driven by affordable internet access, increasing smartphone penetration, and rising demand for live sports content. India and China are key contributors to this growth. Disney+ Hotstar amassed over 50 million subscribers due to its exclusive Indian Premier League (IPL) coverage, while Tencent Sports recorded over 200 million monthly active users streaming Chinese Super League matches. The region is also witnessing a rise in freemium and ad-supported models, making sports content more accessible. Sony Liv reported a 40% increase in ad-supported viewership after launching free-tier live sports streaming options, expanding its user base significantly.
Latin America & Middle East & Africa:
Latin America and the Middle East & Africa (MEA) collectively hold 15% of the global sports streaming market, with growing internet penetration and investments in localized sports content driving demand. Football remains the dominant driver of streaming demand. Brazil saw a 35% increase in LaLiga streaming subscriptions following a partnership between Movistar+ and Star+, while Mexico recorded a 28% rise in Copa Libertadores digital viewership in 2023. MEA is also experiencing rapid growth due to government-backed digital transformation initiativesPlatforms like beIN Sports and StarzPlay are leveraging regional-language content strategies, capturing a 30% rise in Arabic sports streaming viewership across MEA in 2023.
Key Player Analysis:
- Amazon
- DAZN Limited
- Disney
- ESPN Enterprises, Inc.
- fuboTV Inc.
- Hulu, LLC
- LAOLA1.tv
- Sony Pictures Networks India Pvt. Ltd.
- Sling TV L.L.C.,
- Vimeo, Inc
Competitive Analysis:
The sports streaming platform market is highly competitive, with key players investing in exclusive broadcasting rights, advanced technology, and regional expansion. Amazon Prime Video secured a deal for exclusive Thursday Night Football rights, capitalizing on 55% of U.S. households shifting to digital streaming, as per Pew Research.. In Europe, DAZN’s USD 2.9 billion Bundesliga contract benefits from a 70% increase in streaming preference among UK sports fans, per Ofcom. Sky Sports renewed its Premier League rights for USD 8.1 billion, leveraging digital demand. Disney+ Hotstar’s IPL exclusivity pushed it past 50 million subscribers, while Tencent Sports saw 200 million users streaming the Chinese Super League, aided by China’s expanding 5G adoption, per ITU. AI-driven personalization and VR innovations further fuel competition.
Recent Developments:
- In January 2025, Amazon Prime Video Shifted strategic focus towards live sports content with a $3 billion annual investment in sports broadcasting rights, aiming for profitability by end of 2025.
- In February 2025, DAZN Limited Set to account for one-third of global streaming sports rights expenditure following a deal for the 2025 FIFA Club World Cup
- In February 2024, Disney/ESPN Announced collaboration with Fox and Warner Brothers Discovery to launch a new streaming sports service in fall 2025
- In February 2025, Sony Pictures Networks Secured television broadcast rights for Pakistan Cricket Board's home cricket series and 2025 Pakistan Super League (PSL), covering multiple regions including India, Nepal, and Bhutan.
Market Concentration & Characteristics:
The sports streaming platform market is moderately concentrated, with a mix of global leaders and regional players competing for market share. Major platforms such as Amazon Prime Video, ESPN+, DAZN, and Disney+ Hotstar dominate the industry through exclusive broadcasting rights, AI-driven content personalization, and strategic regional expansions. Amazon secured a USD 11 billion deal for Thursday Night Football, while DAZN holds a USD 2.9 billion Bundesliga contract, strengthening their competitive positions. The market is characterized by technological innovation, increasing adoption of freemium models, and AI-powered user engagement strategies. Tencent Sports leverages AI-driven match insights for over 200 million active users, while Meta and Sony Interactive Entertainment are investing in VR-integrated sports experiences worth over USD 1.2 billion. The growing shift from traditional cable to digital streaming, coupled with rising 5G penetration, is further driving market competition and user engagement.
Report Coverage:
The research report offers an in-depth analysis based on pricing model, platform, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Streaming platforms will enhance user experience through AI-driven content recommendations, automated highlights, and real-time game analytics, improving engagement and retention rates.
- The rollout of 5G networks will enable seamless live streaming with ultra-low latency and enhanced video quality, attracting more mobile users to sports streaming services.
- Platforms will integrate multi-angle viewing, VR-based stadium experiences, and real-time fan engagement tools, transforming how audiences consume live sports content.
- Streaming providers will continue securing exclusive broadcasting rights for major sports leagues, strengthening their competitive edge over traditional broadcasters.
- To expand their user base, platforms will offer hybrid pricing models, allowing access to select content for free while monetizing through targeted advertisements.
- The demand for localized sports coverage in native languages will grow, leading to expanded partnerships between streaming services and regional leagues.
- Cloud-based technology will enhance scalability and global content distribution, ensuring uninterrupted streaming across diverse geographies.
- The use of NFTs, fan tokens, and blockchain-based ticketing will create new revenue streams for streaming platforms and sports organizations.
- Governments will introduce stricter regulations on content licensing, data privacy, and fair competition, reshaping the market dynamics.
- More sports leagues will launch their own DTC platforms, reducing dependence on third-party streaming providers and increasing profitability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Sports Streaming Platform Market?
What factors are driving the growth of the Sports Streaming Platform Market?
What are some challenges faced by the Sports Streaming Platform Market?
Who are the major players in the Sports Streaming Platform Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Sports Streaming Platform Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Sports Streaming Platform Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 20,728.00 million → 2032: USD 104,426 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Sports Streaming Platform Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Sports Streaming Platform Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Sports Streaming Platform Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Sports Streaming Platform Market Drivers
- 3.3 Sports Streaming Platform Market Restraints & Challenges
- 3.4 Sports Streaming Platform Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Sports Streaming Platform Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Sports Streaming Platform Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Sports Streaming Platform category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Sports Streaming Platform Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Sports Streaming Platform Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Sports Streaming Platform market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Sports Streaming Platform Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Sports Streaming Platform Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Sports Streaming Platform Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Sports Streaming Platform (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Sports Streaming Platform Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Sports Streaming Platform Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Sports Streaming Platform Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Sports Streaming Platform Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Sports Streaming Platform Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Sports Streaming Platform Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Sports Streaming Platform Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Sports Streaming Platform Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Sports Streaming Platform Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
