
Market Overview:
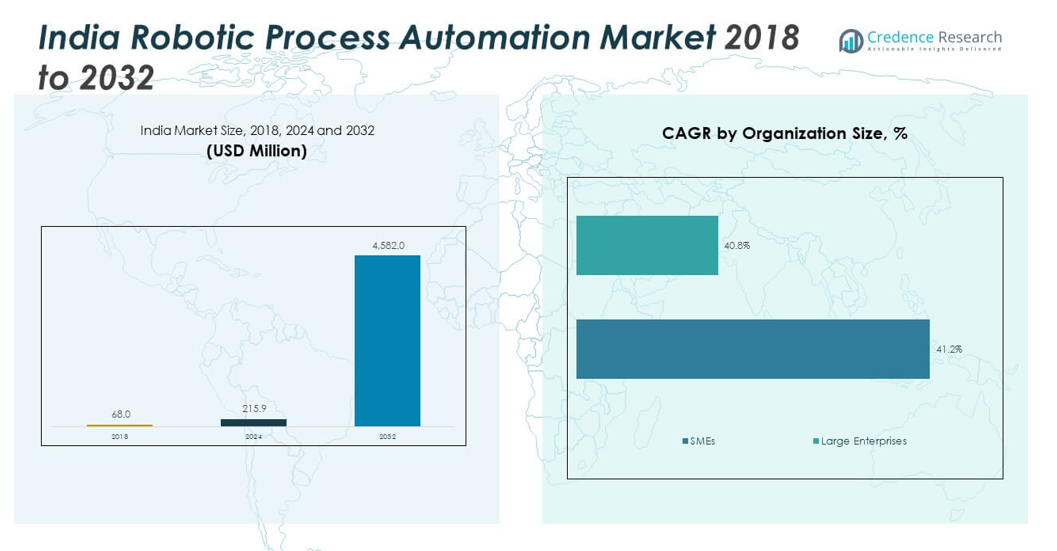
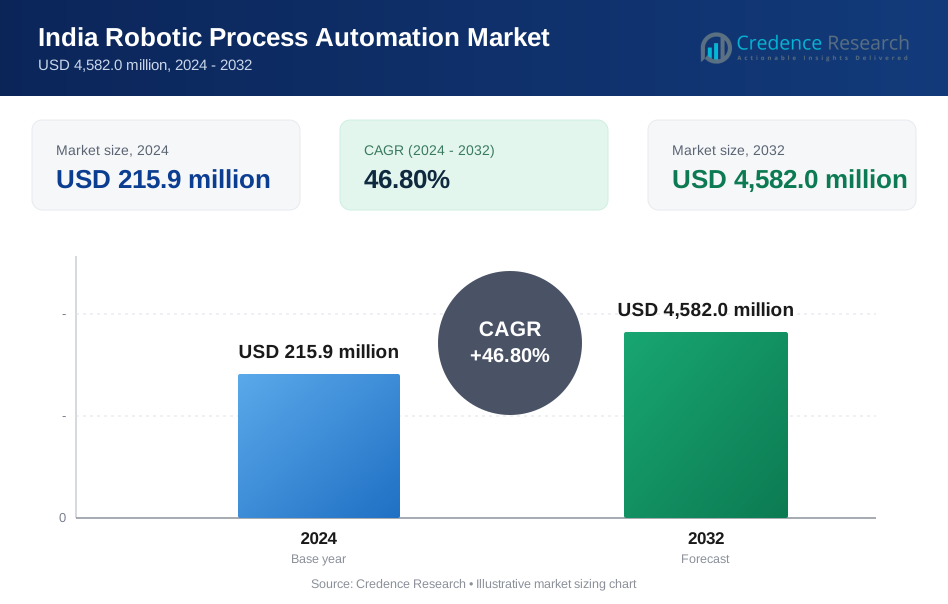
The India Robotic Process Automation Market size was valued at USD 68.0 million in 2018 to USD 215.9 million in 2024 and is anticipated to reach USD 4,582.0 million by 2032, at a CAGR of 46.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Robotic Process Automation Market Size 2024 | USD 215.9 million |
| India Robotic Process Automation Market, CAGR | 46.80% |
| India Robotic Process Automation Market Size 2032 | USD 4,582.0 million |
Strong growth comes from steady digital transformation across key sectors. Banks use RPA to manage onboarding, verification, and compliance checks with better accuracy. Telecom units deploy bots to handle service requests and lift customer response quality. IT companies use automation to streamline back-office tasks and optimize support work. Rising demand for scalable automation drives investment in intelligent bots. Vendors integrate AI-driven features to boost decision support. This shift helps many firms lower manual workload and improve cycle time.
Regional interest grows across major Indian hubs. South India leads due to strong IT clusters and a large technology workforce. Western states show fast adoption because of strong enterprise presence across finance, telecom, and shared service units. Northern cities expand automation in public services and large corporate groups. Eastern regions start to pick up adoption as local firms modernize processes. Tier-2 cities emerge as new adopters because digital services expand and cloud platforms lower deployment barriers.
Market Insights:
- The India Robotic Process Automation Market was valued at USD 68.0 million in 2018, reached USD 215.9 million in 2024, and is projected to hit USD 4,582.0 million by 2032 at a 80% CAGR, reflecting rapid enterprise automation growth.
- South India (38%), West India (27%), and North India (22%) lead market share due to strong IT hubs, BFSI concentration, and large enterprise clusters that drive high-volume automation adoption.
- East and Central India, together at 13%, represent the fastest-growing region supported by rising cloud deployment, expanding digital services, and increasing RPA use across public and mid-size organizations.
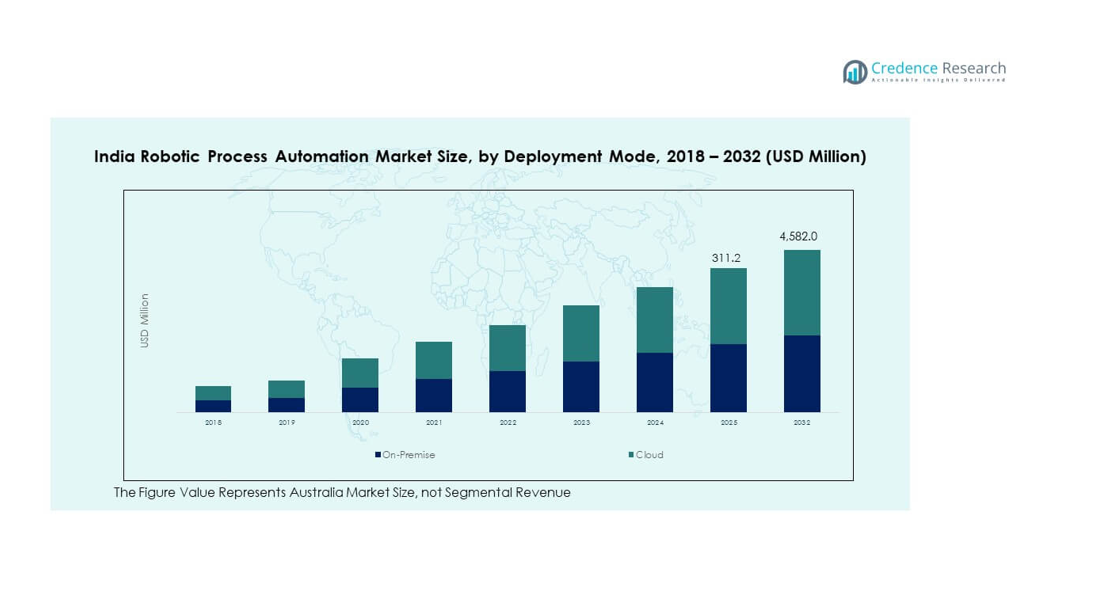
- Based on the deployment-mode chart, Cloud holds about 68% share in 2024, supported by scalable platforms and faster deployment across enterprises shifting toward flexible automation environments.
- On-premise accounts for roughly 32% share in 2024, driven by demand from regulated sectors such as BFSI and government that require strict data control and secure workflow environments.
Market Drivers:
Strong Push Toward Enterprise-Wide Automation Across Core and Support Functions
The India Robotic Process Automation Market gains steady traction through rising automation in banking, telecom, and IT. Many firms adopt bots to replace repetitive manual tasks and lift process quality. The shift supports faster turnaround in routine workflows across operations and finance units. Leaders use digital labor to improve error control and boost compliance levels. Cloud-first policies encourage large companies to scale automation across teams. Strong vendor presence helps companies deploy bots with lower friction. Local service providers support integration, customization, and managed automation layers. The trend improves workforce productivity across many sectors.
- For instance, UiPath confirmed serving more than 10,800 customers worldwide, enabling large enterprises to automate thousands of workflow steps across operational teams.
Growing Adoption of AI-Driven Bots That Improve Decision Support and Accuracy
AI-linked tools strengthen automation by enabling classification, extraction, and rule-based decision activity. Many enterprises use cognitive bots to process documents with higher accuracy. Automation teams deploy these tools to improve exception handling and boost workflow stability. It helps firms manage large data volumes with fewer touchpoints across complex cycles. Faster model updates support operational agility in dynamic environments. IT service firms prefer intelligent bots for scalable process transformation. Users rely on integrated analytics to refine workflows. Higher maturity in AI-linked automation supports expansion across regulated industries.
- For instance, in a December 2020 press release, Automation Anywhere officially reported that it had deployed over 2.6 million bots globally at that time. However, recent 2025 company data shifts focus to metrics such as "1.8M+ Unique AI agent executions" and "400M+ Automations per year," reflecting the evolution of its platform to AI-assisted decision activities across major enterprise environments.
Rising Demand for Cost Reduction, Faster Output, and Better Operational Resilience
Companies use automation to reduce workload across high-volume tasks. Many leaders want systems that ensure consistent output in peak periods. Shared service centers use bots to support finance, HR, and procurement cycles. Automation lowers dependency on manual checks and supports round-the-clock processing. It helps operations teams meet strict SLA goals with fewer delays. Strong economic pressure pushes enterprises to streamline service costs. Buyers use bots to improve customer-facing processes in call centers. The shift strengthens competitive positioning in crowded service markets.
Expansion of Cloud Platforms That Simplify Deployment and Support Scalable Automation
Cloud-led automation helps firms accelerate deployment across multiple departments. It enables flexible scaling without heavy infrastructure investments. Many organizations use cloud models to reduce maintenance efforts and improve update cycles. Vendors offer low-code tools that speed development and shorten automation timelines. Service integrators support hybrid models to meet enterprise security needs. It strengthens adaptation across complex regulated environments. Cloud offers faster provisioning for pilot tests. The India Robotic Process Automation Market benefits from strong enterprise interest in cloud-native automation layers.
Market Trends:
Rise of Industry-Specific Automation Frameworks Tailored for Sector-Level Workflows
Vendors release industry-specific frameworks that target banking, insurance, telecom, and retail. Firms prefer these templates to shorten design time and reduce development errors. The approach supports repeatable results across similar workflows. Automation teams use predefined rule sets for faster rollout. It helps large enterprises meet compliance demands with structured flows. Sector specialists guide firms in refining automation pipelines. Buyers gain a predictable path toward large-scale transformation. The India Robotic Process Automation Market reflects strong interest in sector-focused automation stacks.
- For instance, Blue Prism (SS&C) reports more than 2,000 enterprise customers using sector-specific automation frameworks across BFSI, telecom, and healthcare.
Growing Shift Toward Human-Bot Collaboration to Improve Workforce Productivity
Teams use automation to support human roles rather than replace them. Many enterprises combine bots with employees for better task sequencing. The model improves accuracy in processes that need human judgment. It supports smoother handling of exceptions with fewer delays. Leaders train staff to manage digital labor alongside routine work. Automation centers provide governance rules to maintain discipline. It improves team morale by reducing repetitive work. Human-bot teamwork strengthens operational performance across large service units.
- For instance, Infosys AssistEdge confirms deployment across 400+ global enterprises, supporting human-bot collaboration across service, operations, and contact-center workflows.
Increasing Use of Intelligent Document Processing to Improve Workflow Precision
Firms adopt advanced document processing tools to extract and validate information from varied formats. These tools cut review time for invoices, forms, and compliance files. They improve visibility in high-volume paperwork cycles. IT teams integrate IDP modules with bots for end-to-end automation. Businesses reduce human errors in multi-step tasks. The trend helps operations streamline back-office functions. AI-based classification improves structured and semi-structured data handling. The shift pushes automation deeper into complex departments.
Expansion of Attended and Unattended Automation Models Across Different Work Environments
Organizations deploy attended bots for frontline teams and unattended bots for back-office operations. Both models support different process needs and improve cycle consistency. Attended bots guide employees during customer interactions and help manage query spikes. Unattended bots run scheduled tasks without human input. Many firms combine both styles to build wider automation layers. Vendors provide orchestration tools to manage large bot fleets. It encourages businesses to scale deployments faster. The approach supports flexible automation across hybrid work settings.
Market Challenges Analysis:
High Integration Complexity, Skills Gaps, and Workflow Variability Across Large Enterprises
The India Robotic Process Automation Market faces integration barriers across legacy systems. Many workflows require deep mapping before automation begins. Skills shortages make advanced bot design more difficult for internal teams. Firms struggle when processes vary across departments. IT leaders face pressure to maintain system stability during rollout. It creates delays in scaling automation projects. Vendors must offer stronger governance frameworks to control bot behavior. Firms need clearer process documentation to avoid recurring failures.
Security Risks, Compliance Concerns, and Limited AI Readiness in Regulated Sectors
Many regulated industries hesitate due to strict compliance requirements. Sensitive workflows demand tighter security controls and deeper monitoring. Weak AI readiness slows adoption in processes that need advanced judgment. Firms fear unauthorized bot access if identity controls are weak. Leaders demand secure models that support audit trails. It impacts the pace of automation in finance and public sectors. Integration with secure cloud models needs careful validation. These barriers slow broader adoption across complex institutions.
Market Opportunities:
Expansion of Automation in BFSI, Telecom, Healthcare, and Public Sector Modernization
The India Robotic Process Automation Market benefits from rising interest in automating regulated processes. BFSI players streamline onboarding, KYC, and verification cycles with intelligent bots. Telecom firms automate service management and billing flows. Healthcare units adopt bots for records and claims processing. Public sector agencies modernize citizen services with automated portals. Cloud-led delivery enables fast deployment across government platforms. The opportunity widens as institutions digitize core workflows.
Rising Demand for AI-Enhanced Automation, Low-Code Tools, and Scalable Cloud Platforms
AI-driven bots help enterprises improve decision support and automate complex activities. Low-code platforms lower development barriers for teams with limited technical skills. Cloud-native automation supports fast scaling for high-volume workloads. Vendors expand partner networks that deliver industry-focused automation solutions. It encourages mid-size firms to adopt automation earlier in their digital journey. The opportunity deepens as organizations pursue long-term process modernization.
Market Segmentation Analysis:
By Component
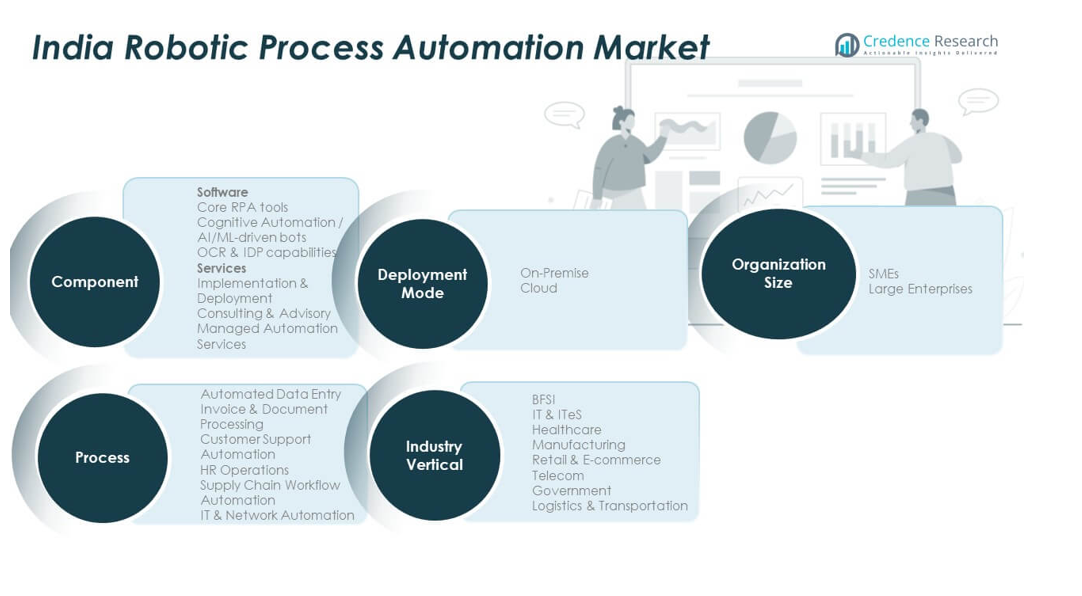
The India Robotic Process Automation Market segments into software and services. Software leads due to strong demand for scalable bots that streamline repetitive workflows. Services gain traction through rising integration, training, and support needs across large enterprises. Many firms rely on service partners to optimize deployments and maintain automation quality. It supports continuous improvement across business functions and helps users upgrade processes with minimal friction.
- For instance, Kofax reports more than 25,000 customers using its automation software suite across document-heavy operations and workflow modernization.
By Deployment
On-premise models stay relevant in regulated industries that require strict data control. Large banks and government units prefer local hosting to maintain compliance standards. Cloud deployment grows faster due to flexible scaling and lower infrastructure costs. Many mid-size firms shift to cloud-based automation platforms for quicker rollout and updates. It drives wider access to intelligent features and supports remote deployment across distributed teams.
- For instance, Pegasystems states that over 70% of its new automation clients adopt cloud-hosted platforms for wider scalability and simplified governance.
By Organization Size
Large enterprises deploy automation across finance, HR, and customer service functions. Their scale supports broad use cases and higher bot volumes. Small and medium enterprises adopt RPA to cut manual workload and improve speed in core tasks. Cloud tools help SMEs reduce deployment complexity and avoid large capital commitments. It increases adoption across fast-growing digital businesses.
By Process
Automated solutions dominate due to strong demand for task-level automation. Decision support and management solutions gain momentum with AI-led workflows. Interaction solutions help customer-facing teams manage queries and routine service activity. It expands automation across both back-office and frontline processes.
By Industry Vertical
BFSI adopts RPA widely for compliance, KYC, and transaction checks. IT and telecom firms use bots to manage service workflows. Healthcare, retail, and manufacturing expand use in documentation, order cycles, and reporting tasks. Energy, utilities, government, and other sectors adopt automation to modernize internal processes and lift operational reliability.
Segmentation:
By Component
- Software
- Services
By Deployment
- On-Premise
- Cloud
By Organization Size
- Large Enterprises
- Small & Medium Enterprises
By Process
- Automated Solution
- Decision Support & Management Solution
- Interaction Solution
By Industry Vertical
- BFSI
- IT & Telecom
- Healthcare
- Retail & E-Commerce
- Manufacturing
- Energy & Utilities
- Government
- Others
Regional Analysis:
South India – Leading Technology Hub with Strong Enterprise Adoption
South India holds the largest share of the India Robotic Process Automation Market at nearly 38%, driven by strong IT clusters and a dense base of technology service providers. Bengaluru, Hyderabad, and Chennai lead due to deep automation expertise and strong cloud adoption. Large IT and BPM firms deploy bots across complex workflows, which fuels advanced use cases. The region benefits from mature digital infrastructure and skilled automation talent. Many global technology firms operate development centers that influence adoption trends. It sets the pace for innovation and expands RPA use across major industries.
West India – Expanding Enterprise Automation Across BFSI and Telecom
West India accounts for about 27% of the market share, supported by strong BFSI, telecom, and shared service activity. Mumbai and Pune lead adoption due to high automation demand in financial services and large enterprise operations. Many banks deploy bots to streamline onboarding, verification, and compliance tasks. Telecom operators use automation to improve service workflows and reduce process backlogs. The region benefits from a strong mix of large enterprises and fast-growing digital companies. It strengthens the role of automation in regulated and high-volume environments.
North, East, and Central India – Growing Demand Through Digital Transformation Across Industries
North India holds close to 22% of the market, led by Delhi NCR with strong adoption in IT services, government units, and large corporates. East and Central India together contribute roughly 13%, supported by rising digital modernization across public sector bodies and mid-size enterprises. Many emerging cities adopt RPA to improve process reliability in healthcare, manufacturing, and retail sectors. Cloud platforms support faster expansion across Tier 2 and Tier 3 cities. Government-led digital programs improve readiness in several administrative departments. It creates new adoption clusters outside major metros.
Key Player Analysis:
- UiPath Inc
- Automation Anywhere
- Blue Prism (SS&C)
- Kofax
- EdgeVerve (AssistEdge)
- Infosys Ltd
- BlackLine Inc
- Nippon Telegraph & Telephone Corp
- Pegasystems Inc
- SAP SE
Competitive Analysis:
The India Robotic Process Automation Market shows strong competition among global vendors and domestic technology providers. Leading players expand footprints through cloud platforms, AI-linked tools, and industry-specific automation frameworks. Vendors focus on partnerships with consulting firms to improve deployment speed across large enterprises. Many firms invest in low-code platforms to help users design workflows with minimal technical effort. Domestic IT service providers strengthen integration support to manage complex automation pipelines. It drives faster adoption in regulated industries and supports expansion across mid-size firms. Competitive intensity stays high due to rapid innovation and ongoing price differentiation in software and services.
Recent Developments:
- In June 2025, UiPath announced a strategic partnership with HCLTech to accelerate agentic automation for global enterprises. The collaboration includes the establishment of an AI Lab in India to develop industry-focused automation solutions and MVPs for clients, covering the full automation lifecycle from strategy to optimization. HCLTech’s global expertise will support UiPath’s expansion, notably benefiting Indian customers.
- In May and July 2025, Pegasystems Inc entered a strategic partnership with Cognizant to advance AI-driven legacy code transformation for Indian enterprises. The alliance integrates Cognizant’s innovation and Pegasystems’ Blueprint to deliver rapid modernization and agentified AI solutions for businesses transforming their legacy systems. Pegasystems also teamed up with SmartBridge Educational Services to launch talent development programs across Indian universities, aiming to quickly build industry-ready skills in low-code, AI, and automation for the next generation of workforce.
- In March 2025, UiPath Inc expanded its R&D footprint in India by acquiring the artificial intelligence-driven inventory management firm Peak. This acquisition brought UiPath into Pune and Jaipur, adding around 100 employees to its India workforce and strengthening its vertical AI solutions strategy. The company is focusing on agentic automation across use cases like invoice processing, claims handling, and medical record summarization. The enhanced presence and specialized talent are expected to support UiPath’s growth in India's automation market.
Report Coverage:
The research report offers an in-depth analysis based on Component, Deployment, Organization Size, Process, and Industry Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise as enterprises expand automation across finance, HR, and service units.
- AI-linked bots will gain traction due to higher accuracy in document-heavy workflows.
- Cloud adoption will increase as firms seek faster deployment and low-maintenance platforms.
- Sector-specific automation frameworks will widen adoption in BFSI, telecom, and healthcare.
- Human–bot collaboration will improve employee productivity in large shared service centers.
- SMEs will scale usage due to simpler, low-code development environments.
- Intelligent orchestration will support complex bot management across hybrid setups.
- RPA vendors will invest in compliance-ready platforms to meet regulated industry needs.
- Regional adoption will deepen across Tier 2 cities as cloud platforms improve accessibility.
- Market competition will intensify through acquisitions and technology partnerships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enterprise-Wide Digital Transformation
Indian enterprises across banking, telecom, and IT are rapidly automating core and support functions to improve accuracy, reduce manual workload, and accelerate process cycles, driving robust RPA adoption.
Cloud-First Automation Strategies
The shift toward cloud deployment enables faster, scalable, and cost-effective automation rollouts, especially for mid-size firms and distributed teams, significantly expanding the addressable market.
AI-Driven Intelligent Automation
Integration of AI with RPA enhances decision support, document processing, and exception handling, making automation more accurate and applicable to complex, data-heavy workflows in regulated sectors.
Cost Reduction and Operational Resilience
Organizations are leveraging RPA to cut operational costs, ensure consistent output during peak periods, and improve service levels, which is especially critical in competitive and high-volume service industries.
Sector-Specific Automation Frameworks
Vendors are offering industry-tailored automation solutions for BFSI, telecom, and healthcare, enabling faster deployment, compliance, and repeatable results, which accelerates adoption in these key verticals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Robotic Process Automation market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Robotic Process Automation market projected to grow between 2025 and 2032?
Which India Robotic Process Automation market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Robotic Process Automation market?
Who are the leading companies in the India Robotic Process Automation market?
Which region commanded the largest share of the India Robotic Process Automation market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Deployment
- 1.3.1 On-Premise
- 1.3.2 Cloud
- 1.4 By Industry Vertical
- 1.4.1 BFSI
- 1.4.2 IT & Telecom
- 1.4.3 Healthcare
- 1.4.4 Retail & E-Commerce
- 1.4.5 Manufacturing
- 1.4.6 Energy & Utilities
- 1.4.7 Government
- 1.4.8 Others
- 1.5 By Organization Size
- 1.5.1 Large Enterprises
- 1.5.2 Small & Medium Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 215.9 million → 2032: USD 4,582.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Robotic Process Automation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Robotic Process Automation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Robotic Process Automation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Robotic Process Automation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Robotic Process Automation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Robotic Process Automation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 India Robotic Process Automation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Robotic Process Automation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 215.9 million → 2032: USD 4,582.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Robotic Process Automation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-Premise
- 12.4.7.2 Cloud
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 BFSI
- 12.5.7.2 IT & Telecom
- 12.5.7.3 Healthcare
- 12.5.7.4 Retail & E-Commerce
- 12.5.7.5 Manufacturing
- 12.5.7.6 Energy & Utilities
- 12.5.7.7 Government
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Large Enterprises
- 12.6.7.2 Small & Medium Enterprises
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Robotic Process Automation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Robotic Process Automation Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Robotic Process Automation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Robotic Process Automation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 UiPath Inc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Automation Anywhere
- 18.4 Blue Prism (SS&C)
- 18.5 Kofax
- 18.6 EdgeVerve (AssistEdge)
- 18.7 Infosys Ltd
- 18.8 BlackLine Inc
- 18.9 Nippon Telegraph & Telephone Corp
- 18.10 Pegasystems Inc
- 18.11 SAP SE
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

