
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sustainable Pharmaceutical Packaging Market Size 2024 | USD 96,005 Million |
| Sustainable Pharmaceutical Packaging Market, CAGR | 15.4% |
| Sustainable Pharmaceutical Packaging Market Size 2032 | USD 301,953.67 Million |
Market Overview:
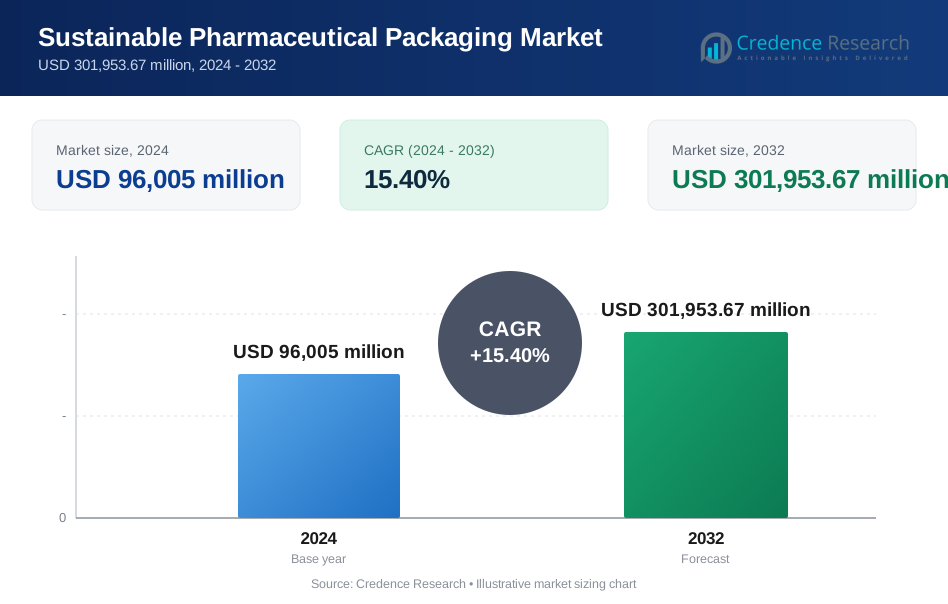
The Sustainable Pharmaceutical Packaging Market size was valued at USD 96,005 million in 2024 and is anticipated to reach USD 301,953.67 million by 2032, at a CAGR of 15.4% during the forecast period (2024-2032).
The growing emphasis on sustainability across industries, particularly in the pharmaceutical sector, is driving this market's growth. Packaging solutions are increasingly being developed to reduce environmental impact while maintaining the high safety standards required for pharmaceutical products. The market is also benefitting from stricter regulations related to sustainability and waste reduction. Several drivers, such as the rising demand for eco-friendly packaging solutions, innovation in materials, and government mandates on environmental sustainability, are propelling the market's growth. The increased adoption of biodegradable, recyclable, and reusable packaging materials plays a significant role in expanding the market. Additionally, technological advancements that enhance the efficiency and sustainability of packaging processes are further driving this market's development.
Regionally, North America dominates the Sustainable Pharmaceutical Packaging Market, with high demand driven by strict environmental regulations and the increasing need for sustainable solutions in the pharmaceutical industry. Europe follows closely, with significant growth in the pharmaceutical and healthcare sectors, which are heavily invested in reducing packaging waste. Meanwhile, the Asia Pacific region is witnessing rapid growth, particularly in emerging markets like India and China, where the demand for pharmaceutical products and sustainable packaging solutions is increasing.
Market Insights:
- The market is projected to grow from USD 96,005 million in 2024 to USD 301,953.67 million by 2032, driven by a global shift toward eco-friendly packaging solutions.
- Increasing regulatory mandates, such as the European Union’s Directive on Packaging and Packaging Waste, are encouraging the adoption of recyclable and bio-based materials.
- Technological advancements in bioplastics and paper-based packaging are enabling manufacturers to meet sustainability goals while maintaining product integrity.
- Rising consumer awareness and demand for environmentally friendly practices in pharmaceutical packaging further drive market growth.
- North America leads the market, driven by stringent FDA guidelines and early adoption of green technologies.
- Asia-Pacific is the fastest-growing region due to expanding pharmaceutical industries and significant investments in sustainable packaging solutions.
- Challenges include high initial costs of sustainable packaging materials and limited infrastructure for recycling in developing regions.
Market Drivers:
Consumer Awareness and Preferences
The rising environmental consciousness among consumers is a major factor driving the demand for sustainable packaging solutions. For instance, nearly 60% of consumers now prioritize sustainability in purchasing decisions, with over half of American consumers willing to pay 5% more for sustainable alternatives over plastic. Additionally, 73% of consumers would switch brands based on packaging sustainability, and 86% of younger consumers are willing to pay extra for eco-friendly products. In response, pharmaceutical companies have increased the use of recycled content in packaging by 40% since 2020, highlighting the shift toward greener solutions.
Regulatory Initiatives
Government regulations and environmental mandates are accelerating the adoption of sustainable pharmaceutical packaging. For instance, the European Union's Circular Economy Action Plan targets 100% reusable or recyclable packaging by 2030, with interim goals of 65% recycling by 2025. Similarly, China’s 2022 state council mandate requires packaging producers to achieve 35% recycled content by 2025 while reducing packaging waste by 20%. As a result, sustainable packaging adoption rates in the pharmaceutical industry have increased by 25% since 2021, emphasizing the impact of regulatory enforcement on industry transformation.
Technological Advancements
Innovations in sustainable materials and packaging technologies are reshaping the pharmaceutical packaging sector. Additionally, robotics and automation have enhanced production efficiency while reducing energy consumption. The development of advanced biodegradable polymers has led to 95% decomposition within 180 days, compared to traditional materials that take over 400 years to degrade, making biodegradable packaging an increasingly viable solution.
Healthcare Infrastructure Growth
The expansion of healthcare facilities and pharmaceutical production, particularly in Asia-Pacific, is driving demand for sustainable packaging solutions. The region’s pharmaceutical production capacity has grown by 35%, with sustainable packaging adoption increasing by 50%. Coupled with an aging population expected to reach 1.5 billion by 2050, the demand for environmentally responsible packaging solutions is expected to rise significantly in the coming years.
Market Trends
Smart Packaging Integration
The pharmaceutical industry is increasingly adopting smart packaging technologies to enhance sustainability and improve patient compliance. Additionally, EU Regulation 2021/2226 mandates QR code placement on pharmaceutical packaging, enabling real-time monitoring of temperature variations within ±0.5°C and humidity levels from 0-100% RH. These advancements have improved inventory management efficiency by 40% and reduced medication errors by 25%, reinforcing the role of digital solutions in optimizing pharmaceutical packaging.
Biodegradable Materials Adoption
The industry is witnessing a major shift toward biodegradable and compostable packaging materials to reduce environmental impact. For instance, companies are leveraging materials derived from seaweed, fungi, and algae, achieving decomposition rates of 90% within 180 days. Furthermore, 3D printing technology has enabled the creation of personalized medicine containers, cutting manufacturing waste by 30% and reducing material consumption by 45%, demonstrating how technological advancements are driving sustainability in pharmaceutical packaging.
Supply Chain Optimization
Pharmaceutical companies are integrating sustainability measures throughout their supply chains to reduce waste and enhance efficiency. For instance, companies have reduced packaging material usage by 40%, implemented renewable energy in manufacturing with 85% efficiency rates, and optimized distribution networks. These initiatives have resulted in a 30% reduction in transportation emissions through route optimization and electric vehicle integration, demonstrating how sustainability initiatives are reshaping the pharmaceutical supply chain.
Market Challenges Analysis
Material Supply and Quality Constraints
The stringent quality requirements for pharmaceutical packaging materials create significant challenges in sourcing sustainable alternatives. The U.S. Food and Drug Administration (FDA) reports that only 10-25% of primary pharmaceutical packaging currently utilizes sustainable materials, with a limited number of suppliers meeting regulatory standards. The European Medicines Agency (EMA) highlights ongoing difficulties in maintaining consistent quality in recycled materials, particularly in ensuring long-term drug stability and preservation. Transitioning to sustainable pharmaceutical packaging incurs substantial costs, impacting manufacturers' operational budgets. For instance, the Environmental Protection Agency (EPA) notes that sustainable materials typically cost 20-30% more than traditional packaging, posing financial challenges for widespread adoption. Additionally, the pharmaceutical industry generates approximately 300 million tonnes of plastic waste annually, with 50% being single-use materials, necessitating large-scale investments in alternative materials and production processes.
Regulatory Compliance Complexity
Navigating evolving environmental regulations adds another layer of complexity to sustainable packaging adoption. Additionally, the FDA’s stringent drug packaging safety and stability guidelines often conflict with sustainability goals, leading to lengthy testing and validation processes before regulatory approval. The complex composition of pharmaceutical packaging materials poses recycling difficulties, hampering efforts to improve sustainability. The World Health Organization (WHO) highlights the challenges of separating plastics, glass, and metals used in multi-material packaging, making effective recycling nearly impossible. To meet the Paris Agreement targets, the pharmaceutical industry must cut emissions by 59% from 2015 levels by 2025, requiring substantial innovation in sustainable packaging solutions while ensuring product integrity and compliance with global safety standards.
Market Opportunities
The Sustainable Pharmaceutical Packaging Market offers immense growth potential as the industry adapts to increasing regulatory pressures and consumer demand for eco-friendly solutions. Governments and regulatory bodies globally are implementing stringent packaging mandates, such as the European Union’s Directive on Packaging and Packaging Waste, to reduce environmental impact, creating a favorable environment for the adoption of sustainable materials. Companies investing in innovative packaging solutions, such as biodegradable polymers, recyclable plastics, and lightweight materials, have significant opportunities to meet evolving industry standards while addressing consumer preferences for sustainability. The push toward carbon neutrality and the circular economy further enhances the demand for green packaging options, enabling manufacturers to differentiate themselves in a competitive market.
Emerging economies, particularly in Asia-Pacific and Latin America, present untapped opportunities due to the rapid expansion of pharmaceutical industries and increasing environmental awareness. These regions are witnessing growing investments in green technologies and infrastructure, providing a lucrative market for sustainable packaging providers. Additionally, advancements in material science and production technologies, such as 3D-printed packaging and bio-based materials, pave the way for cost-effective and scalable solutions. Companies that collaborate with governments, NGOs, and healthcare organizations to promote sustainability and develop localized packaging solutions are well-positioned to capitalize on these opportunities. The rising global focus on environmental conservation and sustainable healthcare practices ensures the long-term growth potential of the sustainable pharmaceutical packaging market.
Market Segmentation Analysis:
By Material
The sustainable pharmaceutical packaging market is segmented based on materials, including biodegradable plastics, paper & paperboard, glass, and metal. Biodegradable plastics are gaining significant traction due to their ability to reduce carbon footprints and meet stringent regulatory guidelines. For instance, pharmaceutical companies are increasingly adopting polylactic acid (PLA) and polyhydroxyalkanoates (PHA) as viable alternatives to conventional plastics, achieving decomposition rates of over 90% within 180 days. Paper & paperboard materials are widely used in secondary and tertiary packaging, offering both recyclability and lightweight benefits. Glass remains a preferred choice for vials and ampoules, ensuring chemical stability and drug preservation, while aluminum and tin-based metal packaging solutions are utilized for their durability and recyclability.
By Product
Sustainable pharmaceutical packaging products include bottles, blister packs, vials, pouches, and cartons. Bottles, particularly those made from recycled PET and glass, are the most widely used due to their versatility in liquid and solid drug formulations. For instance, leading pharmaceutical firms have adopted post-consumer recycled (PCR) materials in bottle production, reducing virgin plastic usage by 50%. Blister packs, essential for unit-dose medications, are evolving toward mono-material designs, improving recyclability without compromising barrier protection. Vials and ampoules made from borosilicate glass continue to dominate injectable drug packaging, while pouches and cartons serve as sustainable alternatives for flexible and bulk packaging applications.
By End User
Key end users of sustainable pharmaceutical packaging include pharmaceutical companies, contract packaging organizations (CPOs), and retail pharmacies. Pharmaceutical manufacturers account for the largest share, as they drive sustainability initiatives to align with global regulations. For instance, multinational pharmaceutical companies have pledged to achieve 100% recyclable or reusable packaging by 2030, emphasizing eco-friendly solutions in drug delivery. Contract packaging organizations (CPOs) play a crucial role in adopting cost-effective sustainable packaging solutions, catering to pharmaceutical firms outsourcing production. Retail pharmacies are increasingly incorporating sustainable packaging, particularly in prescription medication bottles and refillable systems, reducing single-use plastics.
Segmentations:
By Material:
- Plastic and Polymer
- Paper and Paper Board
- Glass
- Aluminium Foil
- Others
By Product:
- Primary
- Secondary
- Tertiary
By End Use:
- Pharma Manufacturing
- Contract Packaging
- Retail Pharmacy
- Institutional Pharmacy
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America dominates the market, accounting for 35% of the global share, driven by stringent regulatory mandates and early adoption of eco-friendly packaging technologies. The FDA’s regulatory emphasis on sustainable practices has accelerated investment in green packaging innovations. In Canada, government initiatives such as the Zero Plastic Waste Initiative aim to reduce packaging waste and promote circular economy principles, further driving market expansion.
Europe
Europe holds 30% of the global market share, supported by the European Union’s Directive on Packaging and Packaging Waste, which targets 100% recyclability in packaging by 2030. France and the UK are also pioneering bioplastics and paper-based solutions to minimize the environmental footprint of pharmaceutical packaging. High consumer demand for eco-friendly packaging and strong government support continue to fuel the region’s growth.
Asia-Pacific
Asia-Pacific is the fastest-growing region, capturing 25% of the global share, driven by expanding pharmaceutical industries and increasing investments in sustainable technologies.. India and Japan are key contributors, with government-backed initiatives such as China’s Green Development Program and India’s National Green Mission creating favorable conditions for sustainable packaging innovations. Additionally, rapid advancements in material science and increasing consumer awareness of eco-friendly products further propel market growth across the region.
Latin America & Middle East & Africa
Latin America and the Middle East & Africa collectively hold the 10% of the global market share, showcasing gradual but promising growth potential. In the Middle East & Africa, Saudi Arabia and South Africa are modernizing healthcare systems and promoting sustainability, with investments in green technologies growing at over 8% annually. These regions are positioned for steady growth as infrastructure development and environmental awareness continue to advance.
Key Player Analysis:
- Amcor plc
- Berry Global Group, Inc.
- Gerresheimer AG
- Schott AG
- West Pharmaceutical Services, Inc.
- AptarGroup, Inc.
- CCL Industries Inc.
- WestRock Company
- Origin Pharma Packaging
- Becton Dickinson & Company
Competitive Analysis:
The Sustainable Pharmaceutical Packaging Market is highly competitive, driven by regulatory pressures, increasing environmental awareness, and rising demand for eco-friendly packaging solutions. Major players such as Amcor plc, Berry Global Group, Inc., and Gerresheimer AG lead the market, leveraging innovative packaging technologies like recyclable plastics, bioplastics, and lightweight materials. Emerging players like Origin Pharma Packaging are gaining market traction by offering cost-effective, sustainable packaging solutions tailored to smaller pharmaceutical firms, making green alternatives more accessible across the industry. Additionally, strategic collaborations are shaping the market, such as Schott AG’s 2024 partnership with healthcare providers to introduce glass vials composed of 50% recycled materials, significantly cutting environmental impact. Increasing R&D investments, with pharmaceutical packaging companies collectively allocating over $2 billion annually toward sustainable innovations, alongside government incentives promoting eco-friendly practices, continue to drive the market forward.
Recent Developments:
- In May 2023, Aptar Pharma launched the Futurity™ solutions platform, representing their sustainable solutions across all product lines. This initiative helps customers identify Aptar Pharma products, technologies, and services that enhance sustainability and circularity objectives.
- In October 2023, at the CPHI conference, Gerresheimer emphasized its focus on high-value solutions and sustainability, showcasing innovative vial and packaging solutions designed to minimize risks in the filling process and reduce carbon footprints for pharmaceutical companies.
- In April 2022, Amcor expanded its pharmaceutical packaging portfolio by introducing new, more sustainable High Shield laminates. These low-carbon, recycle-ready packaging options provide the high barrier and performance requirements needed for the industry while supporting pharmaceutical companies’ recyclability agendas.
Market Concentration & Characteristics:
The Sustainable Pharmaceutical Packaging Market is moderately concentrated, with a mix of established global players and innovative regional companies driving its growth. Key players such as Amcor plc, Berry Global Group, Inc., and Gerresheimer AG lead the market by leveraging advanced technologies and sustainable materials like recyclable plastics, bioplastics, and lightweight solutions. These companies invest heavily in R&D, collectively allocating over $2 billion annually to innovate eco-friendly packaging options. Emerging firms like Origin Pharma Packaging are gaining market share by offering cost-effective, sustainable packaging tailored to smaller pharmaceutical manufacturers. The market is further characterized by collaborations, such as Schott AG’s partnership with healthcare providers in 2024 to develop vials with up to 50% recycled content, enhancing environmental compliance. Increasing regulatory pressures, technological advancements, and consumer demand for sustainability are reshaping the market dynamics, driving innovation and adoption of green packaging solutions globally.
Report Coverage:
The research report offers an in-depth analysis based on material, product, end use, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing regulatory mandates will drive the adoption of sustainable pharmaceutical packaging solutions, particularly in developed regions like North America and Europe.
- Advancements in material science will enable the development of innovative packaging options, such as bioplastics, compostable materials, and lightweight designs.
- Rising demand for recyclable and reusable packaging will accelerate the shift toward a circular economy in the pharmaceutical sector.
- Pharmaceutical companies’ sustainability goals will encourage investments in eco-friendly packaging technologies and green manufacturing practices.
- Emerging markets, particularly in Asia-Pacific and Latin America, will provide significant growth opportunities due to expanding healthcare infrastructure and rising environmental awareness.
- Strategic collaborations between packaging manufacturers and pharmaceutical companies will lead to the co-development of customized, sustainable solutions.
- Intelligent and active packaging technologies, integrating smart sensors and environmental monitoring, will gain traction as sustainability and efficiency priorities converge.
- Consumer awareness and preference for environmentally friendly pharmaceutical products will further push companies to adopt sustainable packaging practices.
- Technological advancements in production processes, such as 3D printing and automation, will lower costs and make sustainable packaging more accessible to small and mid-sized pharmaceutical companies.
- Supportive government policies, incentives, and funding for sustainability initiatives will continue to fuel innovation and adoption of sustainable pharmaceutical packaging globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Sustainable Pharmaceutical Packaging Market?
What factors are driving the growth of the Sustainable Pharmaceutical Packaging Market?
What are some challenges faced by the Sustainable Pharmaceutical Packaging Market?
Who are the major players in the Sustainable Pharmaceutical Packaging Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Sustainable Pharmaceutical Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Sustainable Pharmaceutical Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 96,005 million → 2032: USD 301,953.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Sustainable Pharmaceutical Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Sustainable Pharmaceutical Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Sustainable Pharmaceutical Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Sustainable Pharmaceutical Packaging Market Drivers
- 3.3 Sustainable Pharmaceutical Packaging Market Restraints & Challenges
- 3.4 Sustainable Pharmaceutical Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Sustainable Pharmaceutical Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Sustainable Pharmaceutical Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Sustainable Pharmaceutical Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Sustainable Pharmaceutical Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Sustainable Pharmaceutical Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Sustainable Pharmaceutical Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Sustainable Pharmaceutical Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Sustainable Pharmaceutical Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Sustainable Pharmaceutical Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Sustainable Pharmaceutical Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Sustainable Pharmaceutical Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Sustainable Pharmaceutical Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Sustainable Pharmaceutical Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Sustainable Pharmaceutical Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Sustainable Pharmaceutical Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Sustainable Pharmaceutical Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Sustainable Pharmaceutical Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Sustainable Pharmaceutical Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Sustainable Pharmaceutical Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
