
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Titanium Metal (Titanium Alloy) Market Size 2024 | USD 5,050 Million |
| Titanium Metal (Titanium Alloy) Market, CAGR | 5.2% |
| Titanium Metal (Titanium Alloy) Market Size 2032 | USD 7,576 Million |
Market Overview:
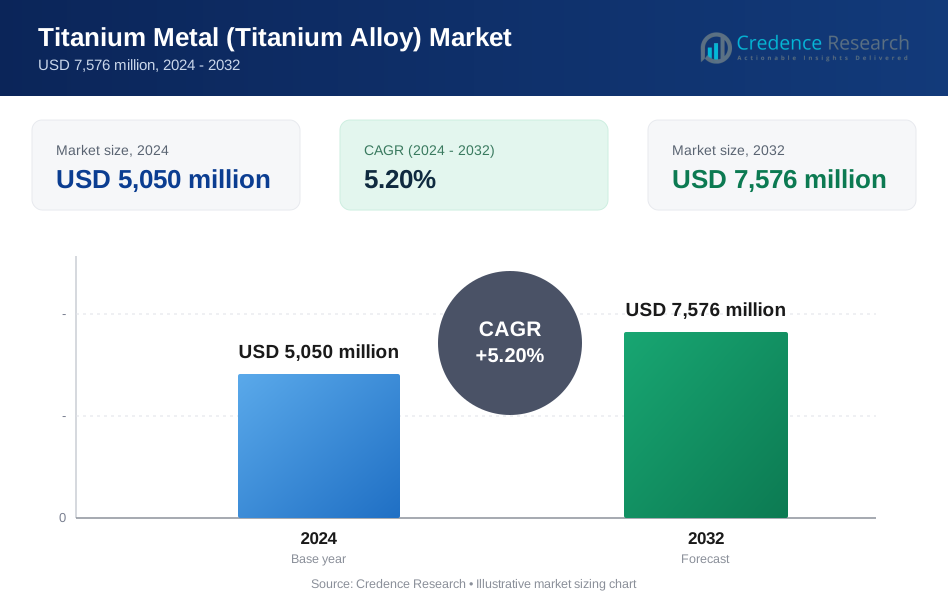
Titanium Metal (Titanium Alloy) Market size was valued at USD 5,050 million in 2024 and is anticipated to reach USD 7,576 million by 2032, at a CAGR of 5.2% during the forecast period (2024-2032).
Key market drivers include increasing aircraft production, growing space exploration initiatives, and rising demand for titanium-based implants in the medical sector. In the aerospace and defense industry, titanium alloys are extensively used in airframes, engine components, and structural parts due to their ability to withstand extreme operating conditions while reducing overall weight. The automotive sector also contributes to demand growth, with manufacturers adopting titanium to improve fuel efficiency and vehicle performance. Furthermore, the medical industry sees rising adoption of titanium for orthopedic implants, dental applications, and surgical instruments due to its biocompatibility and durability. Continued investments in 3D printing technologies are also enhancing the precision manufacturing of complex titanium components across industries. Strong R&D pipelines and collaborations between material scientists and OEMs further accelerate product innovation. Governments and regulatory bodies are also encouraging advanced materials use in high-growth sectors through funding and policy support.
Regionally, North America holds the largest share of the Titanium Metal (Titanium Alloy) Market, driven by strong aerospace, defense, and healthcare infrastructure in the United States. Europe follows closely, with increasing demand for sustainable materials and technological advancements in manufacturing. The Asia-Pacific region is witnessing the fastest growth, supported by expanding aerospace production, industrial development, and rising healthcare investments in China, India, and Japan. Government-backed initiatives promoting domestic manufacturing and raw material self-reliance also support regional growth. Latin America and the Middle East & Africa show growing potential, especially in energy and infrastructure sectors, further diversifying the market landscape. Expanding export opportunities and foreign direct investments are likely to strengthen the global supply chain footprint in these emerging markets.
Market Insights:
- The Titanium Metal (Titanium Alloy) Market reached USD 5,050 million in 2024 and is projected to grow to USD 7,576 million by 2032, driven by rising demand across aerospace, medical, and industrial sectors.
- Titanium alloys are widely used in the aerospace and defense sectors for airframes, engine components, and structural parts due to their strength, heat resistance, and lightweight properties.
- The medical industry continues to adopt titanium in orthopedic implants, dental fixtures, and surgical instruments because of its biocompatibility, corrosion resistance, and MRI compatibility.
- The automotive and industrial sectors are increasingly using titanium alloys to reduce vehicle weight, improve fuel efficiency, and enhance corrosion resistance in harsh environments.
- Technological advancements in additive manufacturing and 3D printing are enabling the production of complex titanium parts with greater design flexibility and reduced material waste.
- High production costs, complex processing methods, and limited raw material sources pose challenges to market growth and restrict titanium’s use in cost-sensitive applications.
- North America accounts for 35% of the market, followed by Europe at 27% and Asia-Pacific at 22%, with Asia-Pacific showing the fastest growth due to expanding manufacturing capabilities and rising healthcare investments.
Market Drivers:
Growing Demand from Aerospace and Defense Applications
Titanium alloys continue to play a critical role in aerospace and defense applications due to their superior strength-to-weight ratio and corrosion resistance. The Titanium Metal (Titanium Alloy) Market benefits significantly from rising aircraft production and defense modernization programs across developed and emerging economies. It supports the manufacturing of airframes, jet engines, and structural components that require high durability under extreme conditions. Titanium's thermal stability and fatigue resistance make it a preferred material for military aircraft and space exploration missions. Increasing defense budgets and growing interest in hypersonic and next-generation aircraft platforms are expanding the demand base. OEMs and suppliers are also investing in titanium machining and forming technologies to improve cost efficiency and throughput.
Expanding Use in Medical Implants and Devices
Titanium alloys are widely adopted in the medical sector due to their excellent biocompatibility and corrosion resistance. The Titanium Metal (Titanium Alloy) Market sees rising consumption in orthopedic implants, dental fixtures, and surgical instruments. It meets stringent safety and performance standards required for long-term use in the human body. Growing incidence of bone-related disorders, coupled with aging populations in North America, Europe, and Asia-Pacific, fuels the demand for titanium-based medical solutions. The metal’s non-toxic nature and compatibility with MRI imaging enhance its appeal for healthcare applications. Increasing investments in healthcare infrastructure and innovation in medical device design support continued adoption.
- For instance, Stryker Corporation has integrated titanium alloys into its orthopedic implant portfolio, enhancing durability and patient outcomes.
Adoption in Automotive and Industrial Sectors for Lightweighting
Automotive manufacturers are integrating titanium alloys into vehicle components to reduce weight and boost performance. The Titanium Metal (Titanium Alloy) Market gains traction in high-performance and electric vehicles where fuel efficiency and range optimization are priorities. It offers high strength with minimal weight, helping meet strict emission standards and sustainability targets. Industrial sectors also utilize titanium in chemical processing, marine equipment, and power generation due to its resistance to corrosive environments. Expanding focus on operational efficiency and lifecycle cost reduction drives adoption in harsh industrial applications. Manufacturers are scaling up supply chains to meet growing OEM requirements.
- For instance, Tesla has incorporated titanium alloy components in its electric vehicle chassis to improve structural integrity and reduce weight.
Technological Advancements and 3D Printing Innovations
Ongoing technological innovation enhances the usability and processing efficiency of titanium alloys. The Titanium Metal (Titanium Alloy) Market benefits from the rapid development of additive manufacturing techniques that allow the production of complex, lightweight parts with minimal waste. It enables design flexibility and customization, especially valuable in aerospace and medical sectors. Advances in powder metallurgy, alloy composition, and surface treatment improve material properties and production consistency. Manufacturers are leveraging digital tools and automation to reduce production costs and increase scalability. Research partnerships and government support for advanced manufacturing foster a favorable environment for innovation in titanium processing.
Market Trends:
Rising Integration of Additive Manufacturing and Advanced Fabrication Techniques
The Titanium Metal (Titanium Alloy) Market is witnessing a significant shift with the growing adoption of additive manufacturing and advanced fabrication technologies. It enables the production of lightweight, complex, and customized components with reduced material waste and shorter lead times. Industries such as aerospace, healthcare, and automotive are increasingly leveraging 3D printing for precision engineering using titanium powders. The trend supports mass customization, rapid prototyping, and cost-effective production of intricate parts. Technological advancements in laser sintering, electron beam melting, and powder metallurgy continue to improve the structural integrity and quality of titanium components. Manufacturers are also developing hybrid systems that combine traditional and additive methods to optimize productivity and performance.
- For instance, Lockheed Martin Space Systems has utilized titanium 3D printing to manufacture aerospace structural parts and airframe components, demonstrating the benefits of additive manufacturing for complex, high-performance applications.
Increased Emphasis on Sustainable Sourcing and Circular Manufacturing
Sustainability trends are reshaping the Titanium Metal (Titanium Alloy) Market, with an emphasis on responsible sourcing and recycling. It aligns with global efforts to reduce carbon emissions and promote circular manufacturing practices. Titanium producers are investing in energy-efficient processes and low-emission extraction technologies to minimize environmental impact. The market is experiencing a growing preference for recycled titanium scrap, which retains its mechanical properties and reduces raw material dependency. End-use industries seek eco-friendly supply chains that meet evolving regulatory standards and ESG goals. Strategic collaborations across the value chain are accelerating the development of closed-loop systems and sustainable production models.
- For instance, IperionX Ltd. and Aperam Recycling have partnered to establish a fully circular, 100 percent recycled titanium supply chain in the United States, converting titanium scrap into high-performance products for advanced manufacturing sectors.
Market Challenges Analysis:
High Production Costs and Complex Processing Requirements
The Titanium Metal (Titanium Alloy) Market faces persistent challenges due to high production costs and complex extraction and refining processes. It requires energy-intensive methods such as the Kroll process, which involves multiple stages and generates significant waste. These complexities increase the final product cost, limiting titanium’s competitiveness against alternative materials in cost-sensitive applications. The market struggles with balancing quality, efficiency, and affordability, particularly for mass-market adoption. Equipment and expertise needed for titanium alloy processing are also capital-intensive, creating barriers for new entrants. This cost structure narrows titanium’s use to premium sectors such as aerospace and medical, restricting wider commercial deployment.
- For instance, Hyperion Metals Limited, in partnership with Blacksand Technology, is advancing the commercial development of titanium metal powders using innovative processes such as the Hydrogen Assisted Metallothermic Reduction (HAMR) and Granulation-Sintering-Deoxygenation (GSD) technologies.
Limited Raw Material Availability and Supply Chain Constraints The Titanium Metal (Titanium Alloy) Market remains vulnerable to raw material shortages and geopolitical disruptions. It relies heavily on a limited number of countries for the mining and supply of titanium ore, such as rutile and ilmenite. Supply chain instability and export restrictions can impact global availability and price stability. Long procurement cycles and dependency on few suppliers affect timely delivery for critical applications. It must also address issues related to recycling infrastructure, which remains underdeveloped in many regions. These factors challenge the market’s ability to scale and meet rising demand across diverse industries.
Market Opportunities:
Expansion of Applications in Emerging Industries and Infrastructure
The Titanium Metal (Titanium Alloy) Market holds strong potential in emerging industries such as renewable energy, marine engineering, and industrial infrastructure. It offers corrosion resistance and strength under extreme conditions, making it suitable for offshore wind components, desalination systems, and chemical processing equipment. Demand is increasing in regions investing in clean energy projects and long-term infrastructure upgrades. The metal’s performance benefits position it as a viable material for reducing maintenance costs and extending asset life in challenging environments. Governments promoting industrial modernization and sustainability targets create favorable conditions for titanium adoption. Companies exploring new applications in industrial sectors can tap into untapped growth segments.
Growth in Developing Markets and Localized Manufacturing
Rising demand from developing economies presents a major growth opportunity for the Titanium Metal (Titanium Alloy) Market. It is gaining traction in countries such as India, Brazil, and Southeast Asian nations, where aerospace, automotive, and healthcare sectors are expanding. Growing focus on domestic manufacturing and raw material security supports investments in titanium production and processing facilities. The trend toward localized supply chains opens avenues for regional players to participate in high-value titanium alloy production. Market participants can capitalize on government-led initiatives to reduce import dependence and boost technological capabilities. Creating affordable and scalable processing solutions will further unlock access to these high-growth markets.
Market Segmentation Analysis:
By Type
The Titanium Metal (Titanium Alloy) Market is segmented into commercially pure titanium and titanium alloys. Titanium alloys lead the segment due to their superior mechanical strength, corrosion resistance, and ability to withstand high temperatures. These characteristics make them ideal for use in aerospace, medical, and automotive components where performance is critical. Commercially pure titanium finds use in applications prioritizing corrosion resistance over strength, such as chemical processing and marine environments. Ongoing material research continues to improve the properties of both categories, broadening their application scope. It reflects a clear shift toward performance-driven materials across industrial applications.
By Application
By application, the Titanium Metal (Titanium Alloy) Market is categorized into aerospace, medical, automotive, industrial, and others. The aerospace sector holds the largest share due to the extensive use of titanium alloys in aircraft structures, engine components, and space systems. The medical segment is expanding with increasing use of titanium in implants, surgical instruments, and dental applications, supported by its biocompatibility and durability. Automotive applications are growing steadily as manufacturers seek lightweight materials to enhance efficiency and meet emissions regulations. The industrial segment includes use in chemical processing, power generation, and marine sectors where corrosion resistance is essential. Each segment benefits from titanium's unique combination of strength, weight, and resistance properties.
Segmentations:
By Type
- Commercially Pure Titanium
- Titanium Alloys
By Application
- Aerospace
- Medical
- Automotive
- Industrial
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Strong Aerospace and Medical Demand
North America holds 35% of the Titanium Metal (Titanium Alloy) Market, making it the largest regional segment. The United States drives this dominance through robust demand from aerospace, defense, and medical industries. Leading aircraft manufacturers and space exploration programs rely heavily on titanium alloys for structural and high-temperature components. The region also benefits from a mature healthcare sector that uses titanium in implants, prosthetics, and surgical instruments. Investment in additive manufacturing and advanced material research strengthens North America's titanium capabilities. Strong industrial infrastructure and a high concentration of key market players further support regional growth.
Europe Benefits from Sustainability and Engineering Expertise
Europe accounts for 27% of the Titanium Metal (Titanium Alloy) Market, positioning it as a major contributor to global demand. Countries such as Germany, France, and the United Kingdom prioritize lightweight and recyclable materials in sectors like aerospace, automotive, and energy. Titanium's corrosion resistance and mechanical strength make it a key material in the region’s push for sustainable innovation. Europe benefits from advanced engineering talent and state-of-the-art fabrication technologies. Environmental regulations continue to encourage the use of titanium in emission-reducing and long-life applications. Regional support for material recycling and green manufacturing enhances long-term competitiveness.
Asia-Pacific Emerges as the Fastest-Growing Market
Asia-Pacific captures 22% of the Titanium Metal (Titanium Alloy) Market and shows strong growth momentum across industrial sectors. China, Japan, and India lead regional consumption through increased activity in aerospace manufacturing, healthcare expansion, and infrastructure upgrades. Governments promote domestic production and reduce import dependence through strategic industrial policies and public investment. The region’s cost advantages and raw material availability improve its role in global supply chains. Medical applications of titanium also see rapid growth due to higher surgical procedure volumes and healthcare modernization. Ongoing advancements in local manufacturing capabilities support further expansion in titanium alloy usage.
Key Player Analysis:
- Advanced Metallurgical Group
- Arconic
- ATI
- OSAKA Titanium Technologies Co.,Ltd.
- TIMET
- BAOTAI
- Carpenter
- Western Metal Materials
- Western Superconducting
- Toho Titanium
- VSMPO-AVISMA
Competitive Analysis:
The Titanium Metal (Titanium Alloy) Market is highly competitive, with key players focusing on technological innovation, capacity expansion, and strategic partnerships to strengthen their market position. Major companies include VSMPO-AVISMA Corporation, ATI Inc., Nippon Steel Corporation, Western Superconducting Technologies Co. Ltd., and Toho Titanium Co., Ltd. These players invest in advanced manufacturing techniques such as additive manufacturing and powder metallurgy to meet the growing demand for precision components. It faces competition from substitute materials in cost-sensitive applications, prompting continuous improvements in production efficiency and material performance. Leading firms emphasize vertical integration and global distribution networks to ensure consistent supply and maintain quality standards. Market participants also collaborate with aerospace, medical, and industrial OEMs to develop application-specific titanium solutions. Competitive differentiation depends on alloy quality, customization capabilities, and the ability to meet stringent regulatory requirements across industries.
Recent Developments:
- In December 2022, AMG Advanced Metallurgical Group N.V. announced a strategic partnership with Nippon Mining & Metals Corporation focused on the tantalum business.
- In May 2024, Osaka Titanium announced a ¥30 billion ($191 million) investment to expand titanium sponge production at its Amagasaki plant, increasing annual capacity from 40,000 to 50,000 tons.
Market Concentration & Characteristics:
The Titanium Metal (Titanium Alloy) Market exhibits moderate to high market concentration, dominated by a few global players with integrated operations and strong technological capabilities. It is characterized by high entry barriers due to capital-intensive processes, complex refining methods, and strict quality standards. Leading companies control a significant share of the supply chain, from raw material extraction to finished product manufacturing. The market favors suppliers with advanced metallurgical expertise, robust R&D infrastructure, and long-term contracts with aerospace, medical, and industrial clients. It is driven by performance-critical applications that demand consistency, precision, and compliance with regulatory specifications. Competitive advantage depends on innovation, reliability, and supply security. Pricing volatility of titanium ore and geopolitical dependence on key producing nations also influence procurement strategies and investment planning. Demand for recycled titanium and closed-loop manufacturing systems is gradually shaping future market dynamics.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The aerospace sector will continue to be a primary driver, with titanium alloys essential for lightweight, high-strength components in aircraft and spacecraft.
- Medical applications are set to expand, leveraging titanium's biocompatibility for implants, prosthetics, and surgical instruments.
- Automotive industries will increasingly adopt titanium alloys to enhance fuel efficiency and performance in high-end and electric vehicles.
- Additive manufacturing advancements will facilitate the production of complex titanium components, reducing waste and production time.
- Industrial sectors, including chemical processing and marine engineering, will grow their use of titanium for its corrosion resistance and durability.
- Emerging economies in Asia-Pacific and Latin America will boost demand through infrastructure development and industrialization.
- Recycling initiatives will gain momentum, addressing raw material scarcity and promoting sustainable practices in titanium usage.
- Technological innovations will lead to the development of new titanium alloys with enhanced properties for specialized applications.
- Strategic partnerships and collaborations among key industry players will drive research and development efforts.
- Government policies and investments will support the growth of titanium applications across various sectors, reinforcing its market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand from Aerospace and Defense Applications
Titanium alloys are essential in aerospace and defense due to their high strength-to-weight ratio, corrosion resistance, and ability to withstand extreme conditions. Rising aircraft production, defense modernization, and space exploration initiatives are significantly increasing titanium alloy consumption for airframes, engines, and structural parts.
Expanding Use in Medical Implants and Devices
The medical sector is increasingly adopting titanium for orthopedic implants, dental fixtures, and surgical instruments because of its biocompatibility, corrosion resistance, and compatibility with MRI imaging. Aging populations and higher rates of bone-related disorders are driving demand for titanium-based medical solutions.
Adoption in Automotive and Industrial Sectors for Lightweighting
Automotive manufacturers are integrating titanium alloys to reduce vehicle weight and improve fuel efficiency, especially in high-performance and electric vehicles. Industrial sectors use titanium for its corrosion resistance and durability in harsh environments, supporting operational efficiency and lifecycle cost reduction.
Technological Advancements and 3D Printing Innovations
Advances in additive manufacturing and 3D printing are enabling the production of complex, lightweight titanium components with reduced material waste and greater design flexibility. These innovations are expanding titanium's applications in aerospace, medical, and industrial sectors while improving cost efficiency.
Sustainability and Circular Manufacturing Initiatives
There is a growing emphasis on sustainable sourcing and recycling of titanium, with investments in energy-efficient processes and closed-loop manufacturing systems. The use of recycled titanium scrap is increasing, helping to reduce raw material dependency and align with global ESG and regulatory standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the expected growth of the Titanium Metal (Titanium Alloy) Market?
What industries are driving demand for titanium metal and alloys?
Why is titanium popular in aerospace and defense?
How is titanium used in the medical sector?
Which region leads the titanium metal market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Commercially Pure Titanium
- 1.2.2 Titanium Alloys
- 1.3 By Application
- 1.3.1 Aerospace
- 1.3.2 Medical
- 1.3.3 Automotive
- 1.3.4 Industrial
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,050 million → 2032: USD 7,576 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Titanium Metal (Titanium Alloy) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Titanium Metal (Titanium Alloy) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Titanium Metal (Titanium Alloy) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Titanium Metal (Titanium Alloy) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Titanium Metal (Titanium Alloy) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Titanium Metal (Titanium Alloy) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Titanium Metal (Titanium Alloy) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Titanium Metal (Titanium Alloy) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,050 million → 2032: USD 7,576 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Titanium Metal (Titanium Alloy) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercially Pure Titanium
- 12.3.7.2 Titanium Alloys
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Aerospace
- 12.4.7.2 Medical
- 12.4.7.3 Automotive
- 12.4.7.4 Industrial
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Titanium Metal (Titanium Alloy) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Titanium Metal (Titanium Alloy) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Titanium Metal (Titanium Alloy) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Titanium Metal (Titanium Alloy) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 VSMPO-AVISMA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ATI Inc.
- 18.4 Toho Titanium Co., Ltd.
- 18.5 OSAKA Titanium Technologies Co., Ltd.
- 18.6 TIMET
- 18.7 Advanced Metallurgical Group (AMG)
- 18.8 Western Superconducting Technologies Co. Ltd.
- 18.9 Arconic
- 18.10 BAOTAI
- 18.11 Carpenter Technology Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

