
Market Overview:
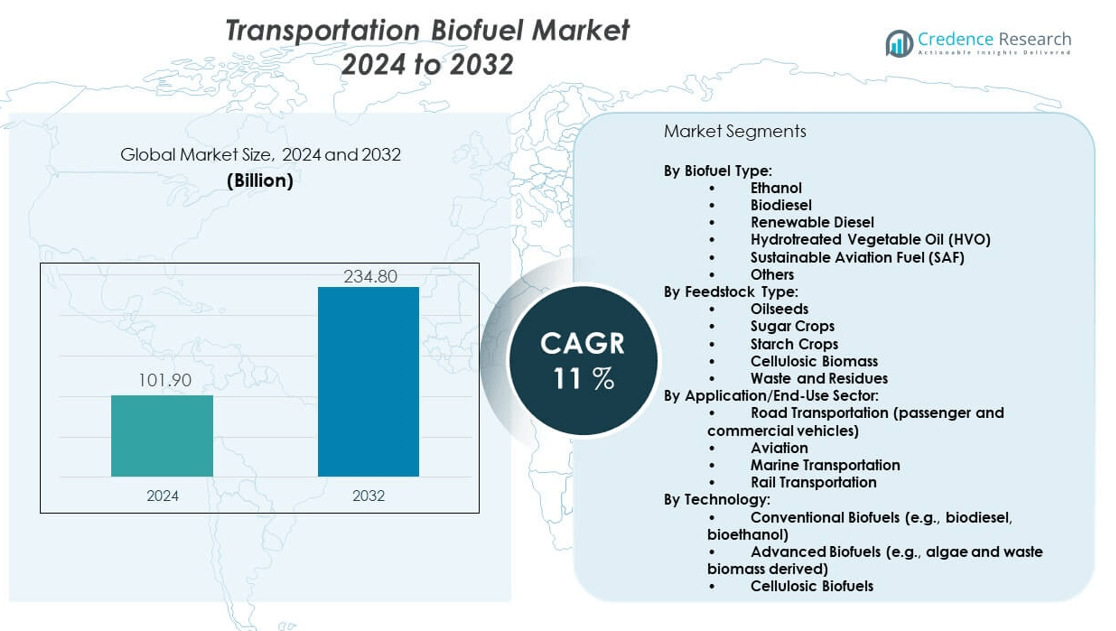
The transportation biofuel market is projected to grow from USD 101.9 billion in 2024 to an estimated USD 234.8 billion by 2032, with a compound annual growth rate (CAGR) of 11% from 2024 to 2032. Growing emphasis on decarbonizing the transportation sector, supportive government mandates, and rising adoption of renewable energy in fuel blends are key factors driving market expansion. Increasing investments in advanced biofuel technologies, such as cellulosic ethanol and biodiesel, are expected to strengthen the role of biofuels in reducing carbon intensity across multiple transportation modes.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Transportation Biofuel Market Size 2024 | USD 101.9 billion |
| Transportation Biofuel Market, CAGR | 11% |
| Transportation Biofuel Market Size 2032 | USD 234.8 billion |
The transportation biofuel market benefits from rising fuel demand, stricter emission reduction targets, and growing energy security concerns. It is supported by policies that promote renewable fuel usage and incentivize low-carbon alternatives to fossil fuels. Market growth is also shaped by the aviation and maritime sectors, where biofuels are increasingly adopted to comply with emission norms. Advancements in feedstock flexibility, efficiency of bio-refineries, and integration of waste-to-fuel technologies enhance competitiveness, positioning biofuels as a scalable and sustainable solution for the transportation industry.
Regional Analysis, The transportation biofuel market shows strong momentum across North America and Europe, where established regulatory frameworks, blending mandates, and technology investments sustain high adoption. The United States and Brazil lead in production due to large-scale ethanol and biodiesel programs, while the European Union strengthens demand through renewable energy directives. Asia-Pacific emerges as the fastest-growing region, with China and India investing heavily in biofuel infrastructure to address energy security and environmental concerns. Latin America demonstrates significant potential, driven by abundant feedstock availability, while African markets remain at a nascent stage but present future growth opportunities with expanding agricultural resources.
Market Insights:
- The transportation biofuel market was valued at USD 101.9 billion in 2024 and is projected to reach USD 234.8 billion by 2032, growing at a CAGR of 11% during the forecast period.
- Strong government regulations, blending mandates, and subsidies drive adoption by creating steady demand and encouraging large-scale investments in biofuel production.
- Rising environmental concerns and the need to reduce dependence on fossil fuels accelerate demand across road, aviation, and maritime transport sectors.
- High production costs and fluctuating feedstock availability remain key restraints, creating challenges for small producers and limiting scalability in certain regions.
- Limited consumer awareness and inconsistent policy support in developing economies hinder smooth adoption of biofuels.
- North America and Europe dominate the market due to established infrastructure, advanced technologies, and strong policy frameworks.
- Asia-Pacific emerges as the fastest-growing region, supported by expanding vehicle fleets, rising energy security needs, and government-backed renewable fuel initiatives.
Market Drivers:
Government Regulations and Policy Support as a Growth Catalyst:
The transportation biofuel market gains momentum from strong regulatory frameworks and policy initiatives that encourage renewable fuel adoption. Governments worldwide enforce blending mandates that require a certain percentage of biofuels in conventional fuels. These mandates create predictable demand and stimulate investments in advanced production facilities. Tax incentives, subsidies, and research funding enhance the competitiveness of biofuels compared to fossil fuels. The aviation and maritime sectors benefit from regulatory pressure to cut emissions, creating new demand. Strict carbon reduction commitments by countries further expand biofuel adoption. It gains traction because policy-driven support lowers the risks for producers and distributors.
Rising Demand for Cleaner Energy Across Transportation Sectors:
The transportation biofuel market experiences growth as consumers and industries demand cleaner energy alternatives. Urbanization and rising vehicle ownership increase fuel consumption, placing pressure on conventional energy resources. Biofuels provide a renewable and low-carbon option that aligns with global sustainability goals. Airlines and shipping companies are turning to biofuels to comply with emission standards. Public transportation agencies adopt biodiesel and ethanol blends to reduce urban pollution levels. Energy security also drives adoption, as biofuels can be produced domestically from diverse feedstocks. It benefits from the alignment of environmental priorities with economic interests. Global initiatives against climate change reinforce this demand shift.
- For instance, Archer Daniels Midland Company (ADM) announced plans in 2022 to convert more than half of its ethanol production capacity to sustainable aviation fuel, partnering with Gevo to target 500 million gallons annually by 2026, demonstrating industry response to rising clean energy demands.
Technological Advancements in Feedstock Utilization and Refining:
The transportation biofuel market advances with continuous improvements in feedstock flexibility and refining technologies. Producers now convert agricultural residues, municipal waste, and algae into biofuels, reducing reliance on food-based crops. These innovations lower the food-versus-fuel conflict and improve sustainability. Second-generation and third-generation biofuels offer higher yields and lower environmental footprints. Refining technologies improve energy efficiency, enabling cost-effective production at scale. Integration of digital monitoring systems in bio-refineries enhances output quality and reduces operational risks. The ability to diversify feedstocks ensures resilience against supply disruptions. It strengthens long-term competitiveness by addressing environmental and economic concerns simultaneously.
Strategic Investments and Private Sector Participation:
The transportation biofuel market receives a boost from strategic investments by energy firms and private players. Large oil and gas companies diversify into renewable fuels to meet sustainability targets. Joint ventures between biofuel producers and automotive firms accelerate adoption in vehicle fleets. Venture capital investment supports startups developing advanced conversion technologies. Infrastructure expansion, such as blending facilities and distribution networks, ensures wider accessibility. Collaboration with agricultural sectors secures feedstock supply at stable prices. Increasing corporate commitments to carbon neutrality push industries to adopt biofuels aggressively. It benefits when capital flows into scalable projects that ensure global reach and efficiency.
Market Trends:
Integration of Biofuels into Aviation and Maritime Sectors:
The transportation biofuel market witnesses rising integration into aviation and shipping industries. Airlines adopt sustainable aviation fuels (SAFs) to meet emission reduction goals set by international bodies. Shipping companies explore marine biofuels as alternatives to heavy fuel oil. These sectors create premium demand that supports advanced biofuel technologies. Pilot projects and commercial-scale trials expand, proving feasibility. Partnerships between airlines, ports, and fuel producers strengthen the value chain. International organizations push for decarbonization, making biofuels a critical part of compliance strategies. It expands as new industries beyond road transport rely on renewable alternatives to reduce carbon footprints.
- For instance, Louis Dreyfus Company successfully completed a B30 biofuel blend trial on a transatlantic shipment in 2022, achieving a 24% reduction in greenhouse gas emissions, illustrating biofuel integration in maritime transport.
Rising Focus on Circular Economy and Waste-to-Fuel Models:
The transportation biofuel market follows a trend toward circular economy principles through waste-to-fuel initiatives. Companies leverage agricultural residues, municipal waste, and used cooking oil to create sustainable fuels. These pathways reduce waste management challenges while providing renewable energy. Urban regions adopt waste-to-fuel plants to balance energy needs with sustainability commitments. Scaling waste-to-fuel improves environmental credibility by reducing landfill usage. Governments encourage adoption with policies that prioritize waste valorization. It strengthens resilience by reducing reliance on traditional agricultural feedstocks. Growing awareness of circular practices makes this trend a defining feature of the evolving market landscape.
- For instance, CropEnergies AG expanded its portfolio in 2023 by acquiring a producer specializing in ethanol from waste and residues, reinforcing its commitment to circular economy practices and sustainable feedstocks.
Expansion of Biofuel Infrastructure and Retail Distribution:
The transportation biofuel market grows through the expansion of distribution networks and retail availability. Fuel stations increasingly offer higher biofuel blends, improving consumer accessibility. Partnerships with logistics providers ensure reliable supply chains. Advanced blending facilities enhance efficiency and lower costs. Expansion into rural areas widens adoption across agricultural communities. Infrastructure investments from oil and gas majors accelerate this trend. Standardization of fuel quality ensures consumer confidence. It benefits when biofuels are positioned as a convenient and accessible alternative at fueling stations globally. The expansion ensures that end users can adopt renewable fuels with minimal disruption.
Digitalization and Smart Refining Practices in Biofuel Production:
The transportation biofuel market embraces digital tools to optimize refining and supply chain operations. Producers use AI and IoT to monitor efficiency in bio-refineries. Predictive analytics reduce downtime and enhance process yields. Blockchain improves traceability of feedstocks, ensuring sustainability compliance. Smart logistics systems lower distribution costs and improve reliability. Automation enhances scalability of large plants, making biofuels more competitive. Integration with renewable power sources in refineries improves energy efficiency. It evolves into a more technologically advanced industry that integrates data-driven insights into production. These advancements strengthen long-term sustainability and market competitiveness.
Market Challenges Analysis:
High Production Costs and Feedstock Supply Constraints:
The transportation biofuel market faces significant challenges due to high production costs and feedstock supply uncertainties. Advanced biofuels often require expensive technologies that limit large-scale affordability. Feedstock availability fluctuates due to weather, land use conflicts, and competing demand from food industries. Supply chain complexities add volatility in pricing. Smaller producers struggle to scale because of capital-intensive operations. Land-use debates around food crops versus energy crops create resistance to adoption. Import dependencies in some regions further raise risks of supply instability. It encounters obstacles in balancing cost efficiency with consistent, sustainable production practices across regions.
Policy Uncertainty and Limited Consumer Awareness:
The transportation biofuel market encounters obstacles from inconsistent policies and low consumer awareness. Shifting political priorities sometimes weaken mandates and incentives, creating uncertainty for investors. Lack of harmonization in international standards complicates global trade of biofuels. Limited consumer knowledge about biofuel benefits slows adoption in some markets. Inadequate distribution infrastructure hinders accessibility in developing economies. Misinformation around vehicle compatibility with higher blends discourages widespread use. Policy reversals in certain countries disrupt long-term growth strategies. It struggles to achieve consistent momentum when regulations and consumer acceptance remain fragmented.
Market Opportunities:
Emerging Adoption in Developing Economies:
The transportation biofuel market holds significant opportunity in emerging economies seeking energy independence. Countries in Asia-Pacific and Latin America invest in domestic biofuel programs to reduce reliance on imported oil. Expanding vehicle ownership in these regions creates higher fuel demand, providing a strong adoption base. Governments support investments in refining facilities and distribution infrastructure. Local agriculture offers abundant feedstocks to produce biofuels sustainably. Partnerships with international players accelerate technology transfer. It gains growth momentum when developing regions adopt biofuels as part of their long-term energy strategies.
Innovation in Advanced Biofuels and Sustainable Practices:
The transportation biofuel market creates opportunities through innovation in advanced fuels and sustainable practices. Breakthroughs in algae-based fuels and cellulosic ethanol promise higher yields and lower carbon intensity. Producers explore integration with renewable power to enhance refinery sustainability. Waste-to-fuel models expand commercial feasibility and environmental benefits. Collaboration with the automotive sector accelerates compatibility testing for higher blends. Growing investor focus on ESG initiatives brings financial support for biofuel innovation. It strengthens its role as a leading renewable energy alternative by embracing cutting-edge solutions.
Market Segmentation Analysis:
By Biofuel Type
The transportation biofuel market includes ethanol, biodiesel, renewable diesel, hydrotreated vegetable oil (HVO), sustainable aviation fuel (SAF), and others. Ethanol and biodiesel remain the most established due to strong blending mandates and widespread use in road transport. Renewable diesel and HVO gain attention for their high efficiency and compatibility with existing fuel infrastructure. SAF emerges as a key growth area, driven by the aviation industry’s commitment to decarbonization. Other biofuel categories serve specialized applications with limited but steady demand.
- For instance, Renewable Energy Group (REG) launched its EnDura Fuels™ branded product line in 2022, including PuriD™, a biodiesel fuel exceeding ASTM quality standards, highlighting advancements across biofuel types to meet diverse market needs.
By Feedstock Type
Feedstock segments include oilseeds, sugar crops, starch crops, cellulosic biomass, and waste and residues. Traditional sources such as oilseeds and sugar crops dominate established production, while starch crops add to ethanol output in many regions. The growing use of cellulosic biomass and waste residues reflects the industry’s shift toward sustainability. It reduces dependence on food-based crops and strengthens circular economy practices by converting agricultural and municipal waste into fuels.
- For instance, Chevron Corporation partnered with CalBio to develop dairy biomethane projects in California, which utilize organic waste as feedstock to generate renewable natural gas, exemplifying protein-rich waste conversion in biofuel feedstocks.
By Application/End-Use Sector
Road transportation holds the largest share, supported by passenger and commercial vehicle adoption of blended fuels. Aviation represents the fastest-growing sector, where SAF adoption accelerates under global emission targets. Marine transportation shows steady interest, especially in reducing reliance on heavy fuel oils. Rail transportation presents a niche but promising avenue as countries invest in greener mobility solutions.
By Technology
Conventional biofuels such as biodiesel and bioethanol dominate due to mature infrastructure and cost advantages. Advanced biofuels derived from algae and waste biomass offer improved sustainability profiles and attract strong R&D focus. Cellulosic biofuels present long-term opportunities, supported by policy incentives and technological breakthroughs. It demonstrates a diverse technological mix that supports both current adoption and future innovation.
Segmentation:
By Biofuel Type:
- Ethanol
- Biodiesel
- Renewable Diesel
- Hydrotreated Vegetable Oil (HVO)
- Sustainable Aviation Fuel (SAF)
- Others
By Feedstock Type:
- Oilseeds
- Sugar Crops
- Starch Crops
- Cellulosic Biomass
- Waste and Residues
By Application/End-Use Sector:
- Road Transportation (passenger and commercial vehicles)
- Aviation
- Marine Transportation
- Rail Transportation
By Technology:
- Conventional Biofuels (e.g., biodiesel, bioethanol)
- Advanced Biofuels (e.g., algae and waste biomass derived)
- Cellulosic Biofuels
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the transportation biofuel market, accounting for nearly 38% of the global revenue. The region benefits from strong regulatory frameworks, high ethanol and biodiesel production, and significant investments in renewable diesel. The United States leads with large-scale corn-based ethanol and biodiesel programs, supported by the Renewable Fuel Standard (RFS). Canada reinforces growth with policies promoting low-carbon fuels and infrastructure expansion. It remains a hub for innovation in advanced biofuels, including sustainable aviation fuel projects. Strong collaborations between fuel producers, agricultural suppliers, and transportation industries ensure stable supply and adoption.
Europe
Europe represents around 30% of the transportation biofuel market, driven by strict emission reduction policies and renewable energy directives. The European Union’s Renewable Energy Directive (RED II) sets ambitious targets for renewable fuel adoption in transport. Countries such as Germany, France, and the Netherlands invest heavily in biodiesel, renewable diesel, and SAF development. The market benefits from established blending mandates and significant investments in waste-to-fuel technologies. It shows resilience as producers shift toward non-food-based feedstocks, addressing sustainability concerns. Aviation and maritime sectors in Europe further strengthen demand as regional regulations push for decarbonization.
Asia-Pacific and Other Regions
Asia-Pacific holds nearly 24% of the transportation biofuel market and emerges as the fastest-growing region. China and India invest in domestic biofuel programs to reduce oil imports and improve energy security. Rising vehicle ownership, rapid urbanization, and government-backed renewable energy policies stimulate demand. Southeast Asian countries such as Indonesia and Malaysia contribute through palm oil-based biodiesel production. Latin America, led by Brazil, accounts for about 6% and remains a global leader in sugarcane-based ethanol. The Middle East & Africa contribute nearly 2%, with growth potential tied to abundant agricultural resources and emerging renewable energy initiatives. It highlights a diverse regional landscape where developed and developing markets adopt biofuels at different scales.
Key Player Analysis:
- Neste Nederland BV
- Archer Daniels Midland Company (ADM)
- Renewable Energy Group, Inc. (REG)
- Chevron Corporation
- Valero Energy Corporation
- CropEnergies AG
- Louis Dreyfus Company
- Bunge Limited
- Marathon Petroleum Corporation
- World Energy, LLC
- Enerkem
- Ineos Group AG
- Gevo, Inc.
Competitive Analysis:
The transportation biofuel market features strong competition among global energy companies, agricultural firms, and specialized biofuel producers. It includes established oil and gas corporations investing in renewable fuels alongside dedicated biofuel firms scaling production capacity. Companies compete on feedstock innovation, cost efficiency, and distribution reach. Partnerships between fuel producers and transportation industries accelerate adoption across aviation, marine, and road segments. Differentiation arises from technological advances in advanced and cellulosic biofuels, enabling lower carbon intensity. Strategic acquisitions and global supply chain expansion also shape the market landscape. It demonstrates a competitive balance between incumbents with resources and emerging innovators with advanced processes.
Recent Developments:
- Gevo, Inc. partnered with ADM to produce sustainable aviation fuel, leveraging ADM’s ethanol production facilities to scale SAF output expected around 2026.
- In 2022, Neste Nederland BV celebrated several acquisitions, including Walco Foods in Ireland and a US-based used cooking oil collection business, expanding their feedstock sourcing platform for renewable fuels. Alongside, Neste launched a strategic study for transforming their Porvoo refinery into a leading renewable solutions site aimed at full renewal feedstock utilization. Neste also initiated partnerships with multiple global companies, such as Rolls-Royce and Coca-Cola Europacific Partners, to promote their MY Renewable Diesel and Sustainable Aviation Fuel (SAF) products. By April 2025, Neste started producing SAF at its Rotterdam refinery, scaling its production capacity to 1.5 million tons annually.
Market Concentration & Characteristics:
The transportation biofuel market shows moderate to high concentration, with a mix of global energy leaders and specialized biofuel firms holding significant market presence. It is characterized by strong policy-driven demand, steady investment flows, and technological advancements in advanced biofuels. Key players expand their operations through acquisitions, feedstock diversification, and capacity building. The market is highly regulated, and competitive differentiation often depends on compliance, sustainability credentials, and global supply chain strength. It maintains resilience due to its ability to serve multiple transportation sectors and adapt to evolving emission reduction mandates.
Report Coverage:
The research report offers an in-depth analysis based on biofuel type, feedstock type, application, and technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for sustainable aviation fuels to meet global emission targets.
- Expansion of renewable diesel capacity across North America and Europe.
- Greater use of waste and residue feedstocks to ensure sustainable supply.
- Accelerated adoption in emerging economies to reduce oil import dependence.
- Ongoing technological breakthroughs in algae-based and cellulosic biofuels.
- Strategic partnerships between fuel producers and transportation industries.
- Growth in circular economy practices through waste-to-fuel innovations.
- Increased investment by oil and gas majors in renewable portfolios.
- Regulatory frameworks tightening to enforce higher blending mandates.
- Broader consumer adoption driven by improved distribution infrastructure.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Regulations and Policy Support
Stringent regulatory frameworks, blending mandates, and subsidies in major markets create predictable demand for biofuels, encouraging large-scale investments and supporting the transition away from fossil fuels. These policies lower risks for producers and accelerate adoption across transportation sectors.
Decarbonization and Emission Reduction Targets
Global commitments to reduce greenhouse gas emissions, especially in the transportation sector, are driving the adoption of biofuels as a low-carbon alternative. Aviation and maritime industries, in particular, are increasingly integrating biofuels to comply with international emission standards.
Technological Advancements in Feedstock and Refining
Innovations in converting non-food feedstocks such as agricultural residues, municipal waste, and algae into biofuels are improving sustainability and reducing reliance on traditional crops. Enhanced refining technologies and digitalization are making production more efficient and cost-effective.
Strategic Investments and Private Sector Participation
Major energy companies and private investors are expanding into biofuels, funding new production facilities, and forming partnerships with transportation and agricultural sectors. This influx of capital and expertise is scaling up production and distribution infrastructure globally.
Expansion of Biofuel Infrastructure and Distribution
The growth of blending facilities, retail distribution networks, and logistics partnerships is making biofuels more accessible to end users. Improved infrastructure supports broader consumer adoption and ensures reliable supply across diverse regions and transportation modes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Transportation biofuel market, and what is its projected size in 2032?
Which Transportation biofuel market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Transportation biofuel market?
Who are the leading companies in the Transportation biofuel market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Conventional Biofuels
- 1.2.2 Advanced Biofuels
- 1.2.3 Cellulosic Biofuels
- 1.3 By Biofuel Type
- 1.3.1 Ethanol
- 1.3.2 Biodiesel
- 1.3.3 Renewable Diesel
- 1.3.4 Hydrotreated Vegetable Oil (HVO)
- 1.3.5 Sustainable Aviation Fuel (SAF)
- 1.3.6 Others
- 1.4 By Feedstock Type
- 1.4.1 Oilseeds
- 1.4.2 Sugar Crops
- 1.4.3 Starch Crops
- 1.4.4 Cellulosic Biomass
- 1.4.5 Waste and Residues
- 1.5 By Application/End-Use Sector
- 1.5.1 Road Transportation
- 1.5.2 Aviation
- 1.5.3 Marine Transportation
- 1.5.4 Rail Transportation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 101.9 billion → 2032: USD 234.8 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Transportation Biofuel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Transportation Biofuel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Transportation Biofuel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Transportation Biofuel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Transportation Biofuel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Transportation Biofuel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Transportation Biofuel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Transportation Biofuel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 101.9 billion → 2032: USD 234.8 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Transportation Biofuel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Conventional Biofuels
- 12.3.7.2 Advanced Biofuels
- 12.3.7.3 Cellulosic Biofuels
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Biofuel Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ethanol
- 12.4.7.2 Biodiesel
- 12.4.7.3 Renewable Diesel
- 12.4.7.4 Hydrotreated Vegetable Oil (HVO)
- 12.4.7.5 Sustainable Aviation Fuel (SAF)
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Feedstock Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oilseeds
- 12.5.7.2 Sugar Crops
- 12.5.7.3 Starch Crops
- 12.5.7.4 Cellulosic Biomass
- 12.5.7.5 Waste and Residues
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application/End-Use Sector - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Road Transportation
- 12.6.7.2 Aviation
- 12.6.7.3 Marine Transportation
- 12.6.7.4 Rail Transportation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Transportation Biofuel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Transportation Biofuel Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Transportation Biofuel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Transportation Biofuel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Neste Nederland BV
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Archer Daniels Midland Company (ADM)
- 18.4 Renewable Energy Group, Inc. (REG)
- 18.5 Chevron Corporation
- 18.6 Valero Energy Corporation
- 18.7 CropEnergies AG
- 18.8 Louis Dreyfus Company
- 18.9 Bunge Limited
- 18.10 Marathon Petroleum Corporation
- 18.11 World Energy, LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

